As the Affordable Care Act (ACA) Marketplace prepares to open its doors for the 2027 enrollment period on November 1, 2026, millions of Americans find themselves facing a transformed and increasingly complex health insurance landscape. Following the expiration of enhanced premium tax credits in 2026 and the implementation of the "One Big Beautiful Bill Act"—the 2025 federal budget reconciliation law—the individual market is undergoing its most significant structural shift in over a decade.
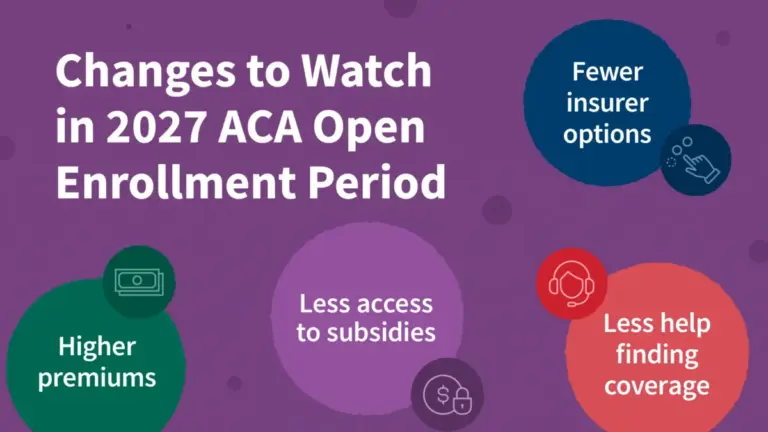
From double-digit premium hikes to new eligibility restrictions and aggressive anti-fraud measures, the 2027 enrollment season presents a challenging environment for both returning enrollees and new applicants.
1. The Financial Reality: Double-Digit Premium Hikes
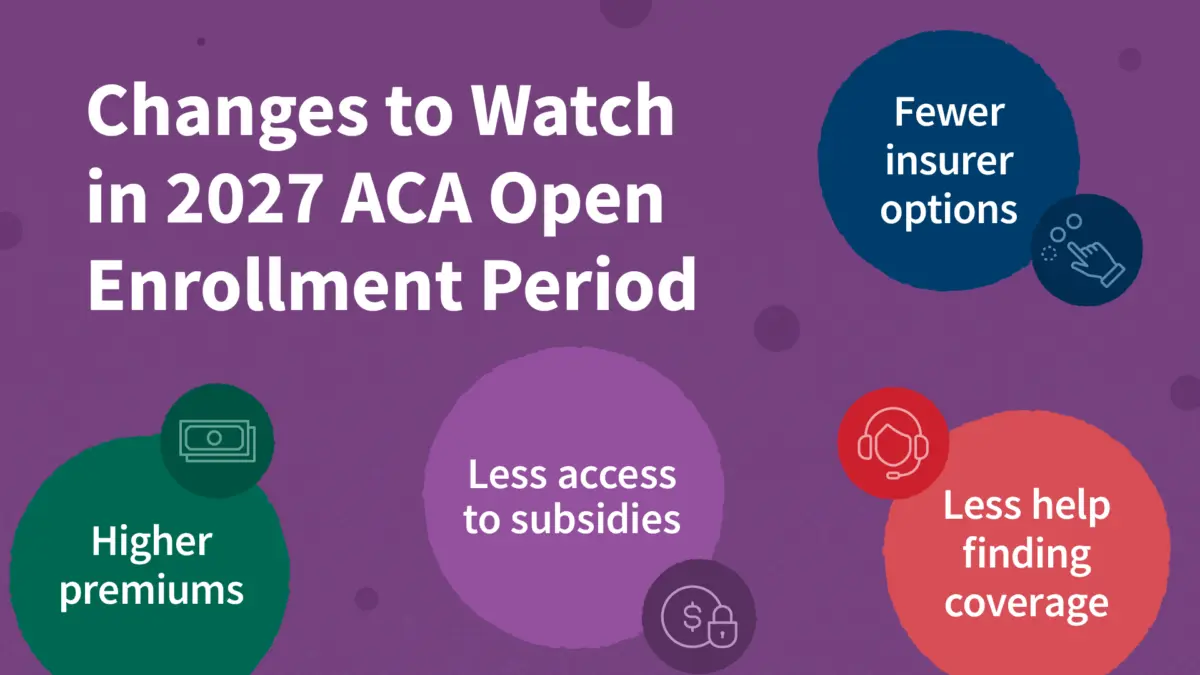
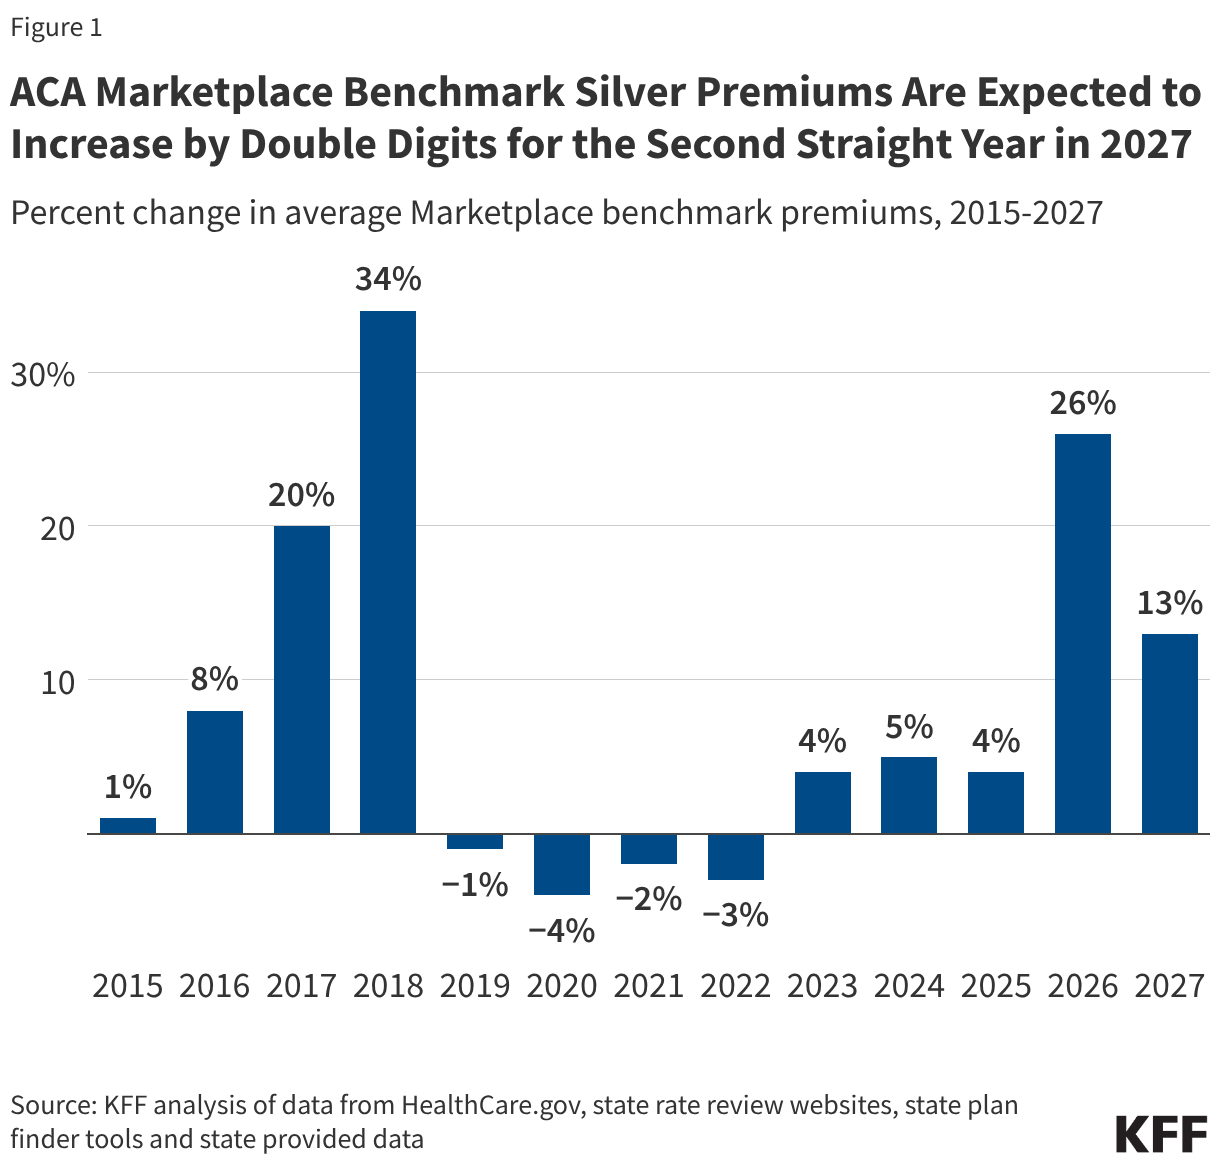
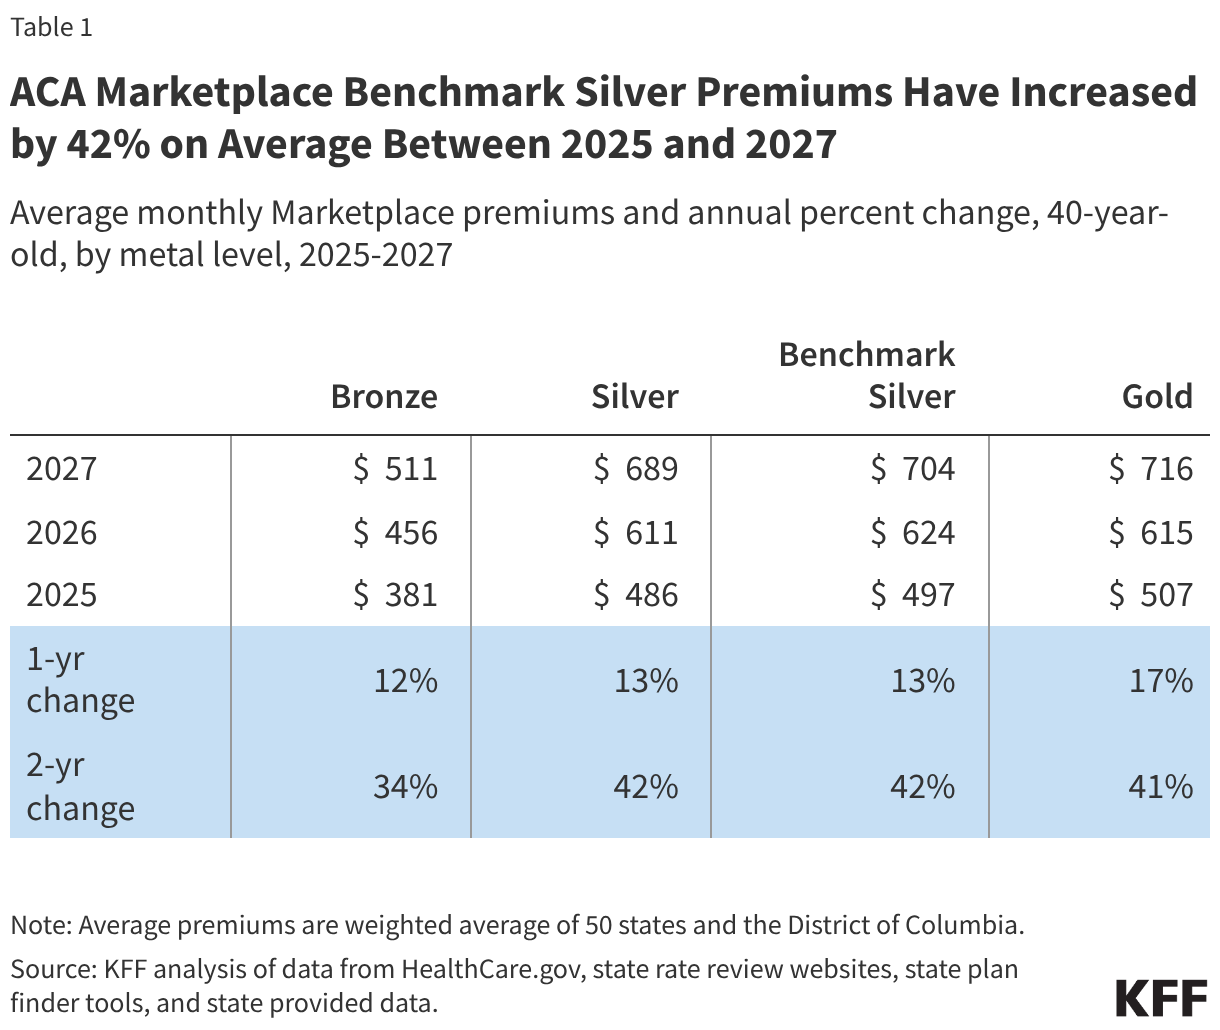
The most immediate hurdle for consumers in 2027 is the surge in insurance premiums. Insurers have finalized an average benchmark silver premium increase of 13%, following a staggering 26% jump between 2025 and 2026. This trend is not isolated; states operating their own enrollment platforms report even steeper average increases of 16%, while those utilizing the federal Healthcare.gov platform are seeing an 11% rise.
Why Are Costs Escalating?
Insurers attribute these spikes to three primary drivers:
- Medical Inflation: Underlying costs for healthcare services have risen significantly, a trend mirrored in employer-sponsored health plans.
- Risk Pool Volatility: The expiration of enhanced premium tax credits has altered the demographics of the risk pool. Healthier enrollees are increasingly opting out, leaving a higher concentration of individuals with significant medical needs, which forces insurers to raise rates to cover projected claims.
- Policy Shifts: The ongoing implementation of Trump administration regulations and the budgetary constraints of the 2025 reconciliation law have removed previous financial buffers, forcing the market to adjust to a new, unsubsidized reality.
While subsidies remain available for many, those with incomes above 400% of the federal poverty level (FPL) are particularly vulnerable, as they are no longer shielded by premium tax credits and must absorb the full force of these price increases.
2. A Chronology of Market Contraction
The current state of the Marketplace is the result of a two-year decline triggered by the erosion of federal support.
- 2025: The ACA Marketplace reached a historic peak of 22.4 million enrollees, supported by generous pandemic-era tax credits.
- 2026: The expiration of these enhanced tax credits caused an immediate contraction. Marketplace plan selections plummeted by 1.2 million during the open enrollment period. By mid-2026, the broader individual market had shed 4.6 million enrollees, a decline of 18%.
- 2027: The trend is expected to continue. Insurers are exiting states at a higher rate than they are entering, citing market instability. As of October 2026, 11 carriers have announced plans to exit at least one state, significantly limiting consumer choice and network availability in some regions.
The Congressional Budget Office (CBO) now projects that total Marketplace enrollment will fall to 13.1 million by the end of 2027, effectively erasing the gains of the previous four years.
3. Supporting Data: The Impact of Policy Shifts
The impact of these policy changes is uneven, creating a "geographic lottery" for health insurance affordability.
State-Based Backfilling
Some states have moved to protect their residents from federal policy shifts. New Mexico has led the charge by fully backfilling the lost federal assistance, resulting in localized enrollment growth. Others, like California, have expanded their state-funded subsidy programs to cover households between 165% and 200% FPL. Conversely, residents in states without such initiatives face the full, unmitigated impact of the federal withdrawal.
The Fraud Crackdown
In September 2026, the Department of Health and Human Services (HHS) took drastic action to purge the system of "phantom enrollees"—individuals signed up by brokers without their knowledge. Approximately 760,000 enrollments were cancelled. While these measures aim to protect the integrity of the Marketplace, they have created collateral damage; legitimate enrollees have been caught in the crossfire, and the resulting administrative burden has made it significantly more difficult for consumers to access reliable broker services.
4. Official Perspectives and Regulatory Responses
The federal government maintains that these changes are necessary for long-term fiscal sustainability. HHS officials emphasize that the new requirements for brokers—including the prohibition of cash rebates and the requirement to submit marketing materials for federal audit—are essential to curb the "predatory" enrollment tactics that characterized the 2025-2026 period.
However, the industry is pushing back. The current environment is defined by ongoing litigation. Cases such as City of Columbus v. Kennedy have challenged the 2025 program integrity rules and the 2027 Payment Notice. These legal battles have resulted in temporary stays on various provisions, creating a climate of uncertainty for insurers attempting to set their rates and for consumers trying to understand their eligibility.
5. Implications: The "New Normal" for Enrollees
The 2027 enrollment period introduces several structural changes that consumers must navigate:
The End of Repayment Limits
Under the 2025 budget reconciliation law, the caps on how much an enrollee must repay in excess premium tax credits have been eliminated. For the first time in early 2027, taxpayers will face the reality of "uncapped" repayment. Individuals with volatile incomes, such as gig workers or seasonal laborers, face a high risk of unexpected tax bills if their annual income exceeds projections.
Medicaid Work Requirements
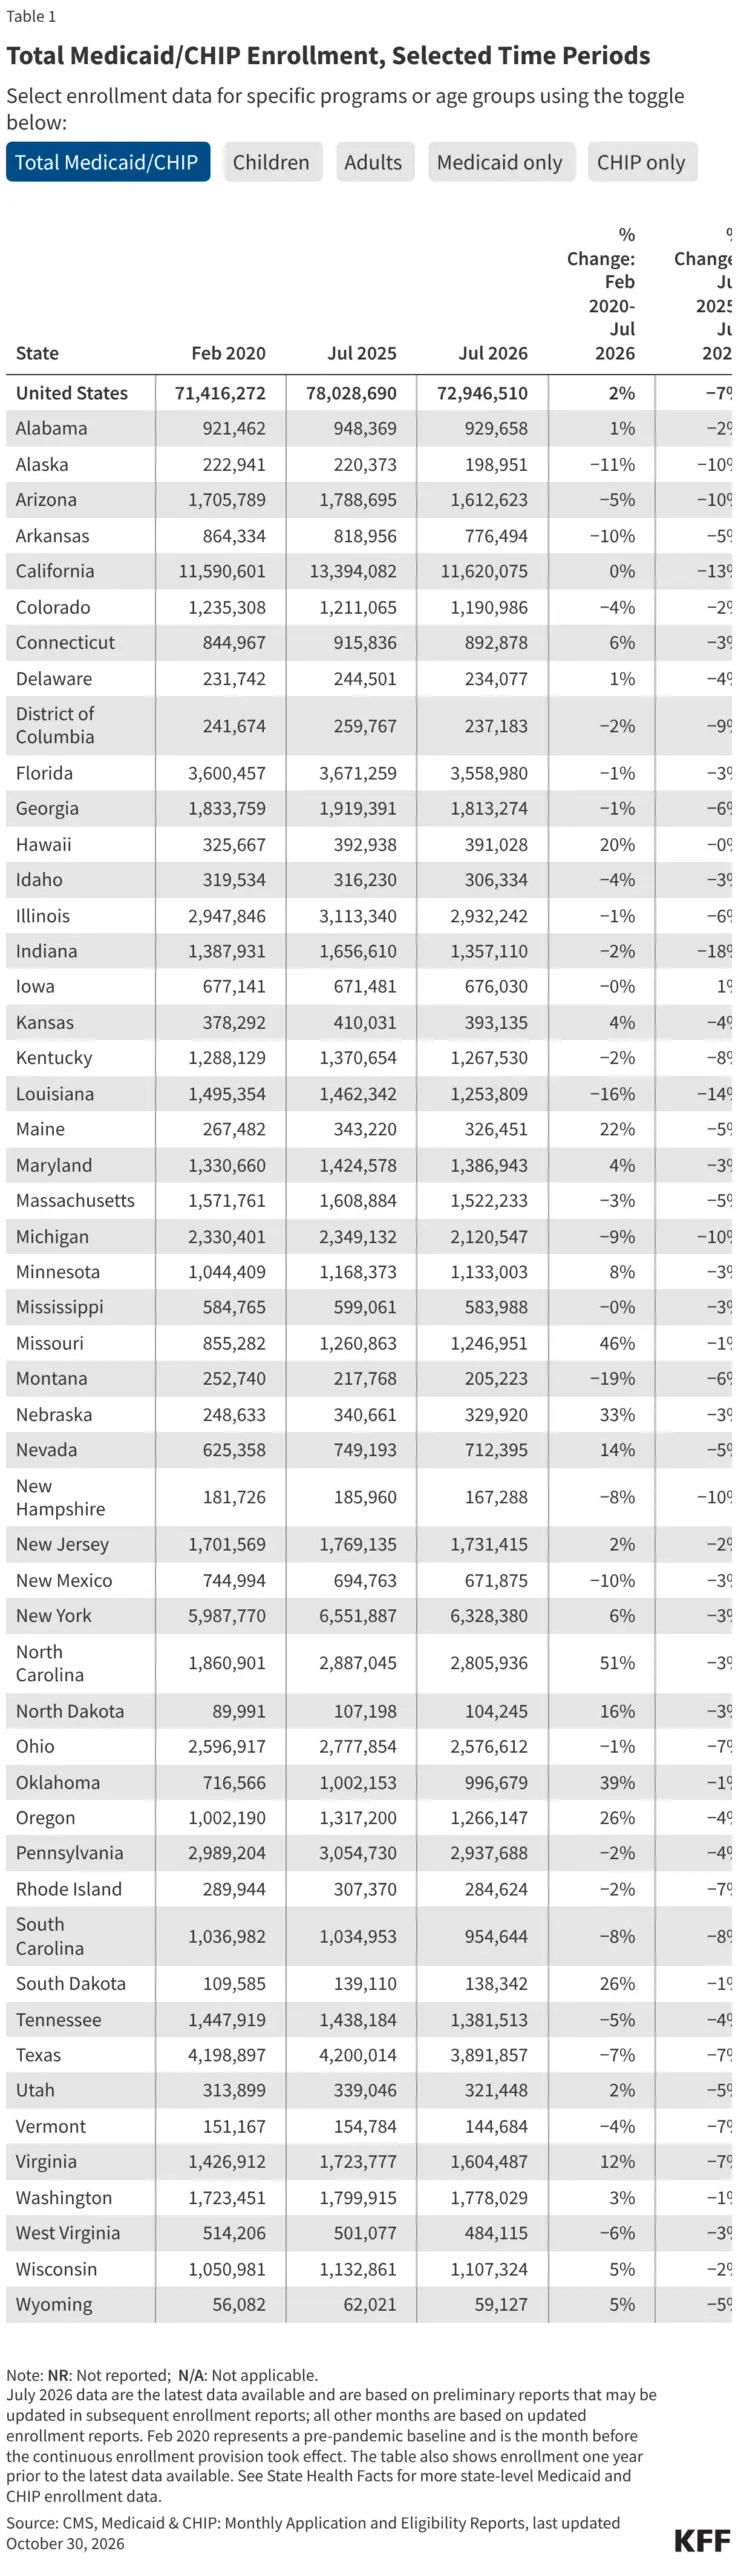
Perhaps the most contentious shift is the intersection of Medicaid and the Marketplace. With 43 states now required to implement Medicaid work requirements, individuals who lose their Medicaid coverage due to non-compliance are now also ineligible for ACA premium tax credits. This creates a "coverage gap" where low-income individuals may find themselves without a safety net, ineligible for both the program they were previously on and the subsidized private coverage they might have otherwise accessed.
Immigration Eligibility Restrictions
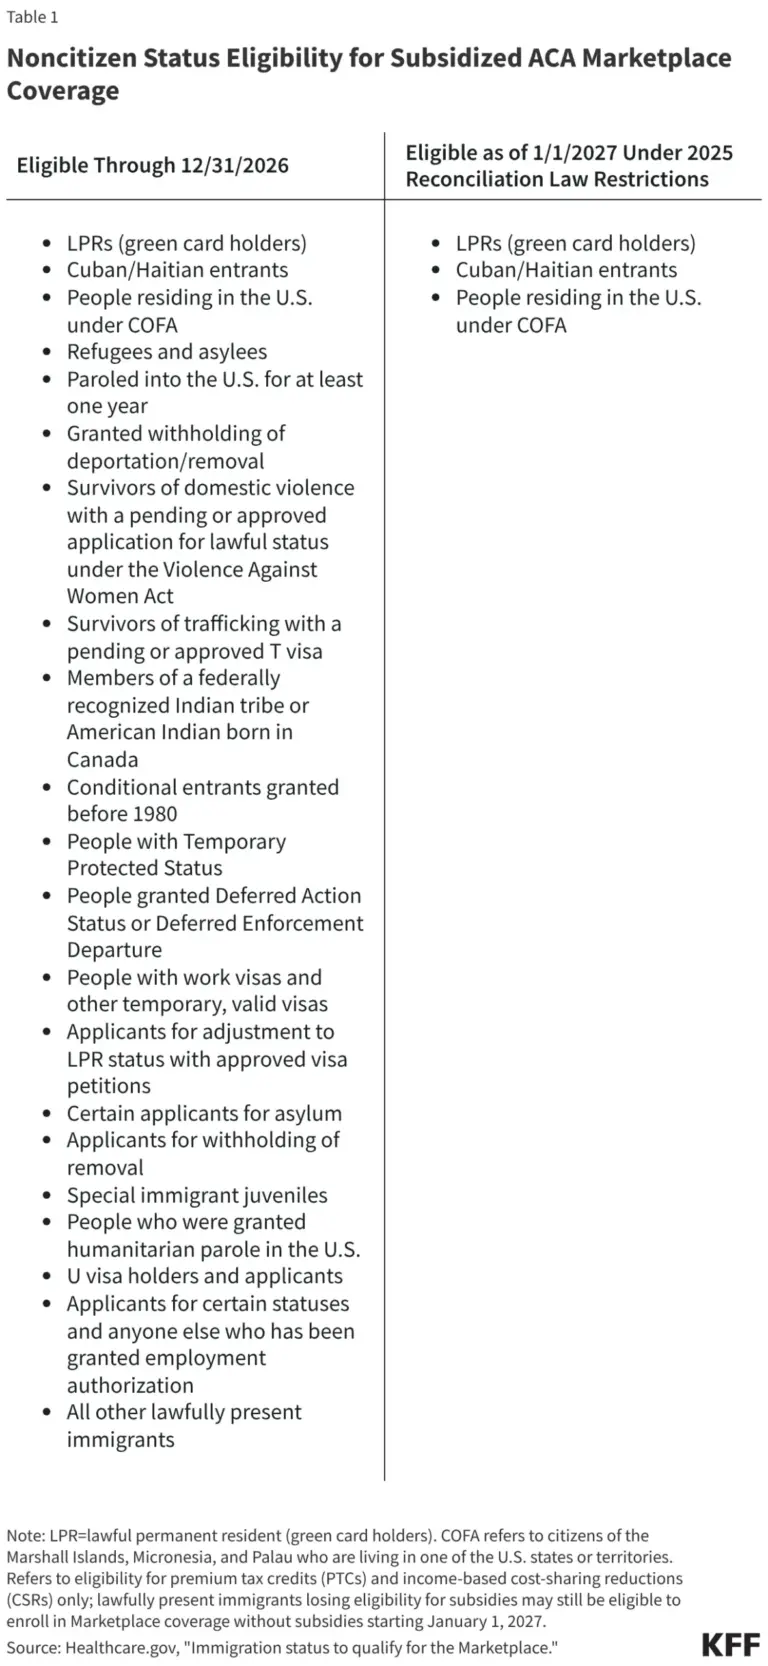
Lawfully present immigrants—including refugees and asylees—are seeing their access to subsidized coverage restricted. While they remain eligible to purchase private insurance at full cost, the loss of tax credit eligibility is expected to force many into the ranks of the uninsured, with the CBO estimating an increase of one million uninsured individuals by 2035 directly linked to these provisions.
Conclusion
As the 2027 Open Enrollment period commences, the message to consumers is clear: do not rely on the previous years’ math. The combination of rising premiums, the loss of federal tax credit protections, and the administrative hurdles created by anti-fraud crackdowns makes active participation and careful planning essential.
Consumers are strongly encouraged to re-verify their income estimates, check if their state provides supplementary subsidies, and be wary of third-party agents promising "zero-dollar" plans, which may now be subject to stricter federal oversight or, in some cases, outright fraud. The American health insurance market is in the midst of a profound correction, and for the foreseeable future, the onus of navigating this complexity lies squarely on the shoulders of the enrollee.
About the Author