Editorial Note: This report was updated on October 23, 2026, to integrate the most recent polling data from KFF. The original analysis was published on December 14, 2021.
For years, the American health care system has operated under a cloud of fiscal anxiety. While medical innovation continues to reach new heights, the financial accessibility of that care remains a persistent, systemic barrier for millions of families. According to the latest data from KFF, health care costs have cemented their position as the primary financial concern for U.S. adults, frequently outpacing worries over gas, housing, and food. This crisis is no longer confined to the uninsured; it has permeated the lives of the insured and the middle class, forcing difficult trade-offs that are actively eroding the public’s health.
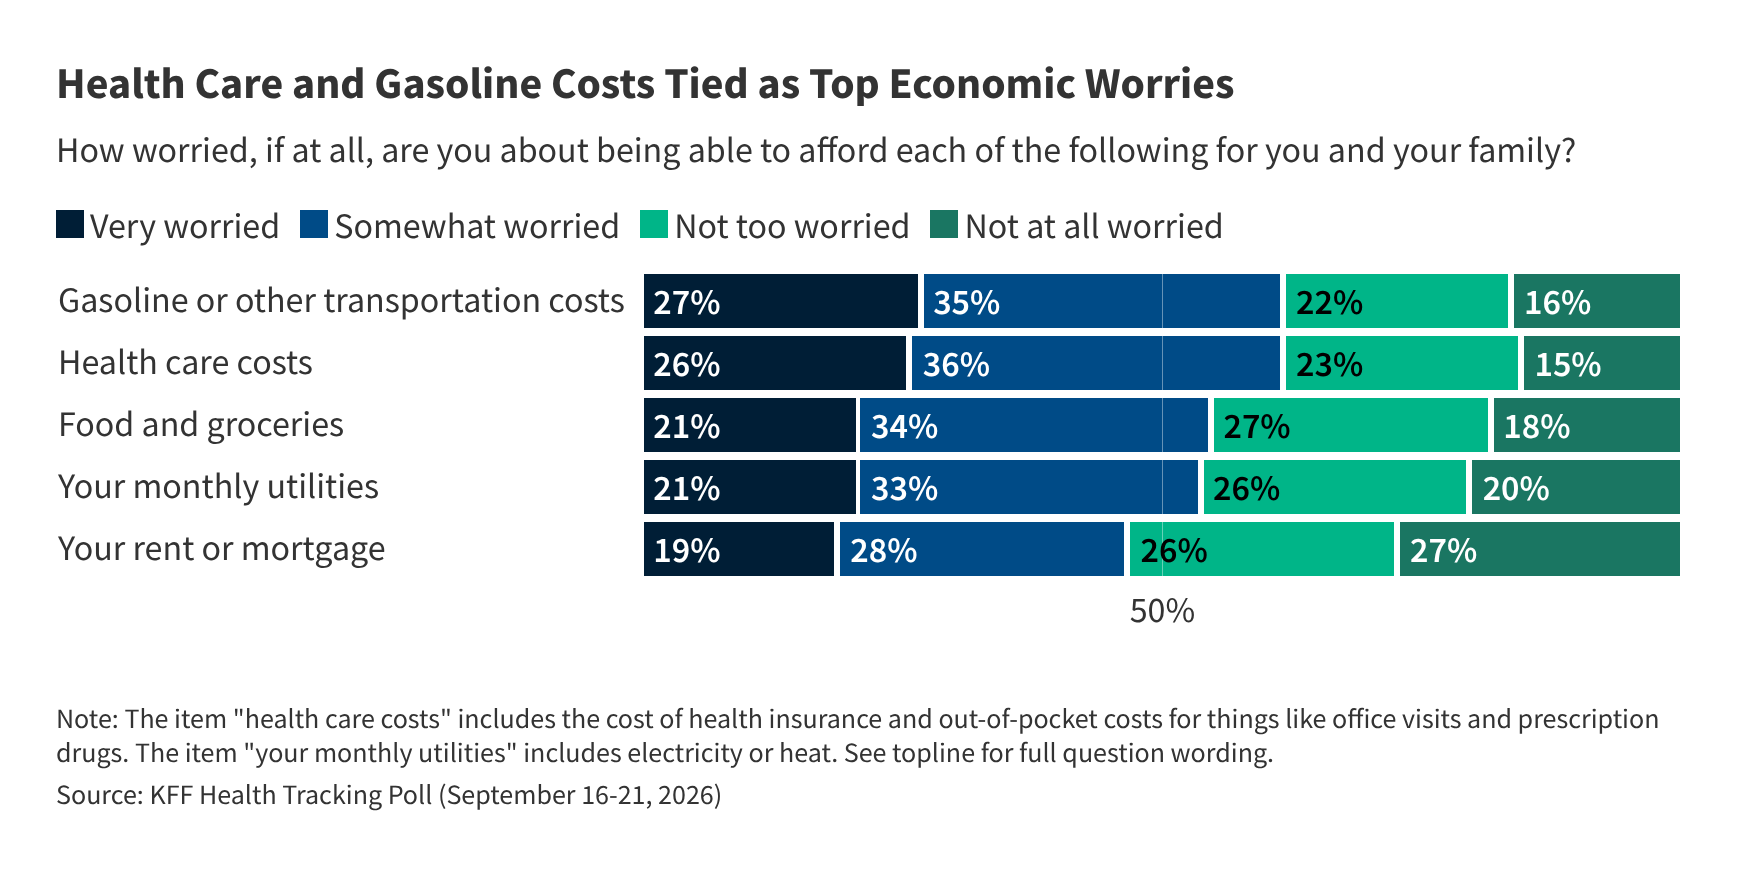
The Landscape of Economic Anxiety: A Chronology of Concern
The trajectory of public concern regarding health care affordability has seen a steady, troubling climb over the past half-decade.
- December 2021: KFF reports initial findings that health care costs are the leading financial worry for U.S. families, with significant portions of the population reporting that these costs influence their decision to delay or skip medical care.
- February–March 2022: The Diagnosis Debt investigative project, a collaboration between KFF and NPR, reveals that 41% of U.S. adults carry some form of medical or dental debt.
- July 2023: Data indicates that the practice of rationing prescription medication—cutting pills or skipping doses—is becoming a common coping mechanism for patients facing rising costs.
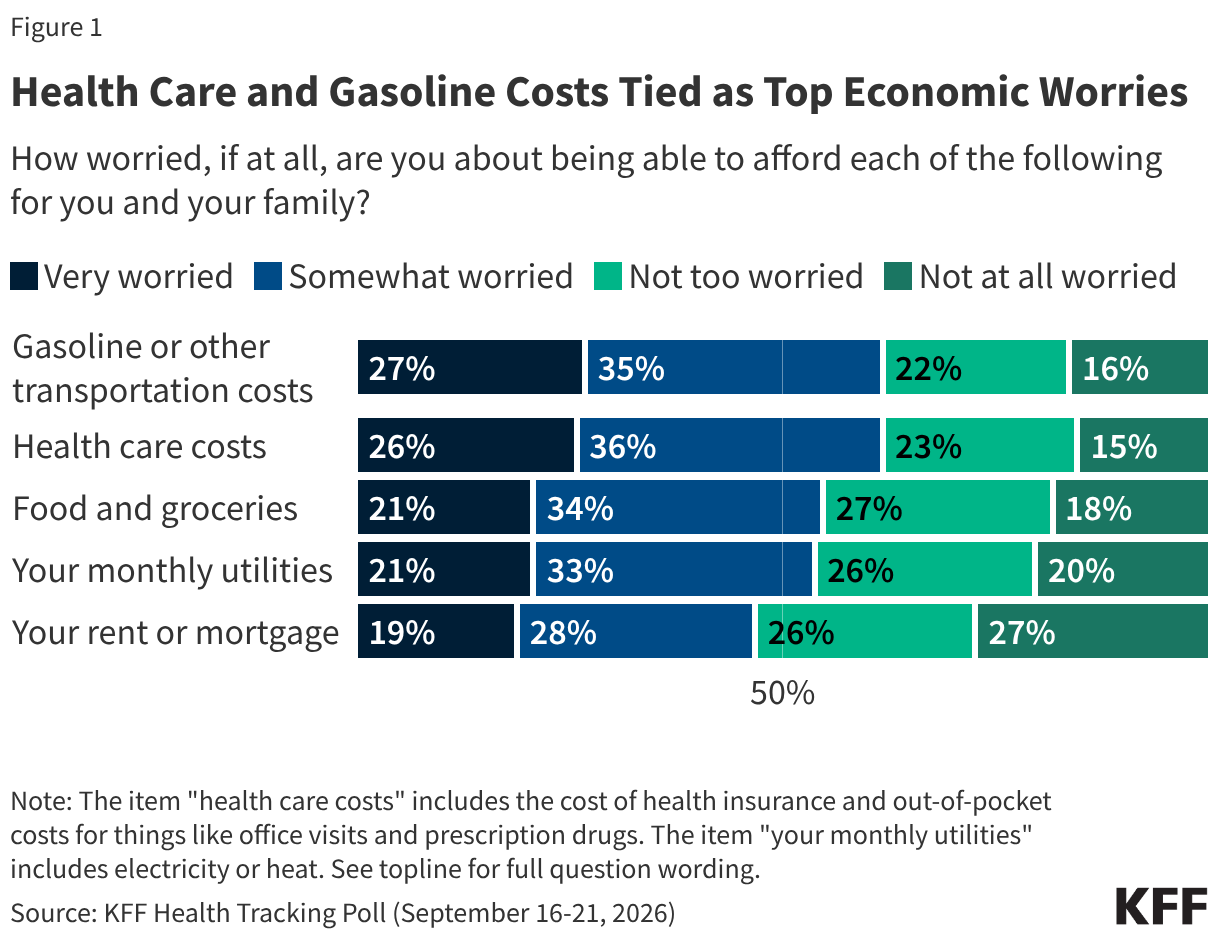
- May 2025: Polling confirms that 44% of U.S. adults find it difficult to afford their health care, with stark disparities emerging across racial and income lines.
- October 2026: In the lead-up to the midterm elections, 62% of adults report being “very” or “somewhat” worried about affording health care costs, confirming that the issue remains a defining political and economic challenge.
Supporting Data: The Anatomy of Affordability
The data reveals that the burden of health care is not distributed equally. It is a weight that presses hardest on those already operating on the margins of financial stability, yet it is heavy enough to crush the security of those in the middle class.
The Difficulty of Access
While 82% of uninsured adults under 65 report difficulty in affording care, the crisis is pervasive among the insured as well. Roughly 42% of those with health insurance coverage report struggling to meet their medical financial obligations. This "under-insurance" phenomenon—where coverage exists but deductibles and out-of-pocket maximums remain prohibitively high—is a primary driver of the current crisis.
Furthermore, demographic data highlights deep inequities:
- Race and Ethnicity: 55% of Hispanic adults and 49% of Black adults report significant difficulty affording care, compared to 39% of White adults.
- Income Disparities: Households earning under $40,000 annually are the most vulnerable, though the "middle-class squeeze" is increasingly evident as costs for premiums and co-pays rise faster than wages.
The Prescription Drug Dilemma
Perhaps the most visceral indicator of this crisis is the trend in prescription drug management. In 2026, 43% of adults reported taking at least one measure to lower medication costs—such as opting for over-the-counter alternatives, not filling prescriptions, or skipping doses. This represents a substantial increase from 33% in 2025 and 31% in 2023. When patients begin rationing life-saving medication, the cost of the "solution" is the eventual, preventable decline of their physical health.
The Human Toll: Skipping Care and Worsened Outcomes
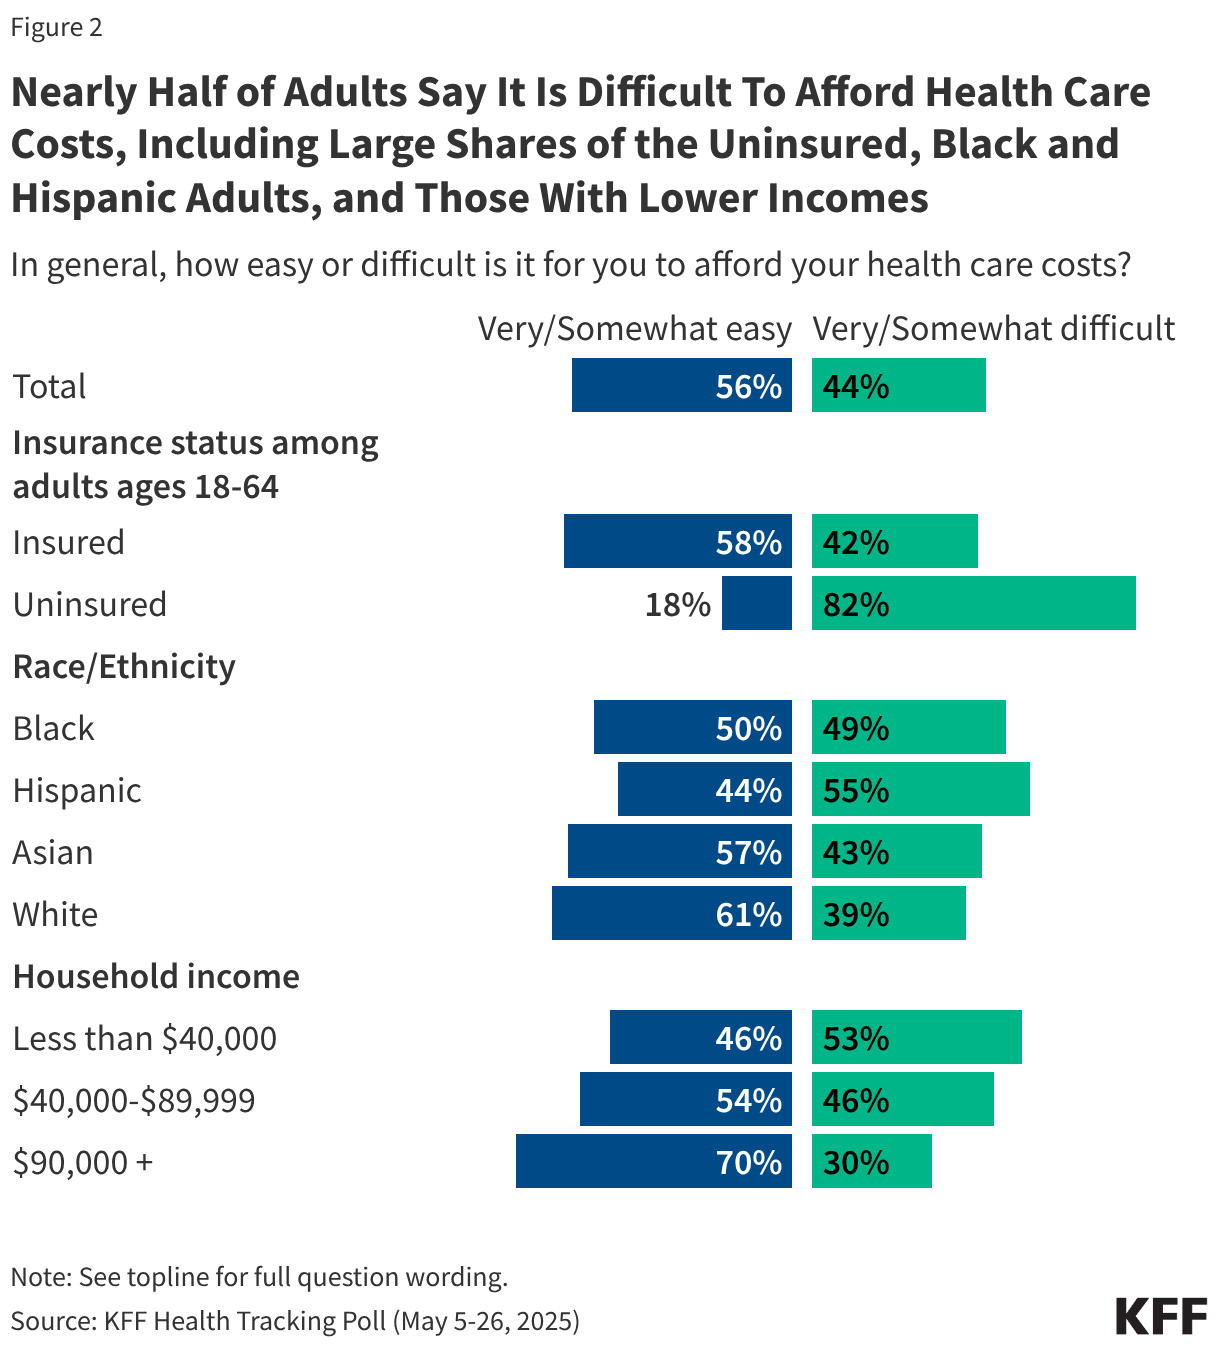
The most critical implication of high health care costs is the phenomenon of "deferred care." Approximately 28% of adults have skipped or postponed needed medical services in the past 12 months due to cost.
The Cumulative Health Impact
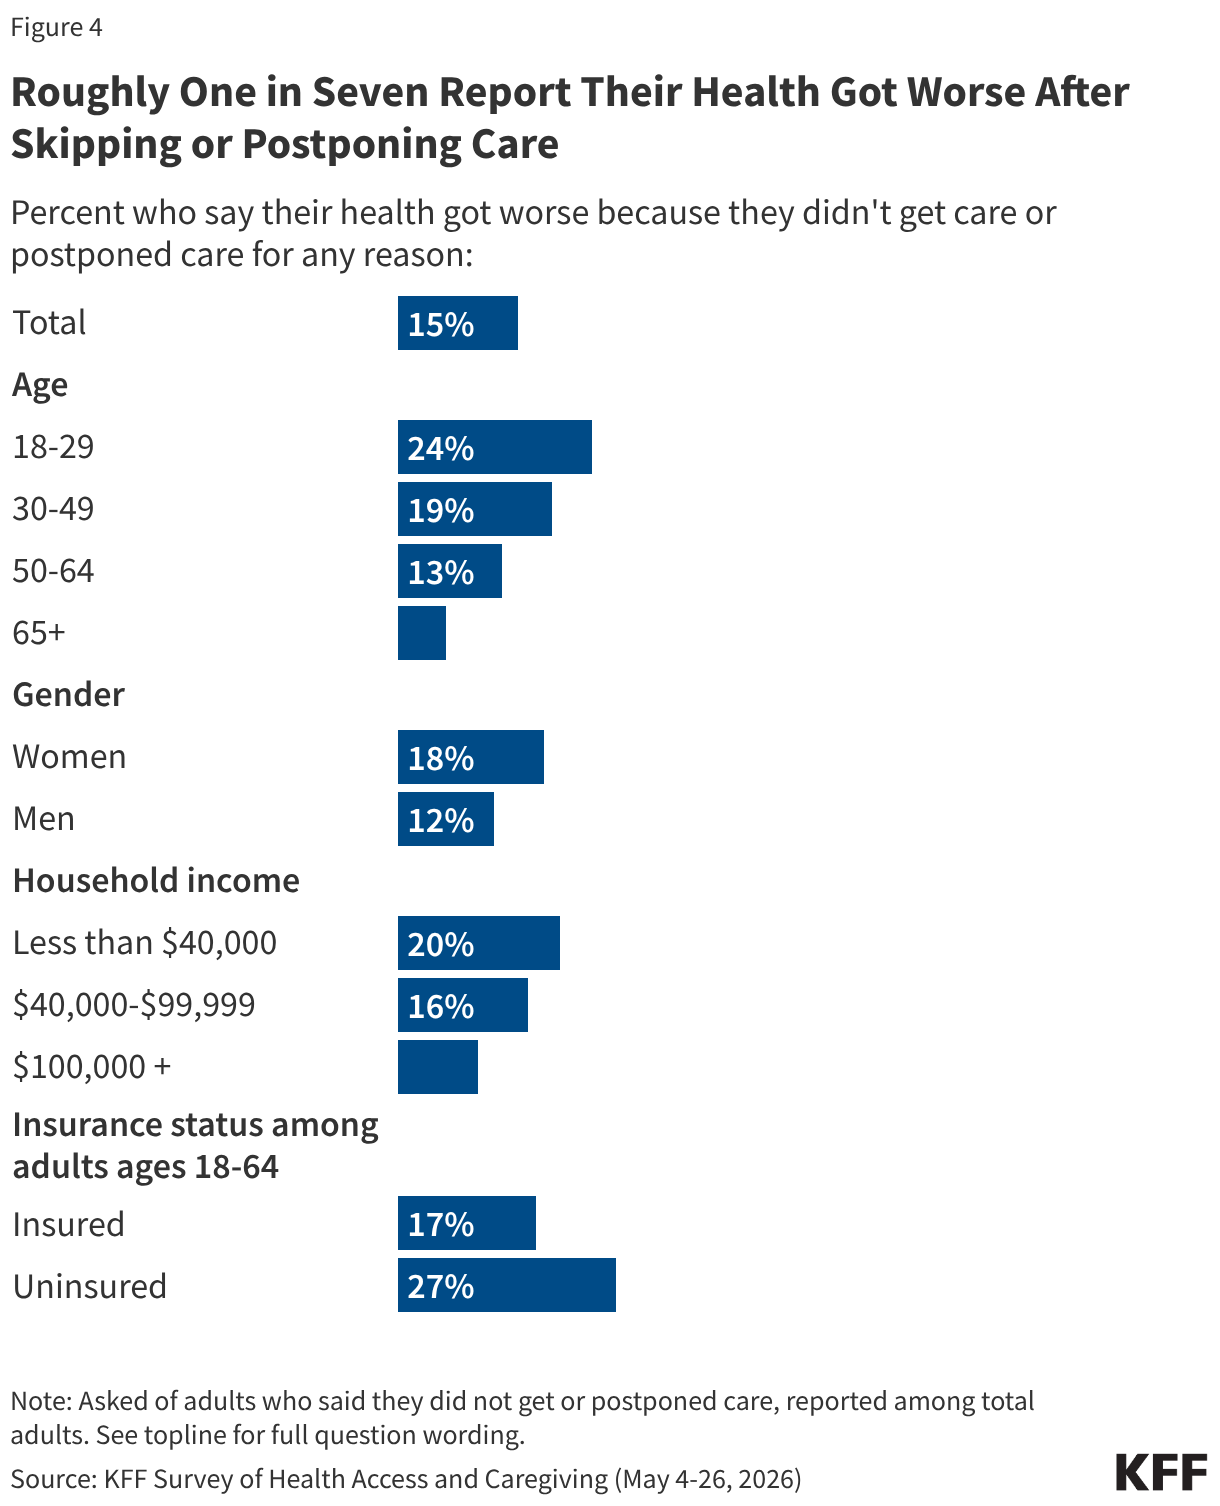
Skipping care is not a neutral act; it is a gamble with long-term health. Roughly 15% of all adults report that their health deteriorated because they could not access care when they needed it. Among uninsured adults under 65, this figure rises to 27%.
Age also plays a significant role in these outcomes. Adults under 30 are four times more likely than those 65 and older to report that their health worsened after skipping care. This highlights the vital role of Medicare; by providing near-universal, stable coverage, it shields the elderly from the catastrophic health outcomes caused by financial barriers to entry.
Vulnerable Populations: LGBTQ+ and Chronic Conditions
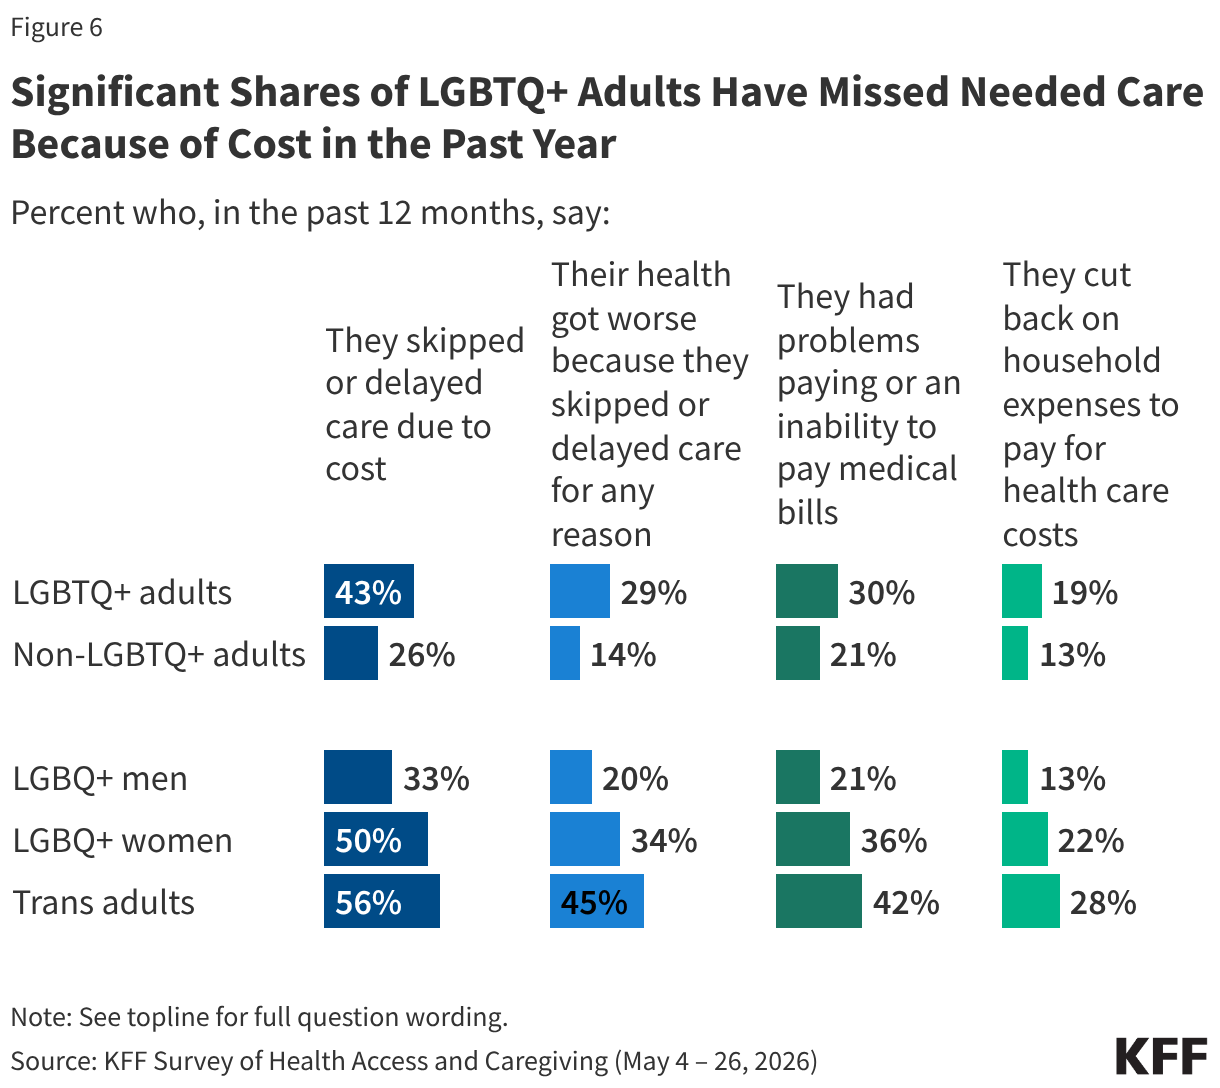
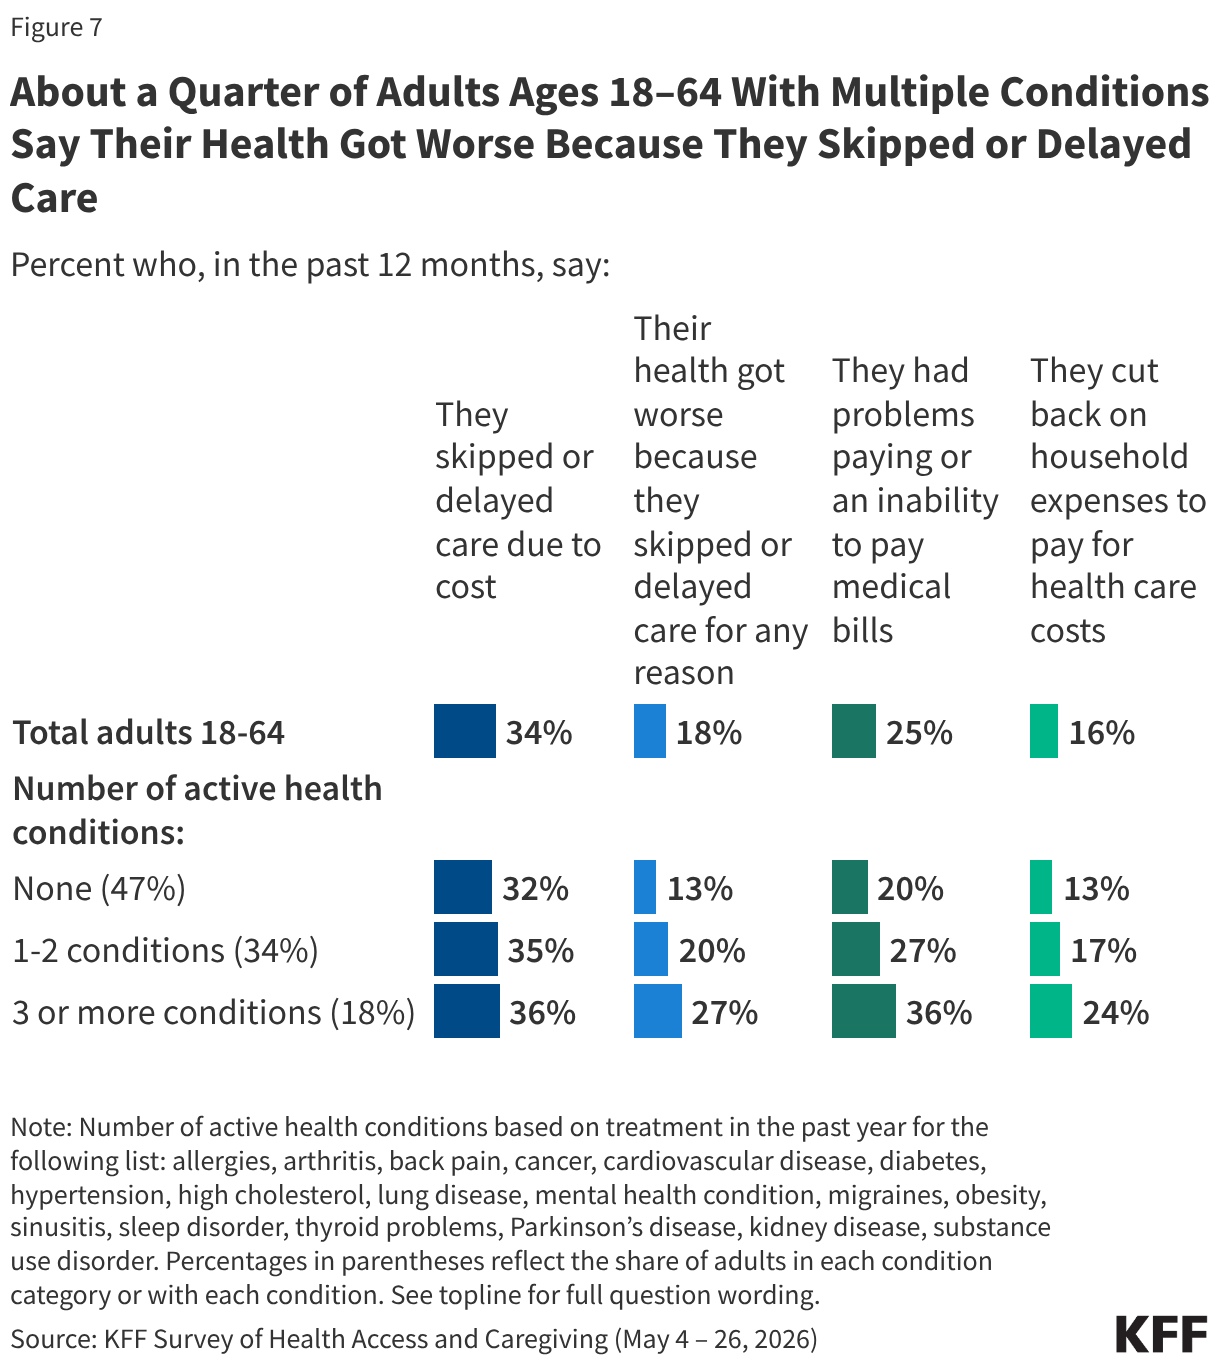
The crisis is particularly acute for the LGBTQ+ community and those living with multiple chronic conditions. More than 43% of LGBTQ+ adults report delaying care due to cost, with the figure rising to 56% among transgender adults. These populations, who often face structural barriers to employment and insurance access, are trapped in a cycle where financial instability directly undermines their physical well-being. Similarly, 36% of adults under 65 with three or more chronic conditions report an inability to access necessary care, creating a feedback loop where lack of maintenance leads to more complex, expensive, and debilitating health issues.
Official Responses and Systemic Implications
The current state of health care affordability has profound implications for the U.S. economy and the social contract.
The Debt Cycle
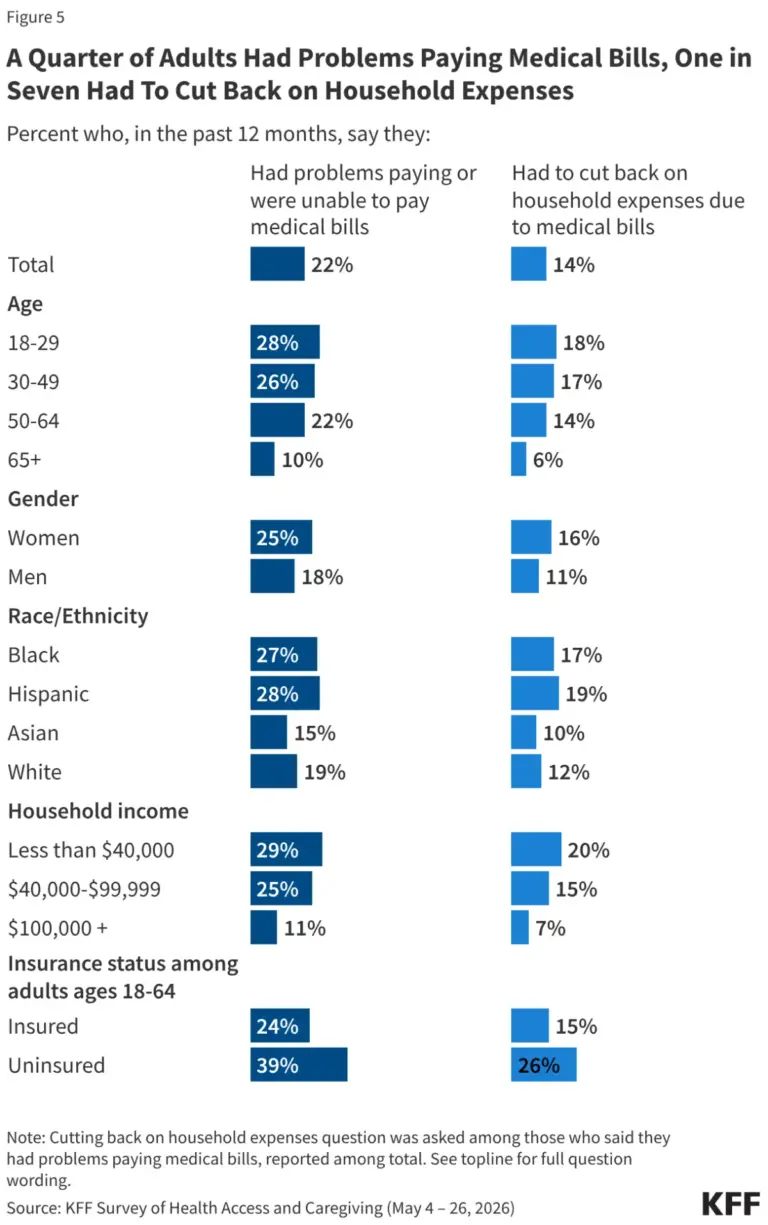
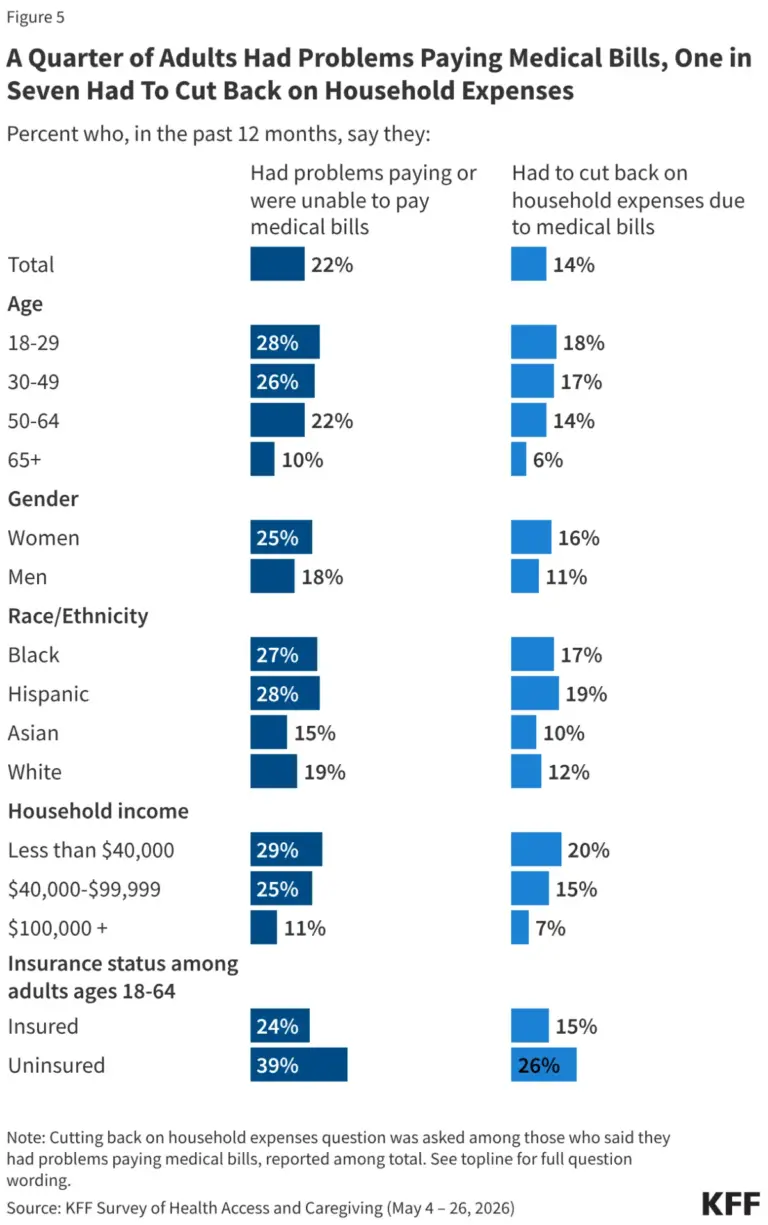
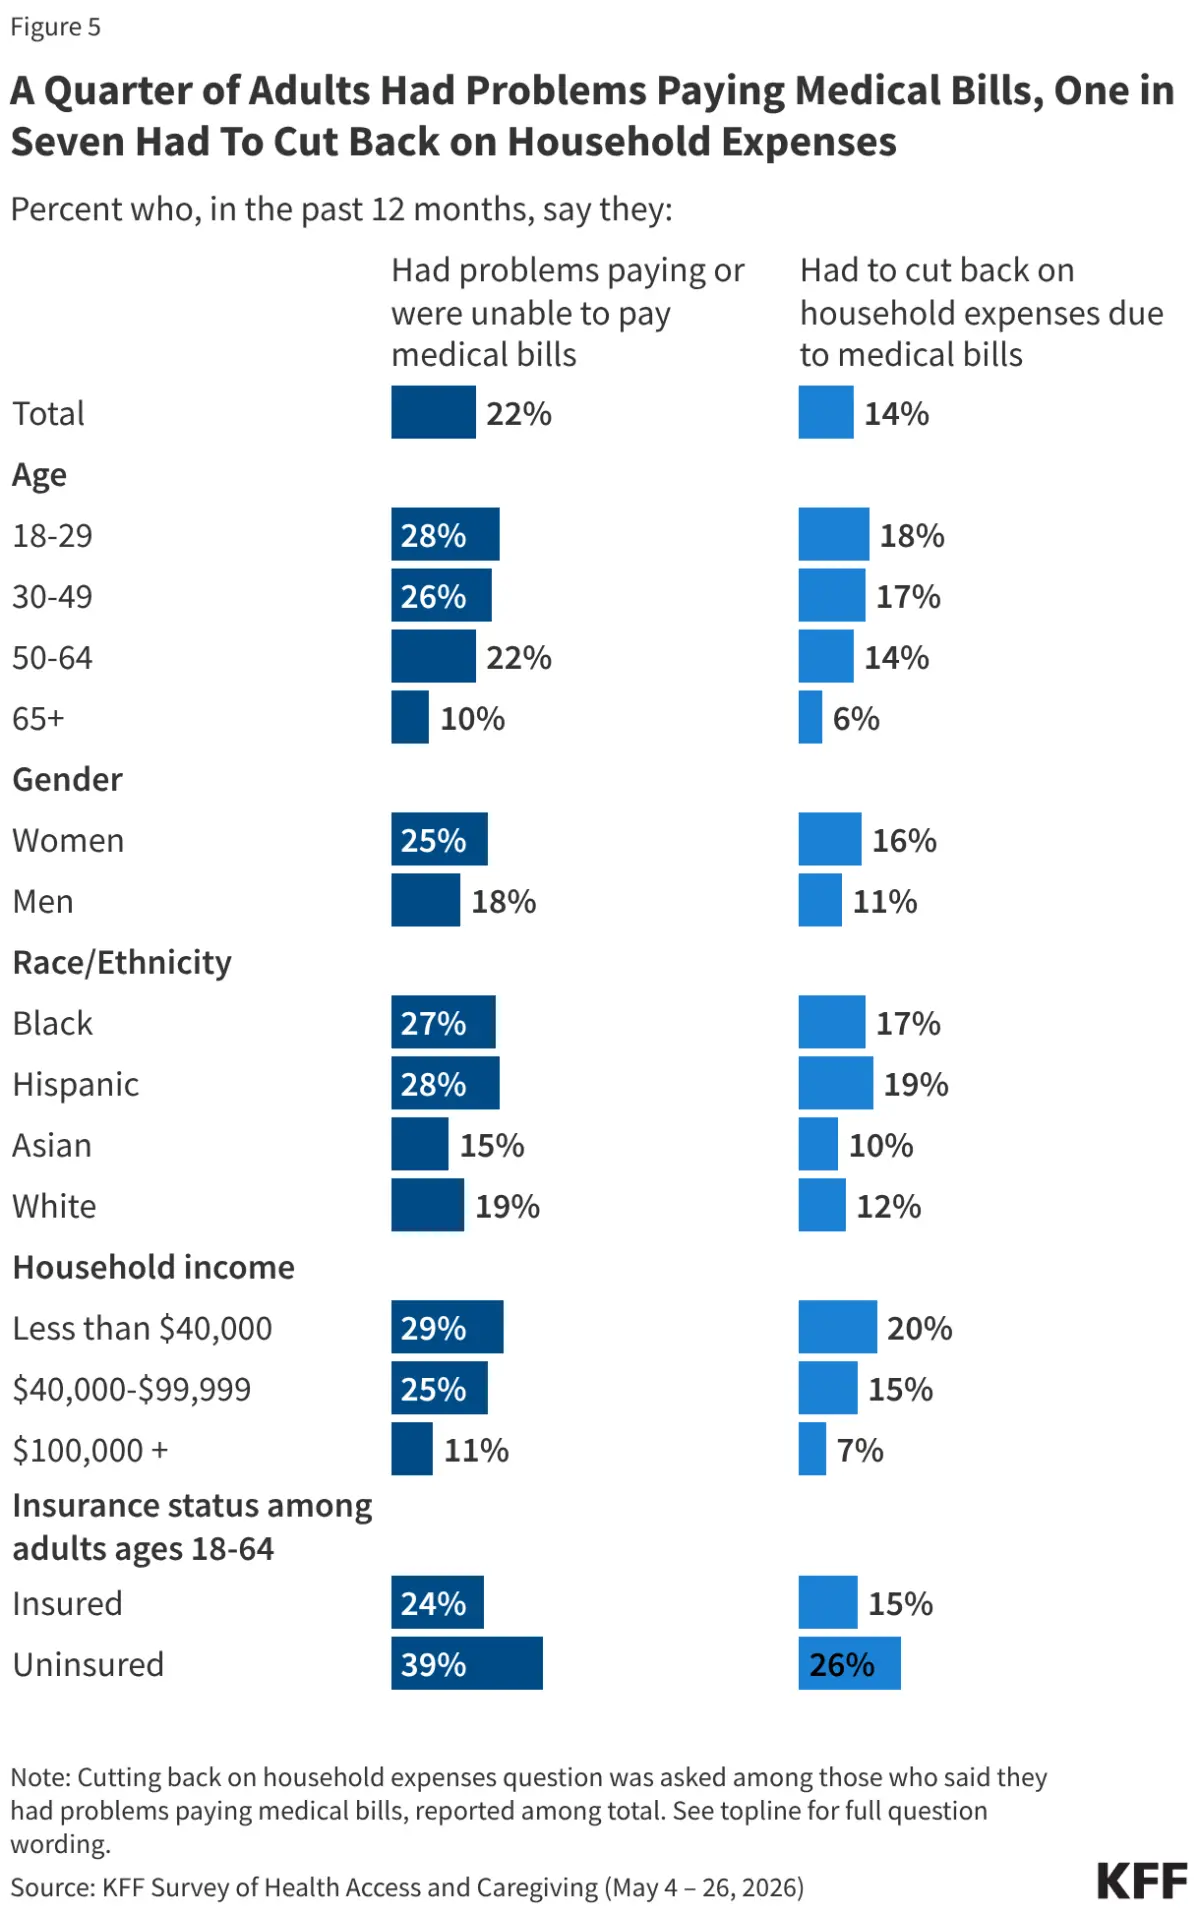
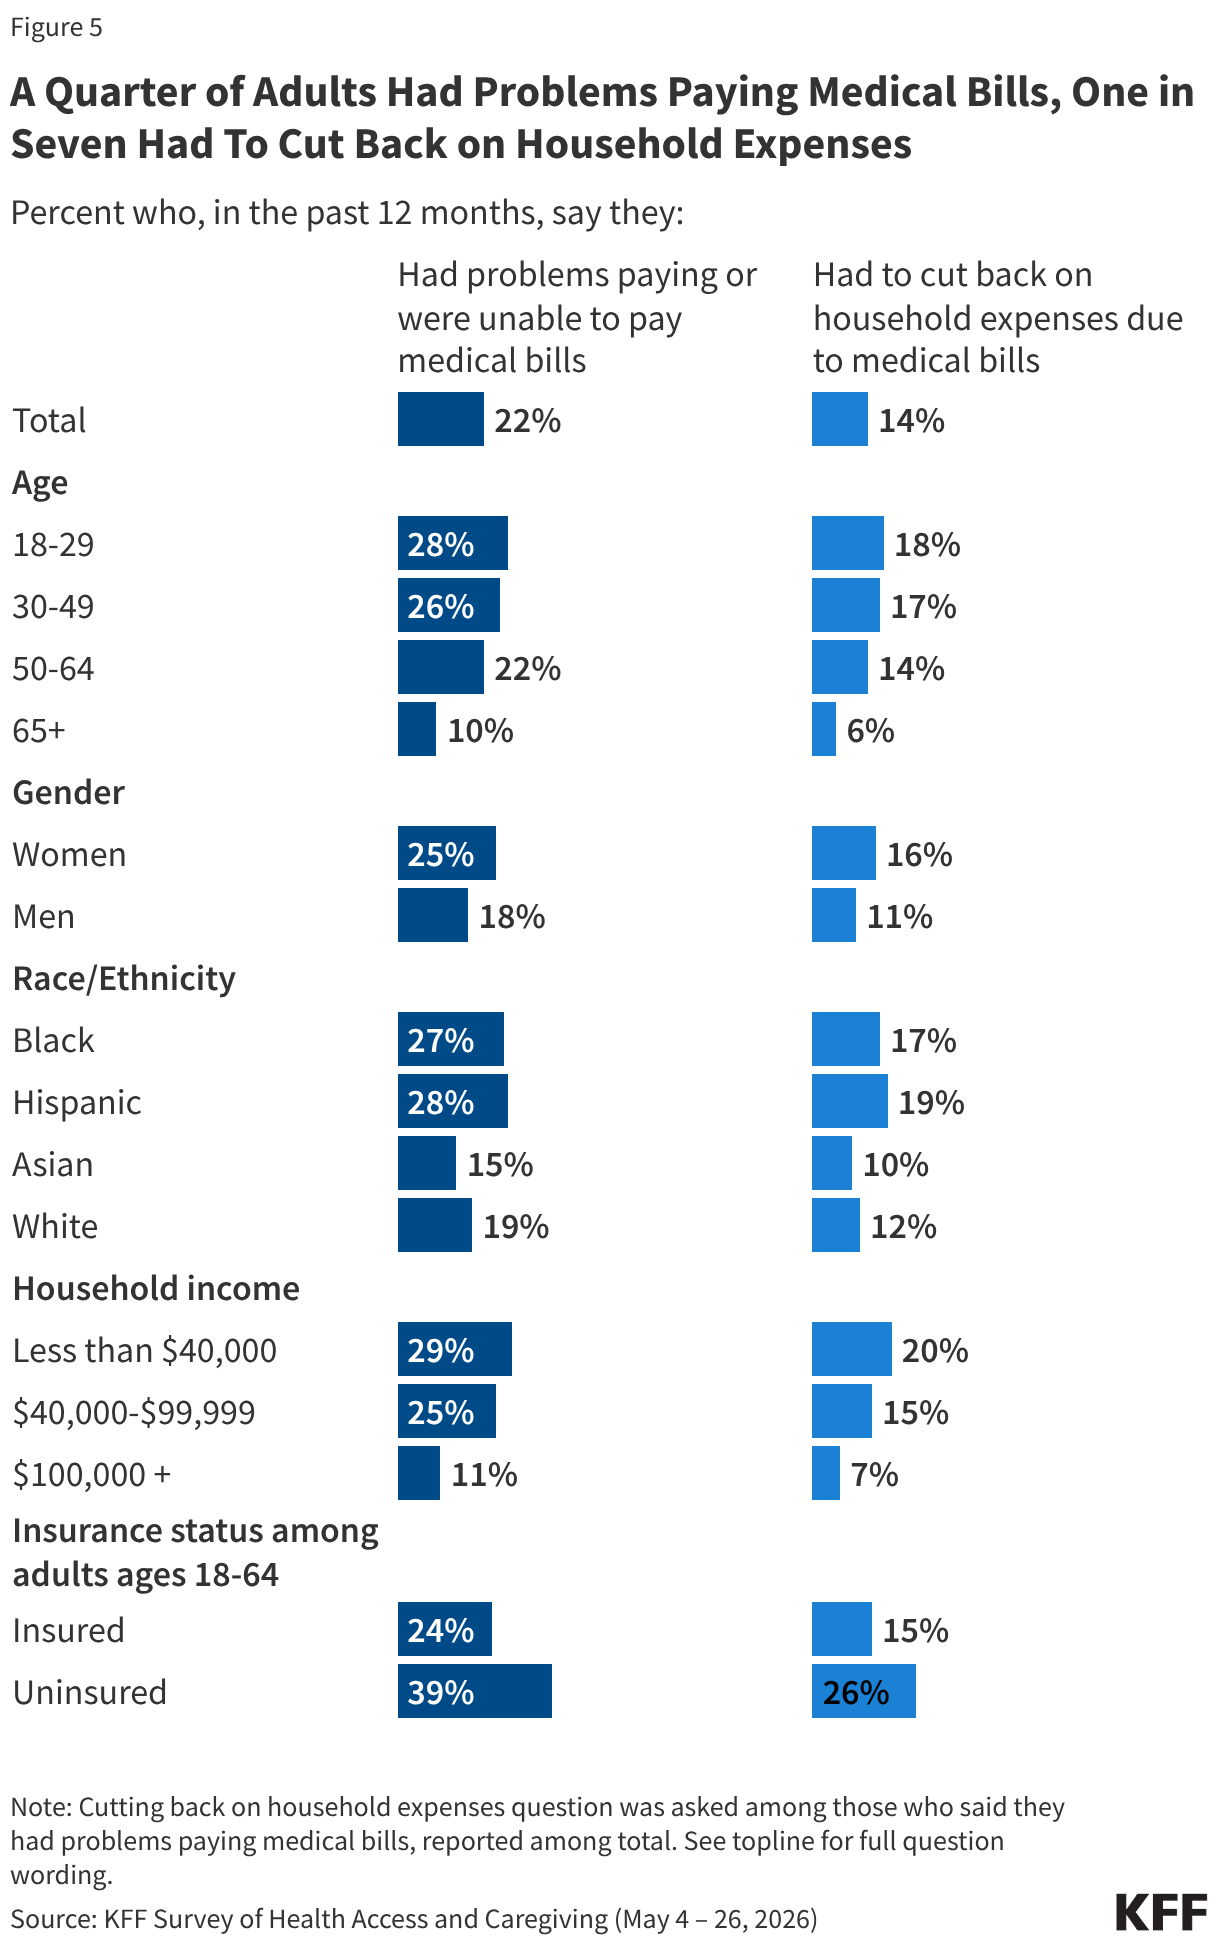
Medical debt is not just a line item on a credit report; it is a lifestyle inhibitor. With one in seven adults forced to cut back on basic necessities—like food, clothing, and utilities—to pay for medical services, the ripple effects are felt across the entire household budget. The fact that half of U.S. adults would be unable to cover an unexpected $500 medical bill without incurring debt indicates that the average American household is essentially one health emergency away from financial ruin.
The Long-Term Care Anxiety
Looking toward the future, the anxiety surrounding long-term care is pervasive. Among those aged 50–64, over 70% express deep concern about the affordability of nursing homes or professional home health aides. As the population ages, the disconnect between the high cost of elder care and the available financial resources suggests a looming crisis that will likely fall on the shoulders of the next generation of caregivers.
Ratings of Insurance Coverage
While most Americans rate their insurance as "good" or "excellent," these ratings hide a significant segment of the population that remains dissatisfied. Those with private employer-sponsored plans or Marketplace coverage are more likely to report negative experiences with premiums and out-of-pocket costs compared to those on Medicaid. This suggests that while insurance is a necessary buffer, it is increasingly failing to provide the level of financial protection that families require to feel secure.
Conclusion: The Path Forward
The data from 2026 paints a picture of a nation struggling to balance the necessity of health care with the reality of stagnant purchasing power and rising medical costs. When a significant portion of the population is forced to choose between groceries and a prescription, or between paying rent and visiting a doctor, the health care system has failed in its primary mission: to promote the well-being of the citizenry.
Addressing this will require more than just technical fixes to insurance plans; it necessitates a fundamental rethink of how medical costs are managed, how drugs are priced, and how the social safety net can be extended to cover the "under-insured." Until these structural issues are addressed, the American public will continue to view health care not as a pillar of security, but as one of their greatest financial liabilities. As the data suggests, this is a systemic problem—and it requires a systemic, durable solution.
About the Author