Editorial Note: This report was updated on October 23, 2026, to incorporate the latest polling data from KFF. It was originally published on December 14, 2021, and has been expanded to reflect the deepening economic strain on U.S. families.
For years, the promise of affordable, accessible healthcare has been a cornerstone of American political discourse. Yet, according to the latest data from KFF, the reality for millions of U.S. families is a persistent, gnawing anxiety over the rising costs of medical care. Healthcare costs are no longer just a line item in a household budget; they are a primary driver of financial instability, influencing decisions on everything from insurance enrollment to whether to seek medical attention at all.
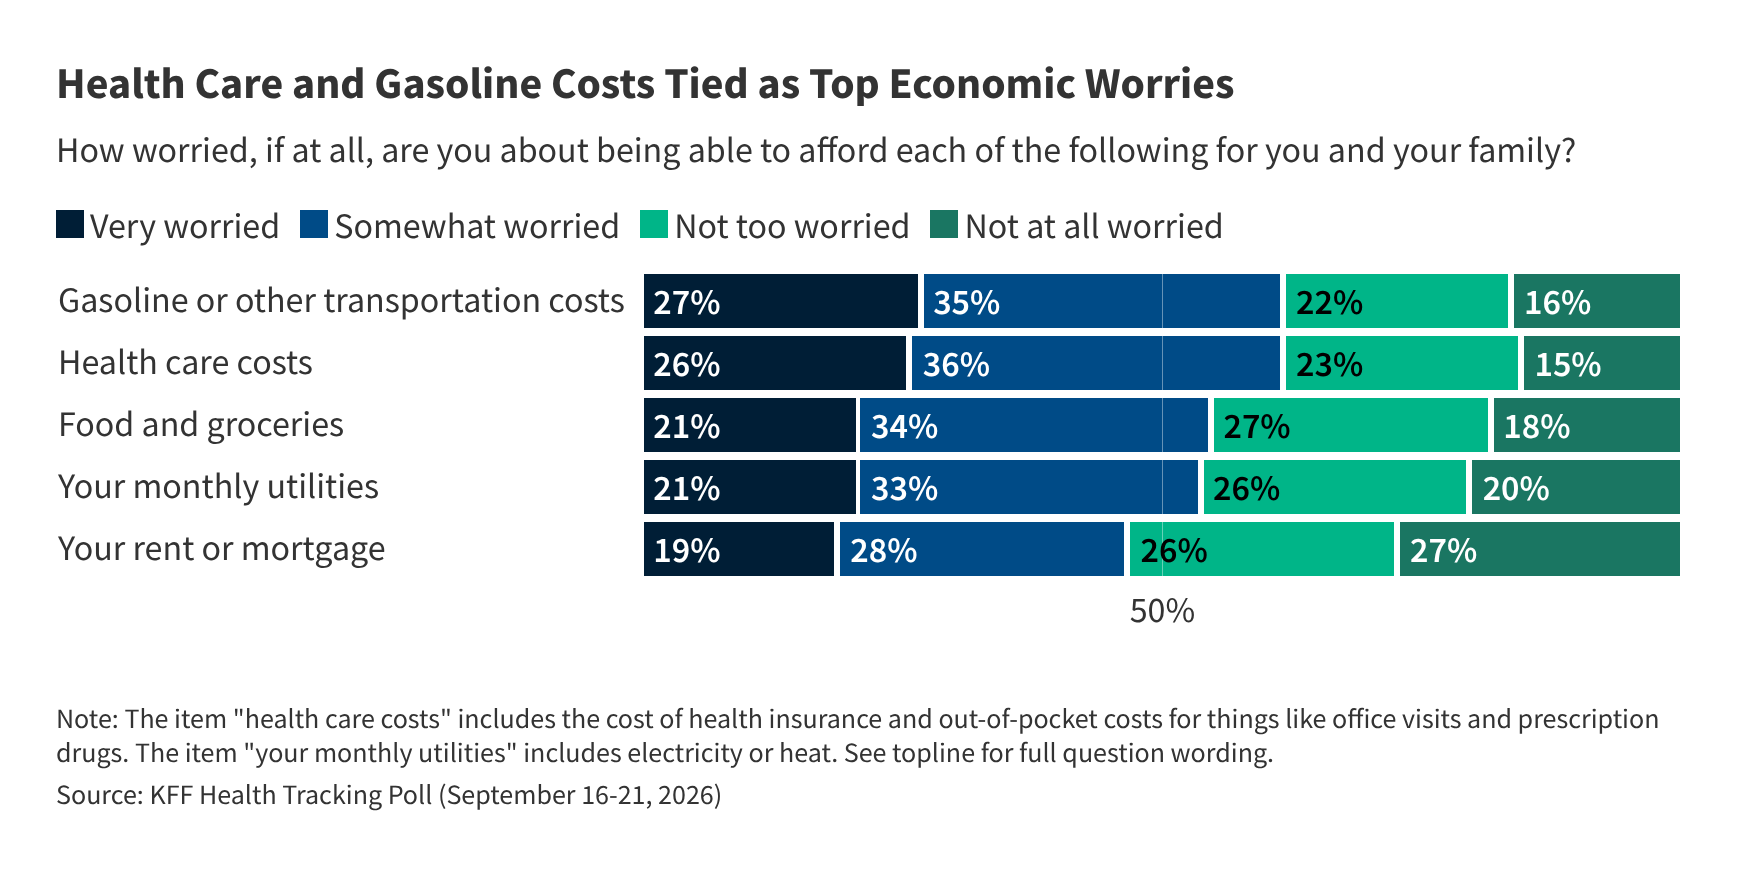
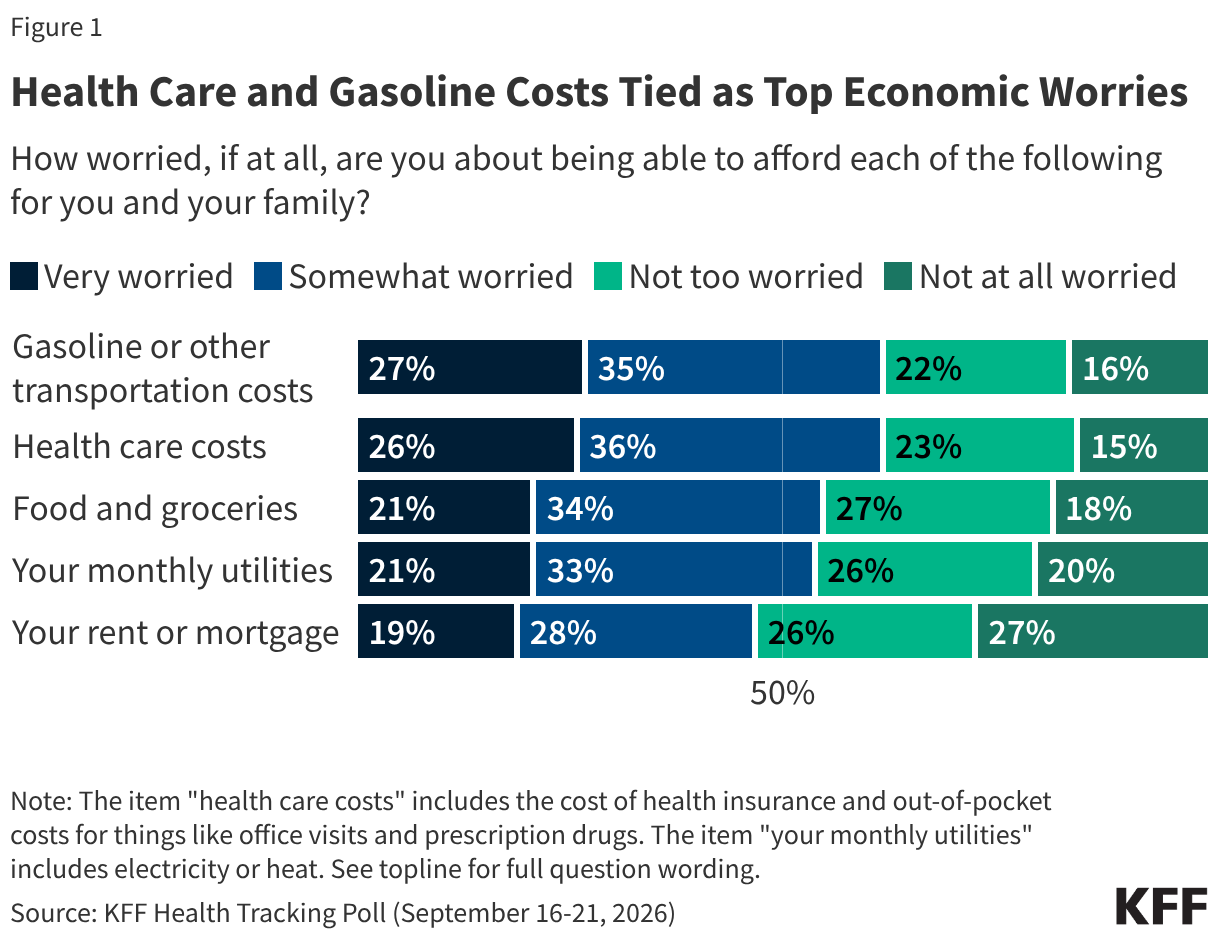
As the nation moves through the latter half of 2026, healthcare expenses have solidified their position as the top financial worry for adults, eclipsing even the costs of housing, food, and transportation. This report examines the systemic nature of this crisis, the demographics most affected, and the long-term implications for the health and financial security of the American public.
The Chronology of an Escalating Financial Burden
The struggle to afford healthcare is not a new phenomenon, but it has intensified in the current economic climate.
- 2021: KFF began documenting a surge in concern as the pandemic-era financial landscape shifted, revealing that medical debt and insurance premiums were already pushing families to their breaking points.
- 2022: The Diagnosis Debt project, a collaborative investigation by KFF Health News and NPR, exposed that 41% of U.S. adults carried some form of medical or dental debt.
- 2023–2025: Throughout these years, polling showed a steady increase in the number of Americans resorting to "cost-saving" measures, such as cutting pills in half or skipping prescription doses, signaling a normalization of medical rationing among middle-class families.
- 2026: In the lead-up to the midterm elections, KFF tracking polls confirm that 62% of adults are now "very" or "somewhat" worried about their ability to afford healthcare. This anxiety has become a defining characteristic of the modern American experience, transcending party lines and insurance status.
Supporting Data: Who Is Most at Risk?
The burden of healthcare costs is not distributed equally. While the high cost of medical care is a universal concern, the data highlights specific vulnerabilities based on income, race, insurance status, and health history.
The Myth of Insurance Protection
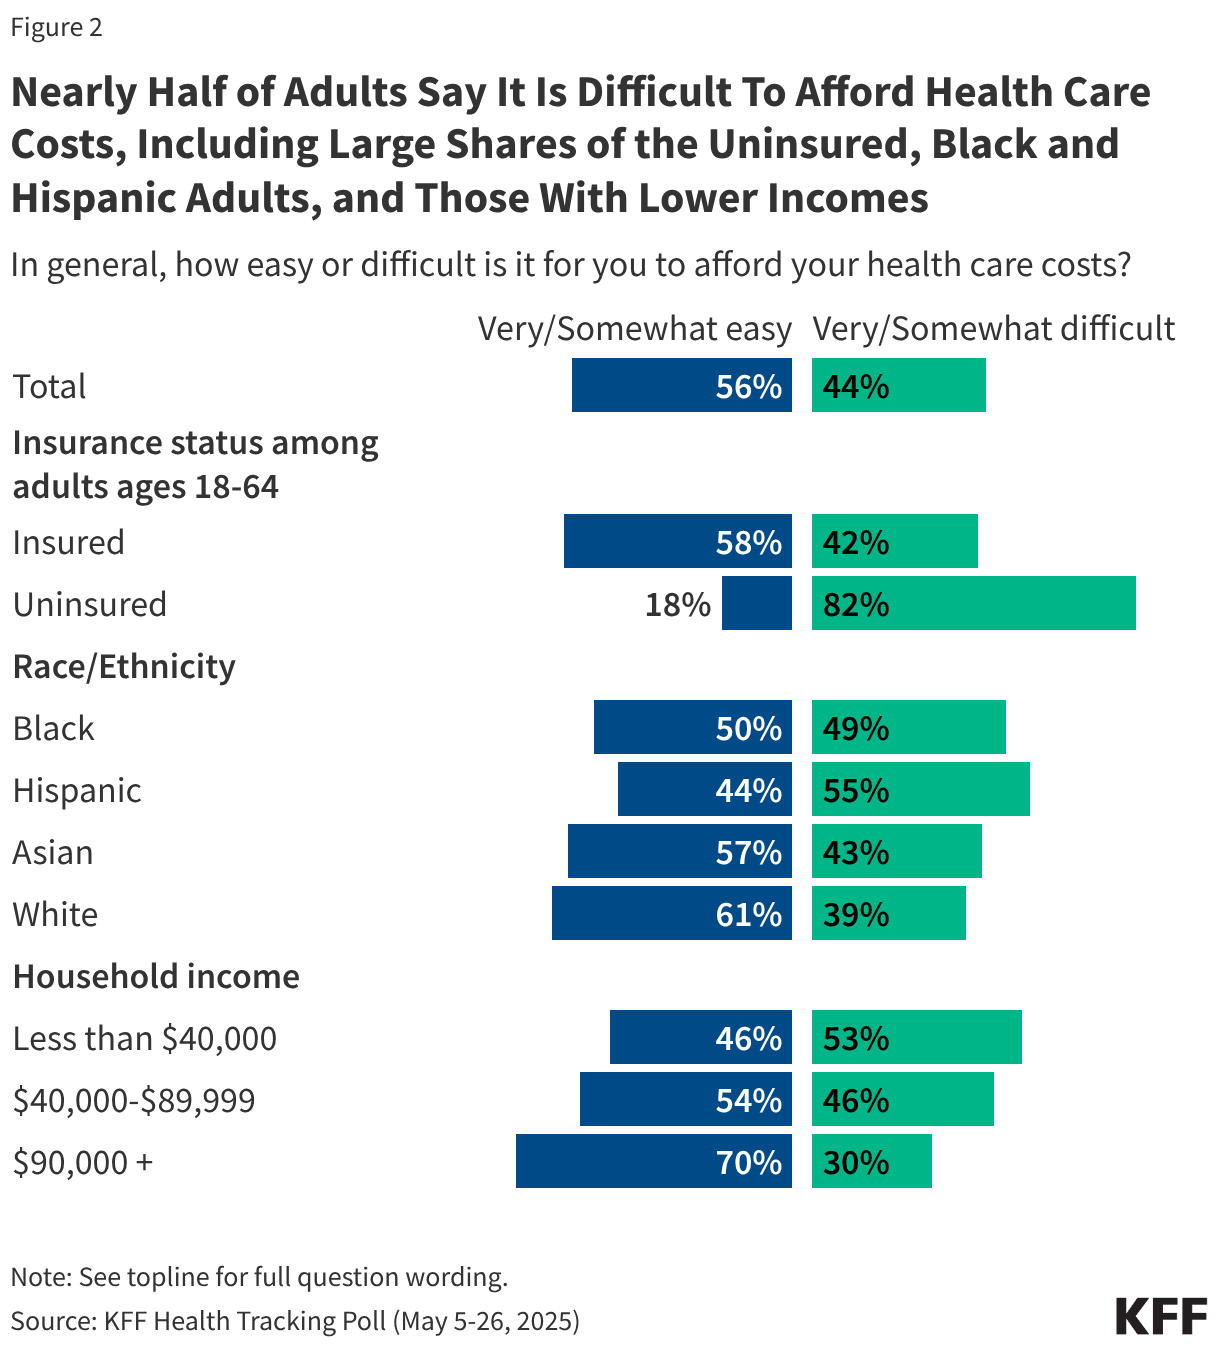
A common misconception is that having health insurance acts as a full shield against financial catastrophe. However, 42% of insured adults under the age of 65 report that it is difficult to afford their healthcare costs. Even for those with coverage, high deductibles, co-pays, and out-of-pocket maximums mean that seeking care remains a calculated financial risk rather than a guaranteed right.
Racial and Economic Disparities
The data reveals stark inequities:
- Demographic Divide: A slight majority of Hispanic adults (55%) and half of Black adults (49%) report difficulty affording care, compared to 39% of White adults.
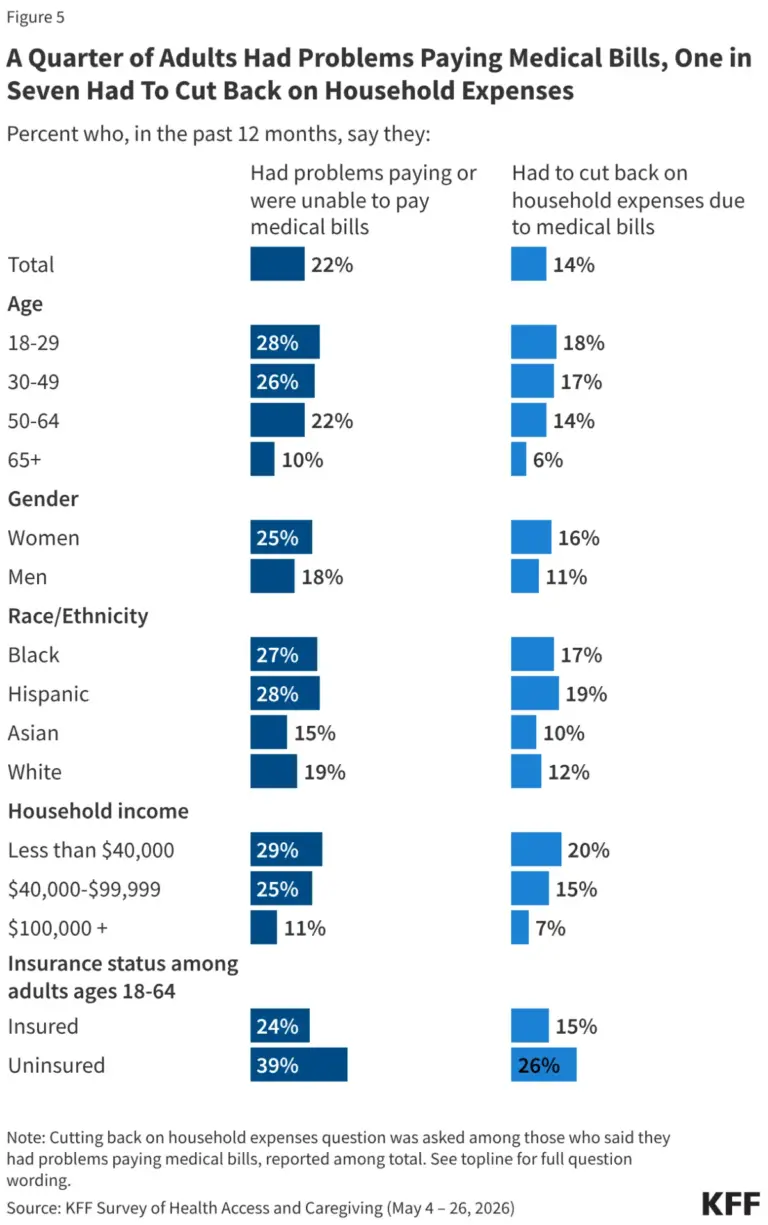
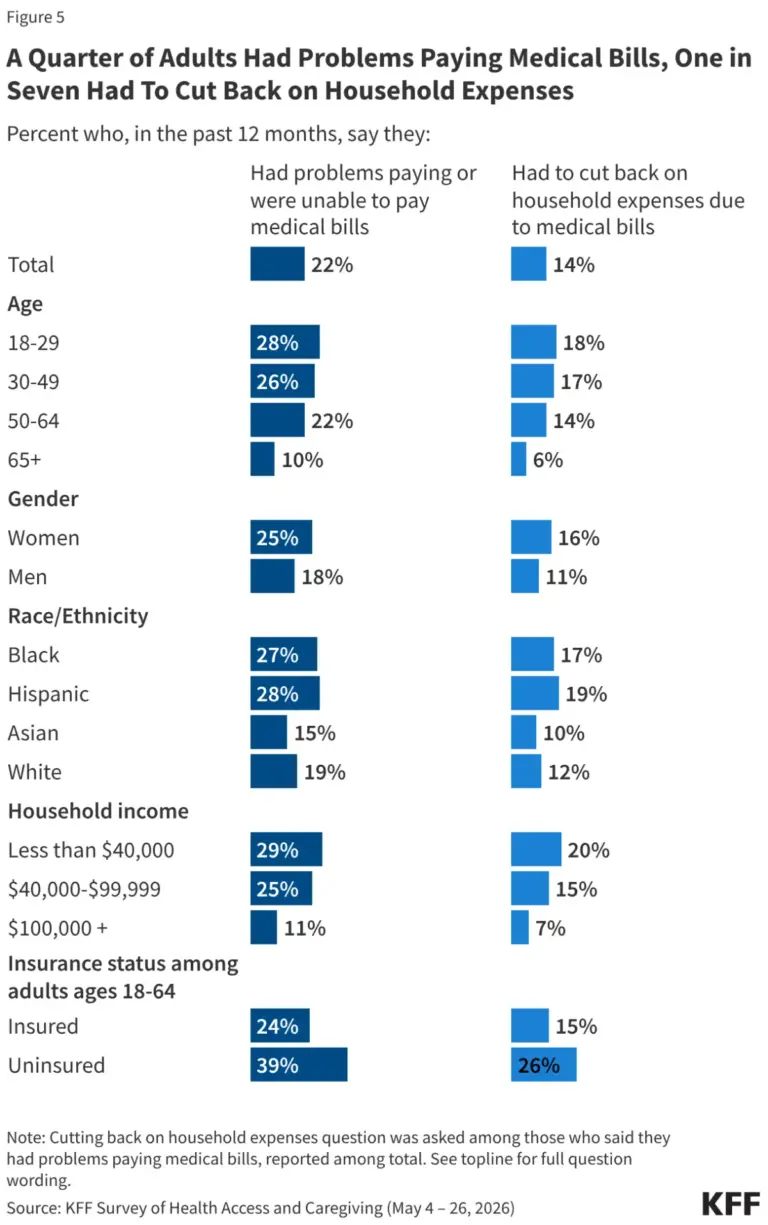
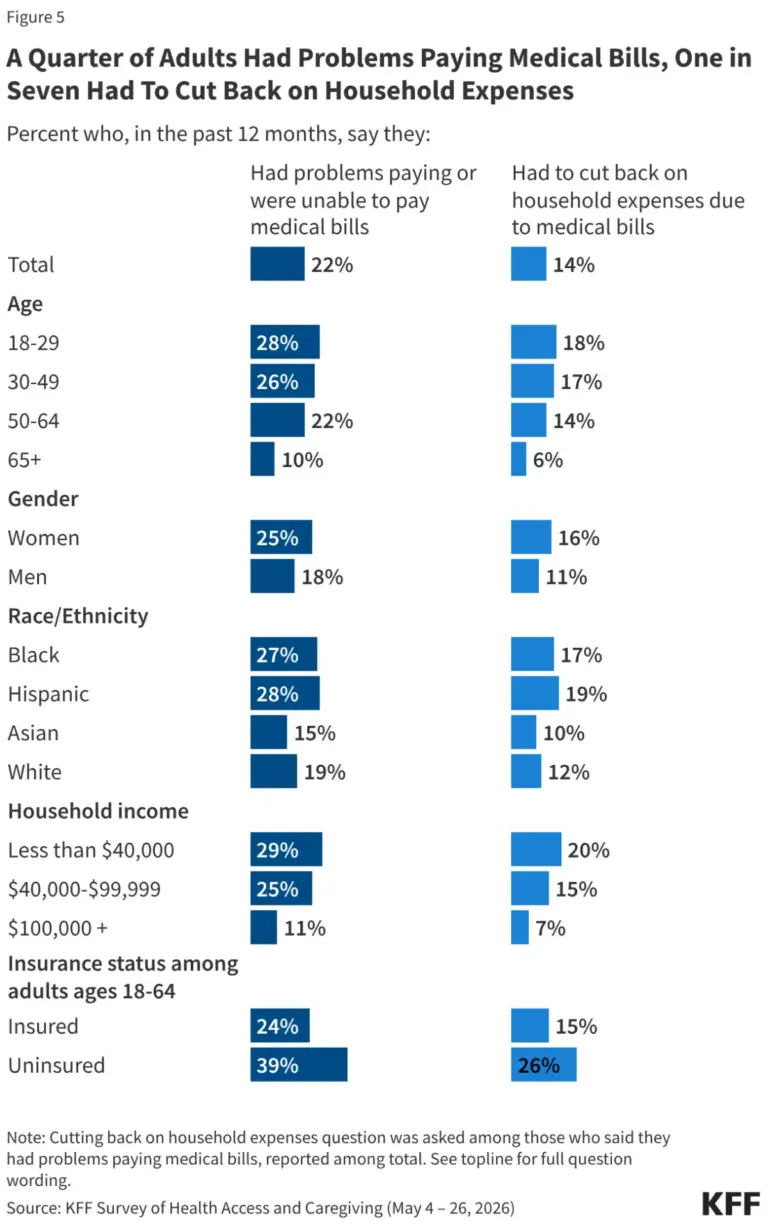
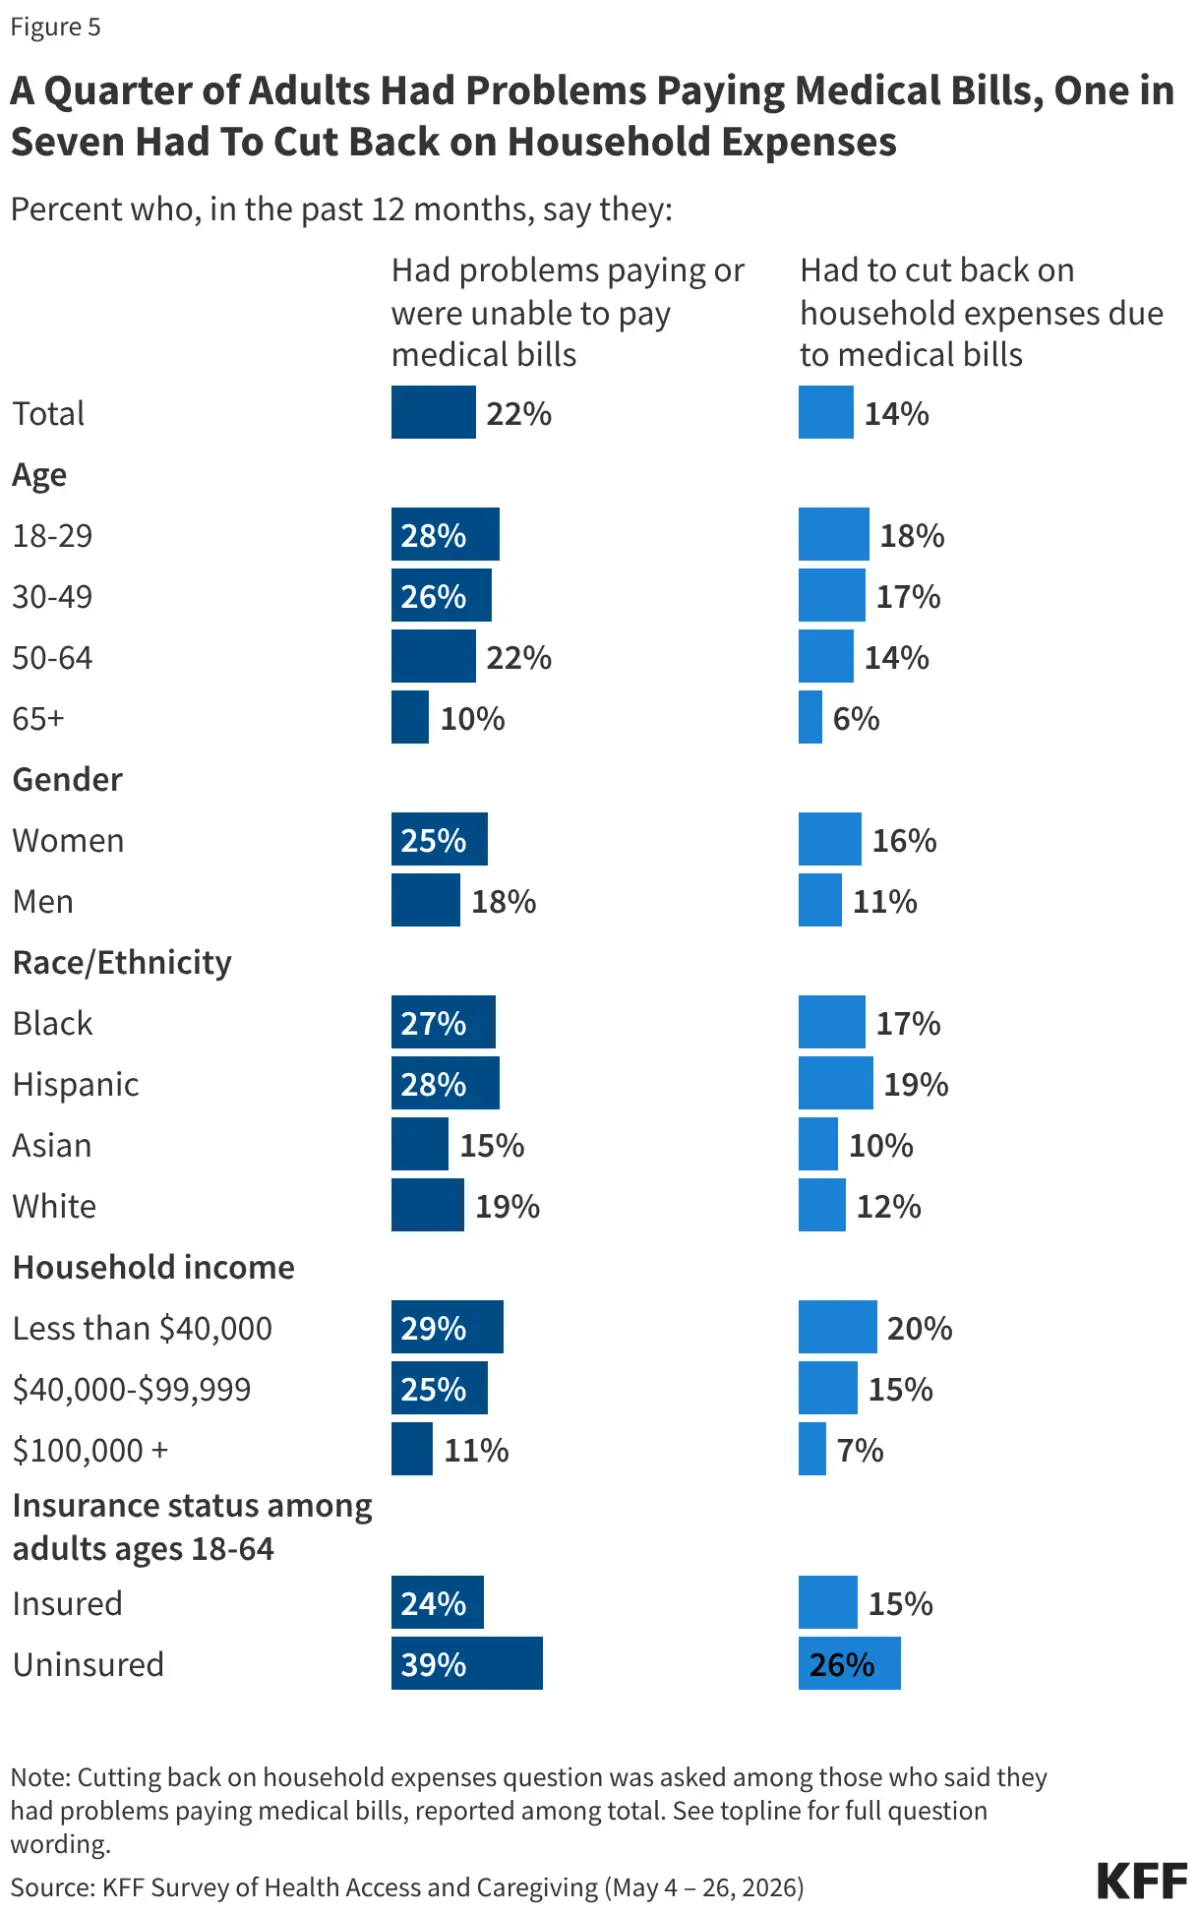
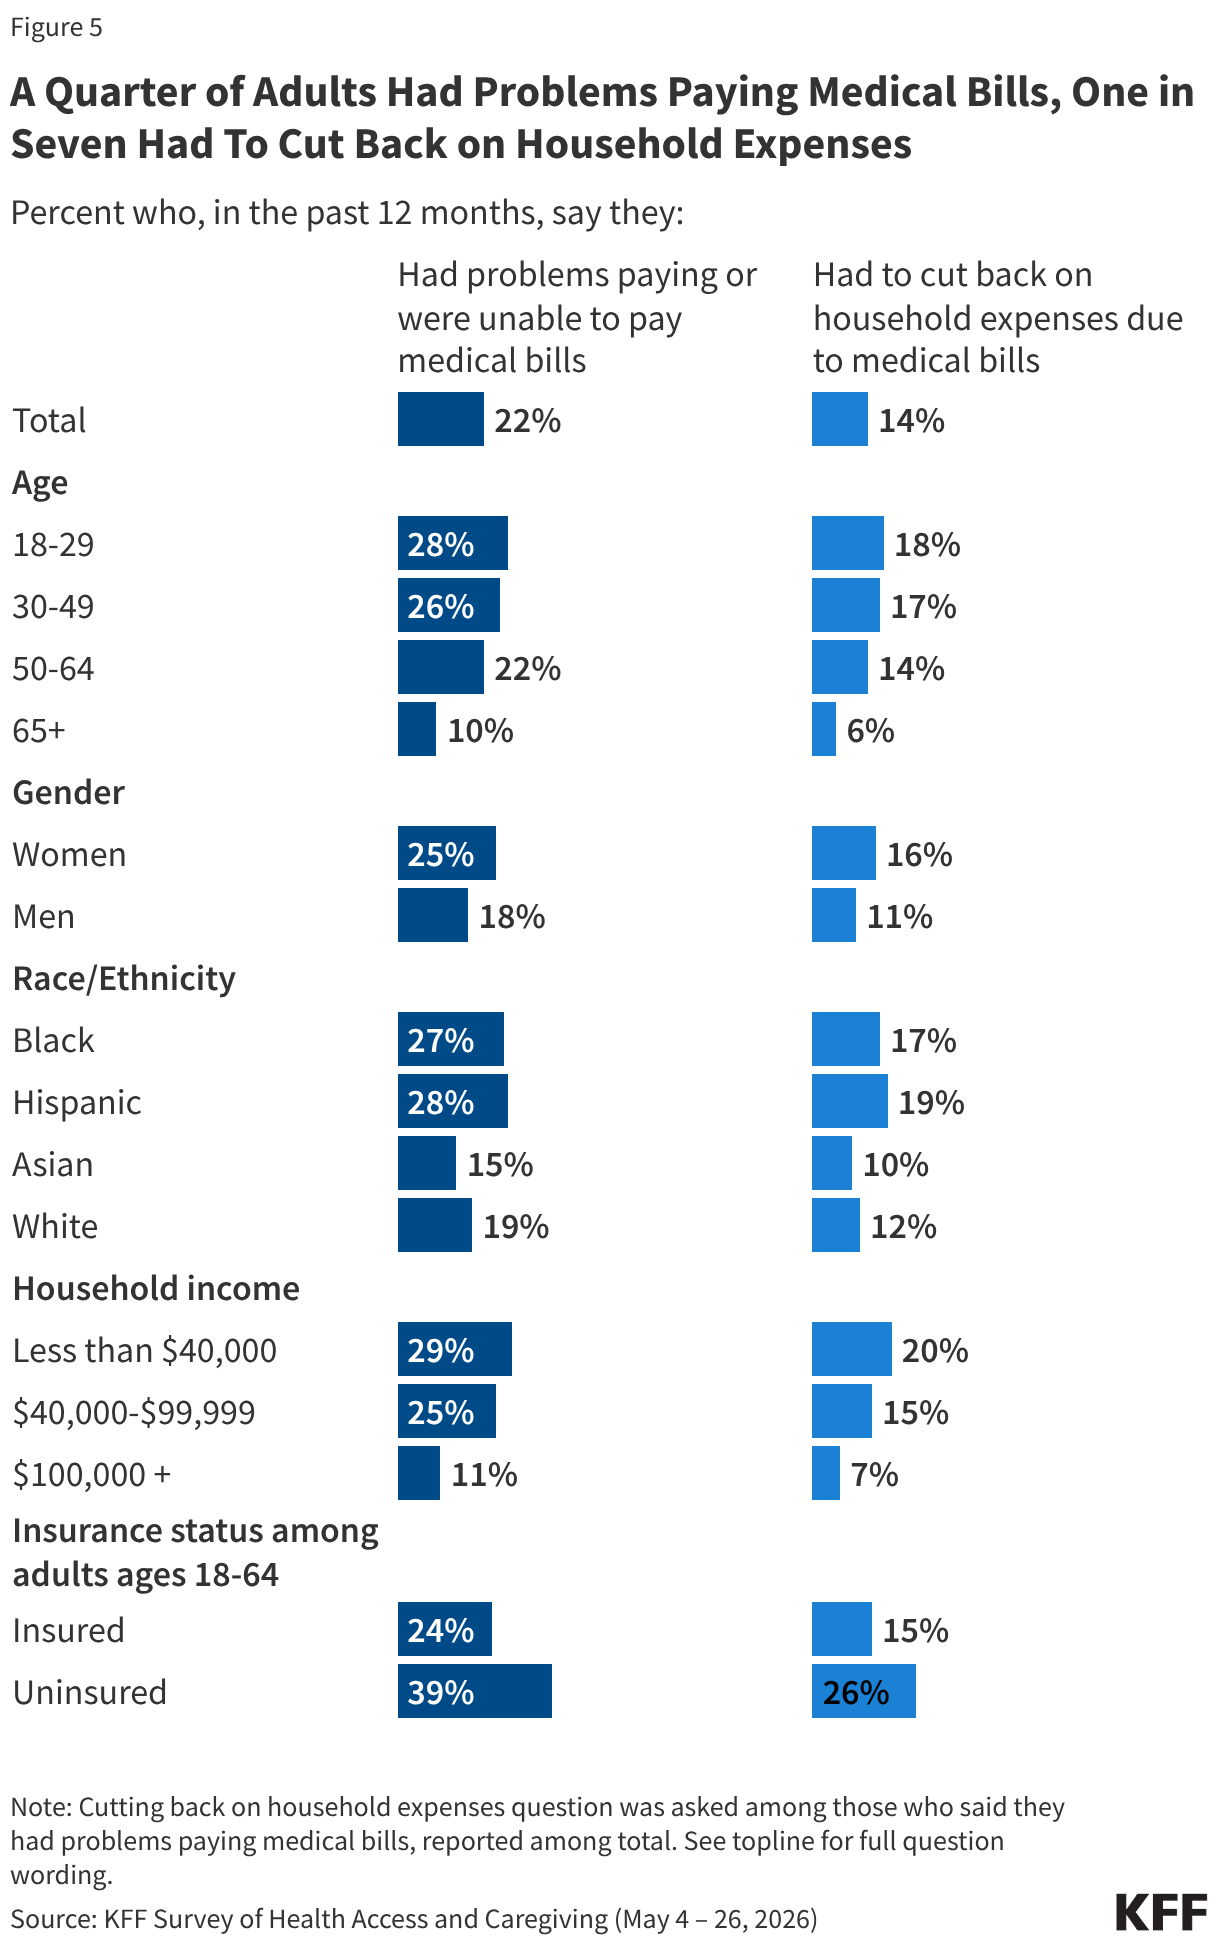
- Income Constraints: Households with annual incomes under $40,000 face the most acute challenges. For these families, a single medical event can necessitate the sacrifice of other basic needs. In fact, 14% of all U.S. adults admit they have had to cut back on groceries, clothing, or utilities to pay for medical services.
- The Uninsured Reality: For the uninsured, the situation is dire. Roughly 82% of uninsured adults under 65 are worried about costs, and 62% report skipping or delaying necessary medical care in the past year.
The Hidden Cost of Delaying Care
Perhaps the most alarming trend identified in the KFF data is the prevalence of "medical rationing." When individuals delay or skip care due to cost, the long-term health consequences are often severe.
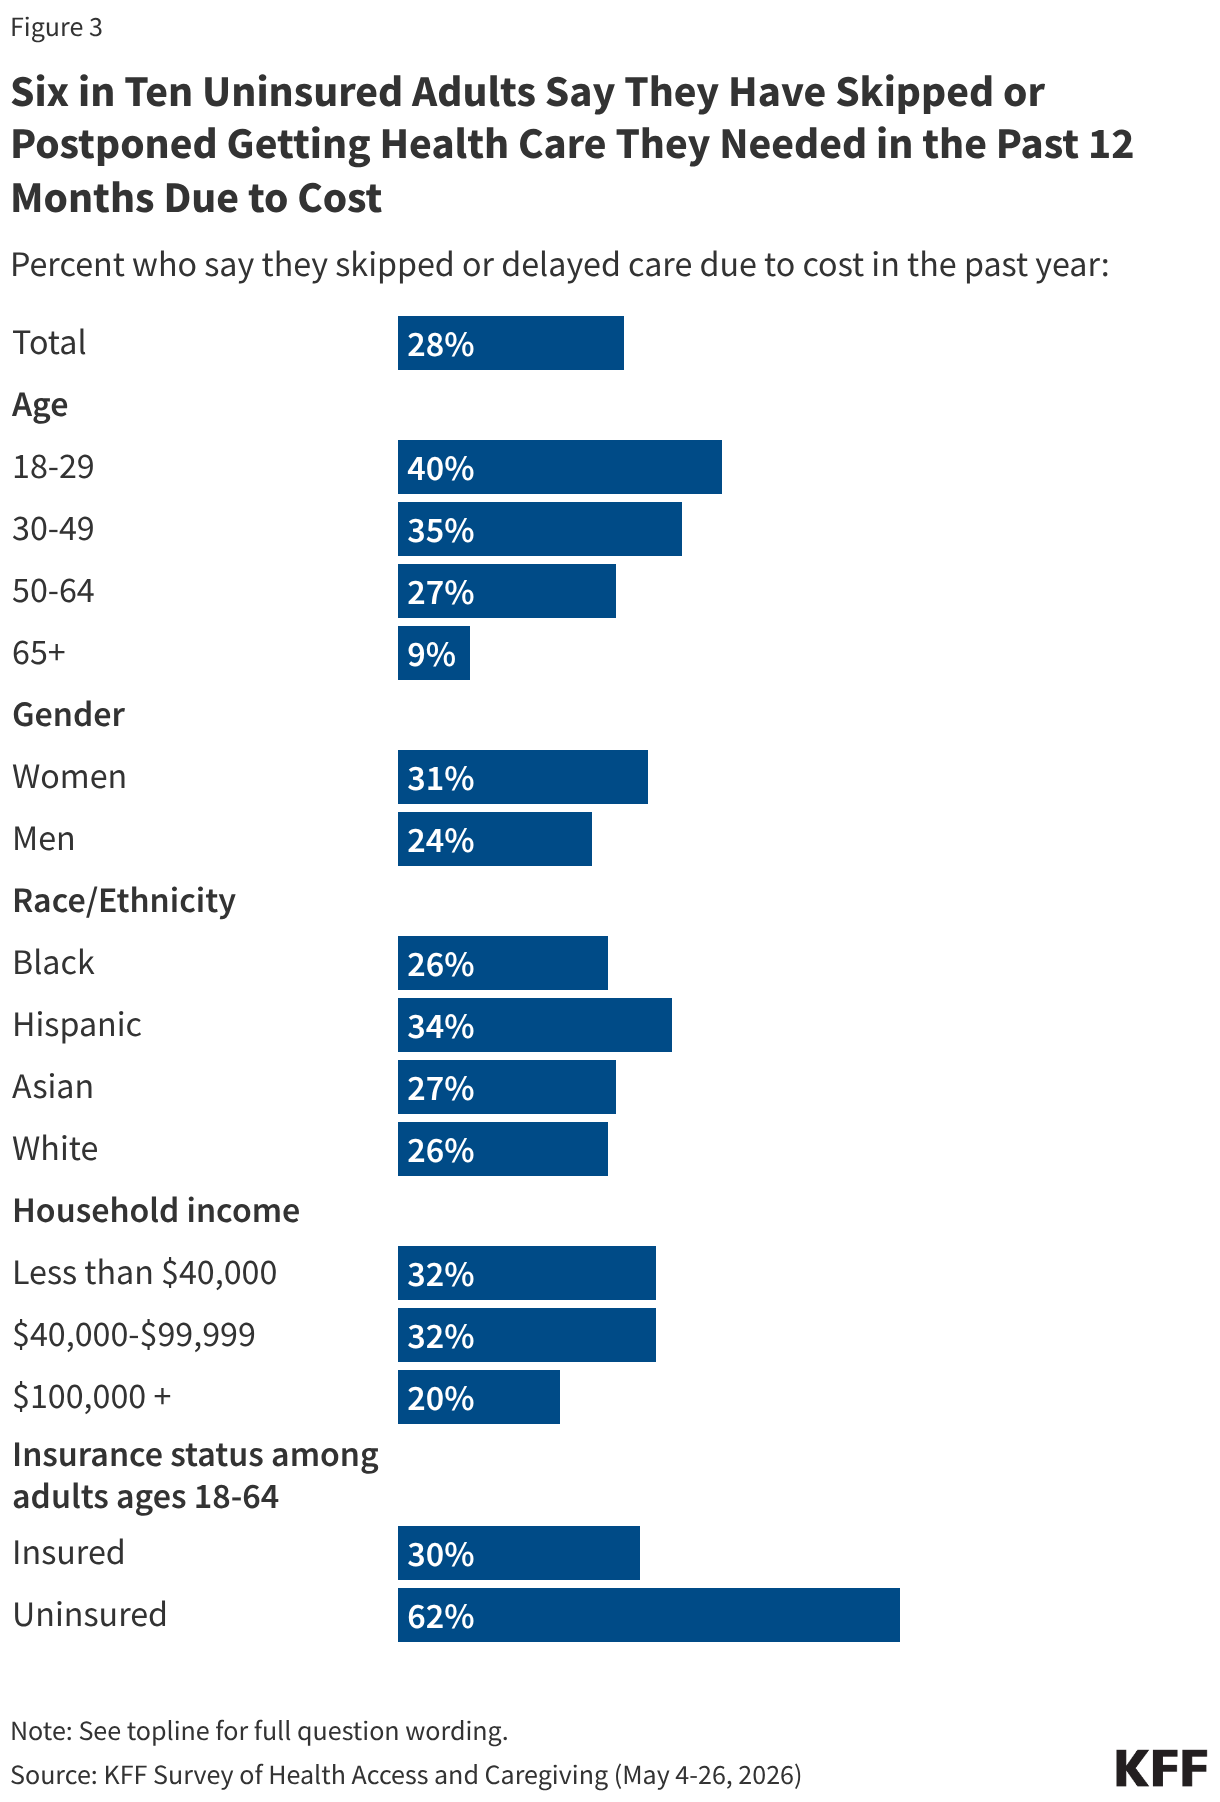
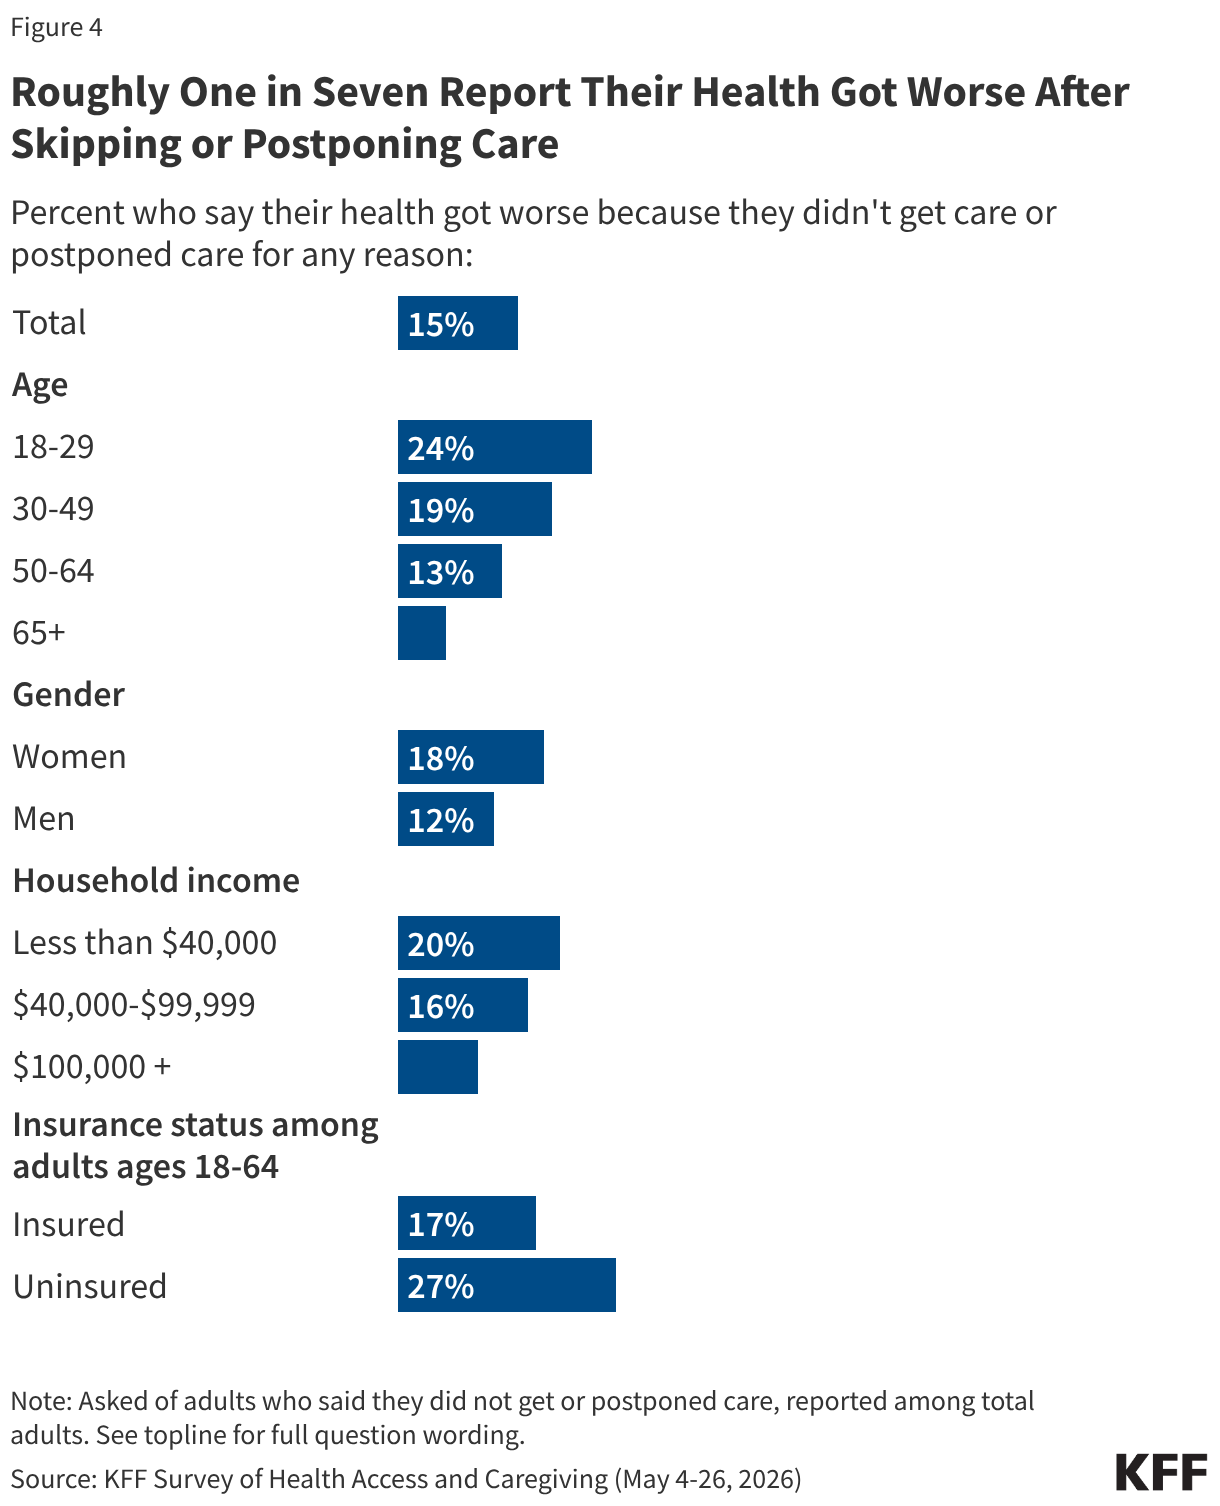
Roughly 28% of adults have skipped or postponed needed healthcare in the last 12 months. The impact of these delays is measurable: 15% of adults report that their health has actively worsened because they did not receive timely care. This effect is particularly pronounced among younger populations and those with chronic conditions. For adults under 30, the rate of health deterioration following skipped care is four times higher than that of adults over 65, the latter of whom are largely protected by the stability of Medicare.
Chronic Conditions and Vulnerable Populations
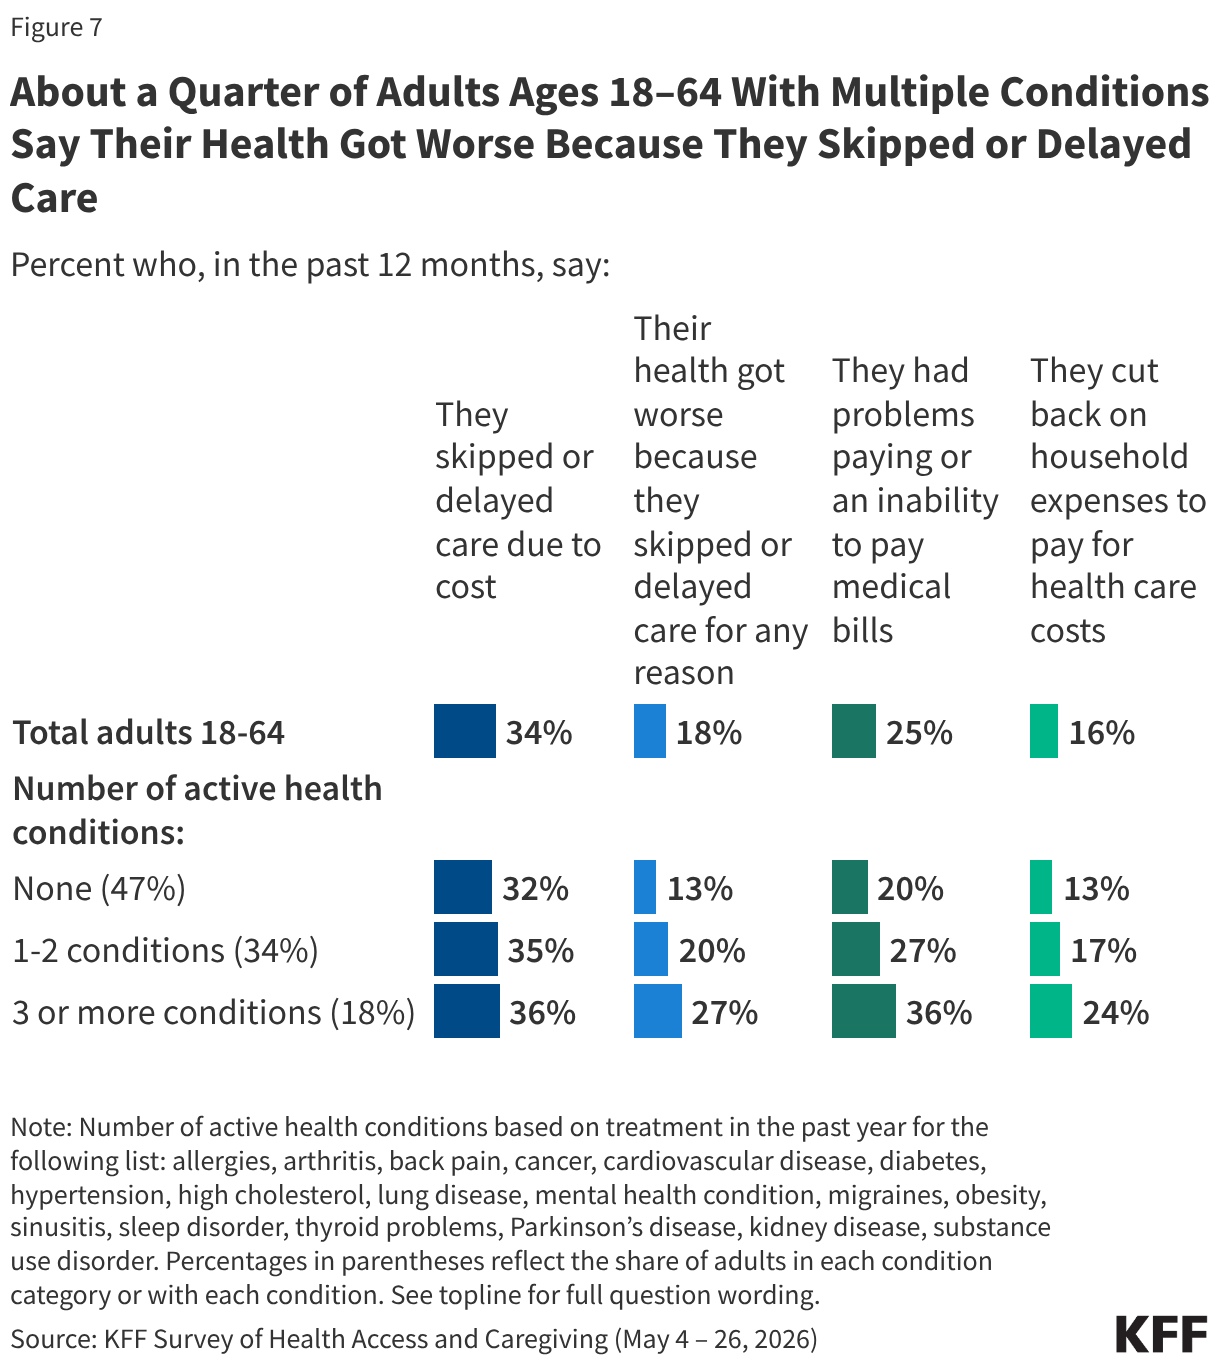
Individuals with complex or multiple health conditions are effectively trapped by their own medical needs. Among adults ages 18-64 with three or more health conditions, 36% skipped care due to cost, and 27% saw their health decline as a result.
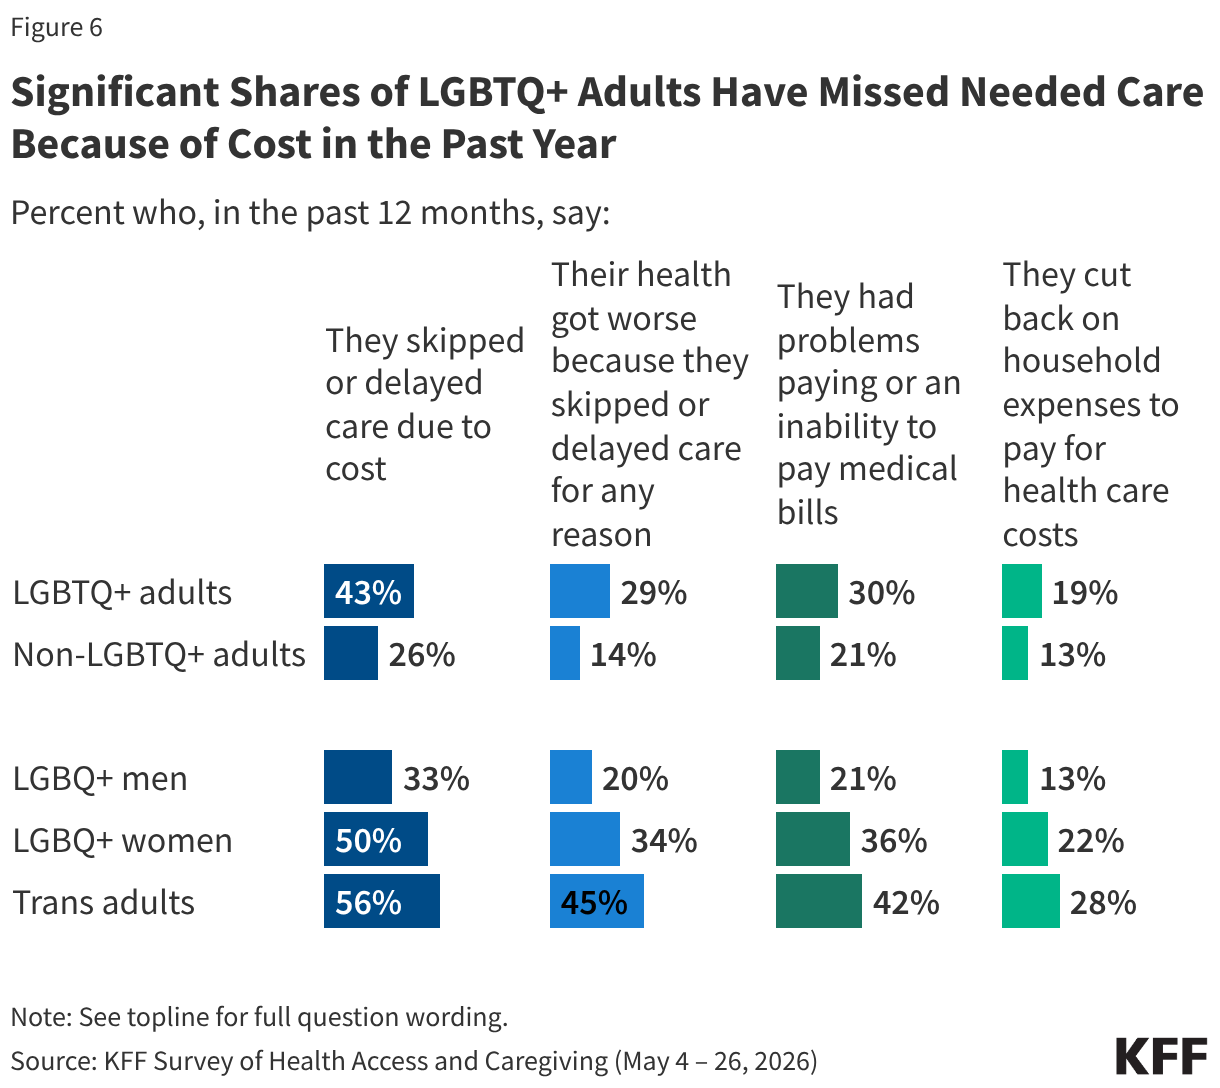
Furthermore, the LGBTQ+ community faces unique hurdles. Over 43% of LGBTQ+ adults report delaying care due to cost, with transgender adults reporting even higher rates (56%). These figures underscore that affordability is not merely a financial issue—it is a matter of civil rights and health equity.
Prescription Drug Costs: A Growing Crisis
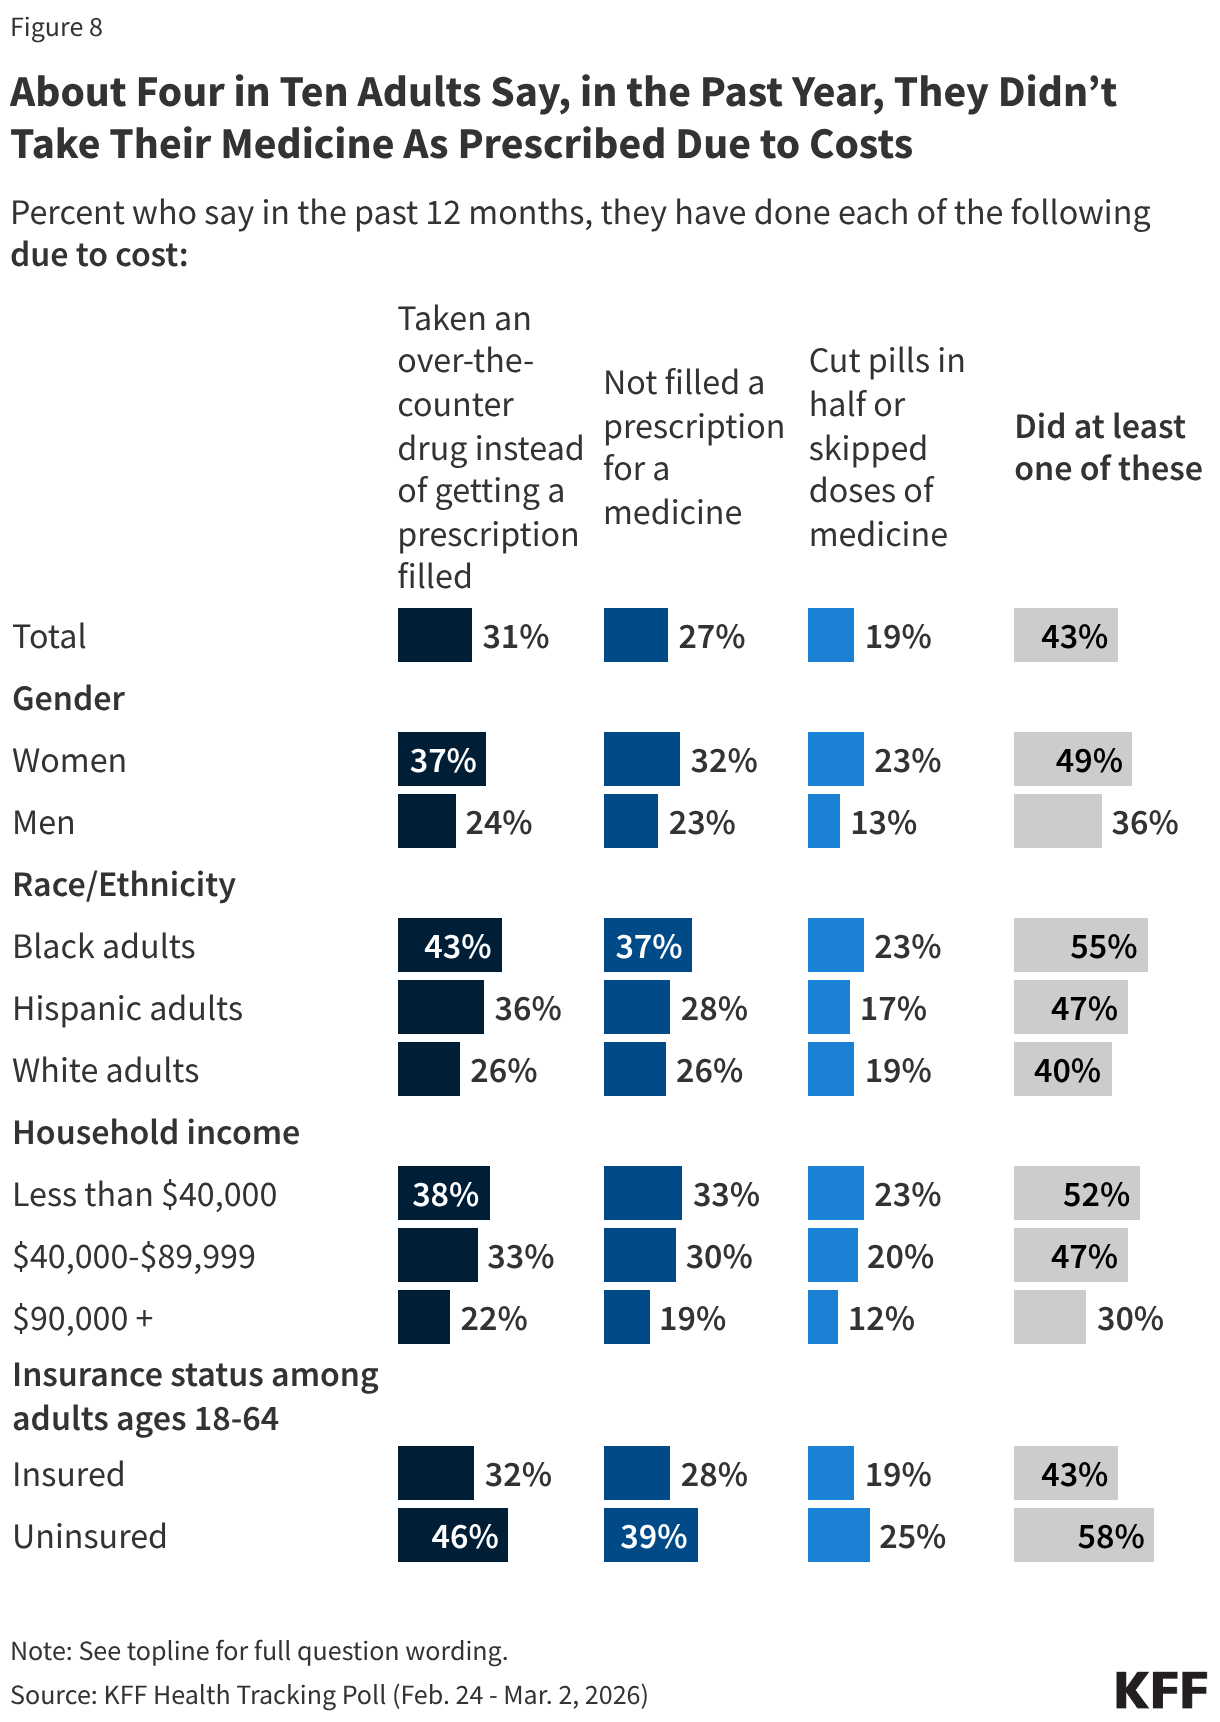
The high cost of prescription medication has led to a dangerous shift in patient behavior. As of 2026, 43% of adults report taking at least one measure to reduce their drug costs, such as:
- Substituting over-the-counter drugs for prescription medication.
- Refusing to fill a prescription.
- Cutting pills in half or skipping doses.
This behavior is trending upward, climbing from 31% in 2023 to 43% in 2026. These actions are most prevalent in low-to-middle-income households, where the choice often becomes a trade-off between medication and other survival necessities.
Official Responses and Insurance Perspectives
The insurance industry maintains that premiums and out-of-pocket costs are a reflection of the broader cost of medical technology, administrative complexity, and provider reimbursement rates. Most insured Americans still rate their plans as "good" or "excellent" for specific services. However, a significant minority—at least 30%—rate their coverage as "fair" or "poor" across all metrics, including premiums and co-pays.
Those with employer-sponsored or Marketplace plans are generally more critical of their insurance affordability than those on Medicare or Medicaid. While Medicaid provides a safety net with nominal costs, the private insurance market continues to be a source of frustration for middle-class Americans who find themselves in a "coverage gap" where they are too wealthy for subsidies but too financially constrained to handle high out-of-pocket expenses.
The Long-Term Implications: Debt and Anxiety
The financial ripples of a medical emergency extend far beyond the doctor’s office. Medical debt has become a permanent feature of the American economy.
The $500 Threshold
KFF research indicates that nearly half of U.S. adults would struggle to pay an unexpected $500 medical bill. For many, this leads to:
- Credit Card Debt: The use of high-interest credit to cover medical bills.
- Borrowing from Friends/Family: Straining personal relationships to pay for care.
- Long-Term Financial Instability: Becoming beholden to collection agencies or banks for years to come.
The Aging Population and Long-Term Care
As the American population ages, the anxiety surrounding long-term care—nursing homes, assisted living, and home health aides—is reaching a fever pitch. More than 70% of adults aged 50 to 64 are "anxious" about their ability to afford residential care in the future. This suggests that the current crisis is not just a present-day struggle but a looming demographic emergency that current social safety nets are ill-equipped to address.
Conclusion: A System at a Crossroads
The data presented by KFF serves as a stark reminder that for millions of Americans, healthcare is not a seamless service but a source of persistent, multifaceted trauma. Whether it is the patient skipping a dose of insulin, the parent delaying a child’s visit to a specialist, or the older adult fearing the cost of a nursing home, the message is clear: the current trajectory of healthcare costs is unsustainable.
Addressing this crisis requires more than incremental policy shifts. It demands a holistic re-evaluation of how medical costs are structured, how pharmaceutical pricing is regulated, and how society views the intersection of health and financial security. As the electorate continues to demand relief, the gap between the cost of living and the cost of staying alive remains the most significant challenge facing the American healthcare system in the coming decade.
About the Author