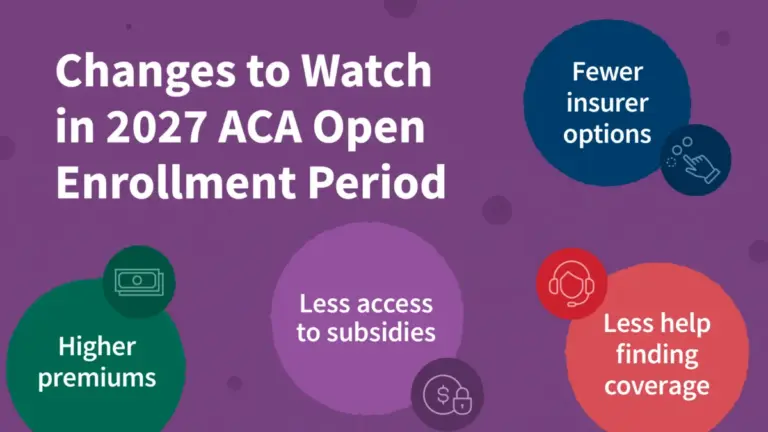
The Affordable Care Act (ACA) Marketplace enters its 2027 Open Enrollment period, which begins November 1, 2026, facing a convergence of economic pressures and transformative legislative changes. Following the expiration of enhanced premium tax credits in 2026 and the implementation of significant provisions from the 2025 federal budget reconciliation law—informally dubbed the "One Big Beautiful Bill Act"—the landscape for individual health insurance has undergone its most radical restructuring since the law’s inception. As premiums climb by double digits for the second consecutive year and federal eligibility rules tighten, millions of Americans are navigating a significantly more complex and expensive coverage environment.
The State of Play: Key Economic and Policy Drivers
The 2027 enrollment cycle is defined by a "perfect storm" of rising medical inflation, reduced federal subsidies, and aggressive regulatory oversight. Insurers have cited a higher-than-usual increase in the underlying cost of care as the primary driver for premium hikes. This phenomenon is not isolated to the ACA; employer-sponsored plans are reporting similar cost escalations. However, the impact on the individual market is magnified by the loss of pandemic-era enhanced subsidies, which had previously cushioned the blow of rising healthcare costs.
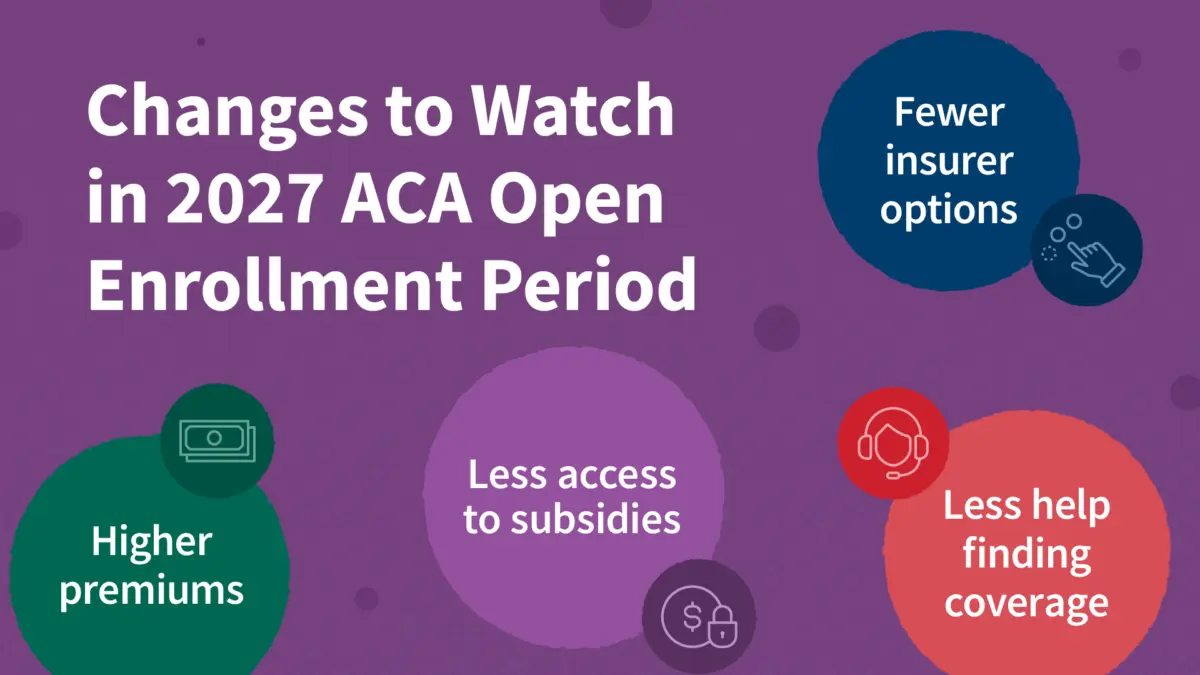
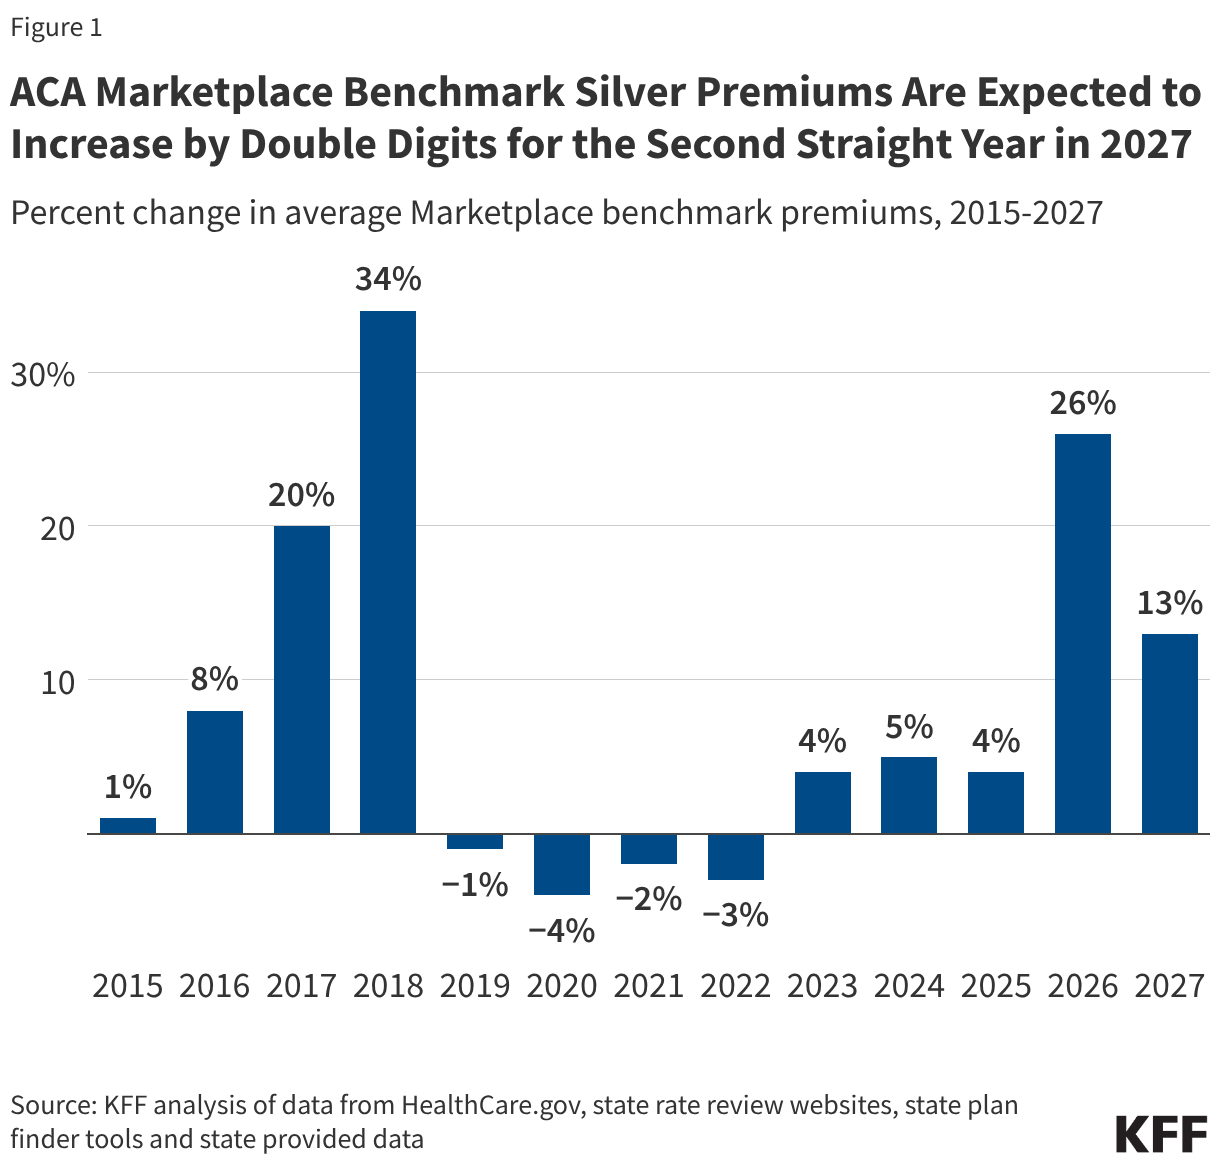
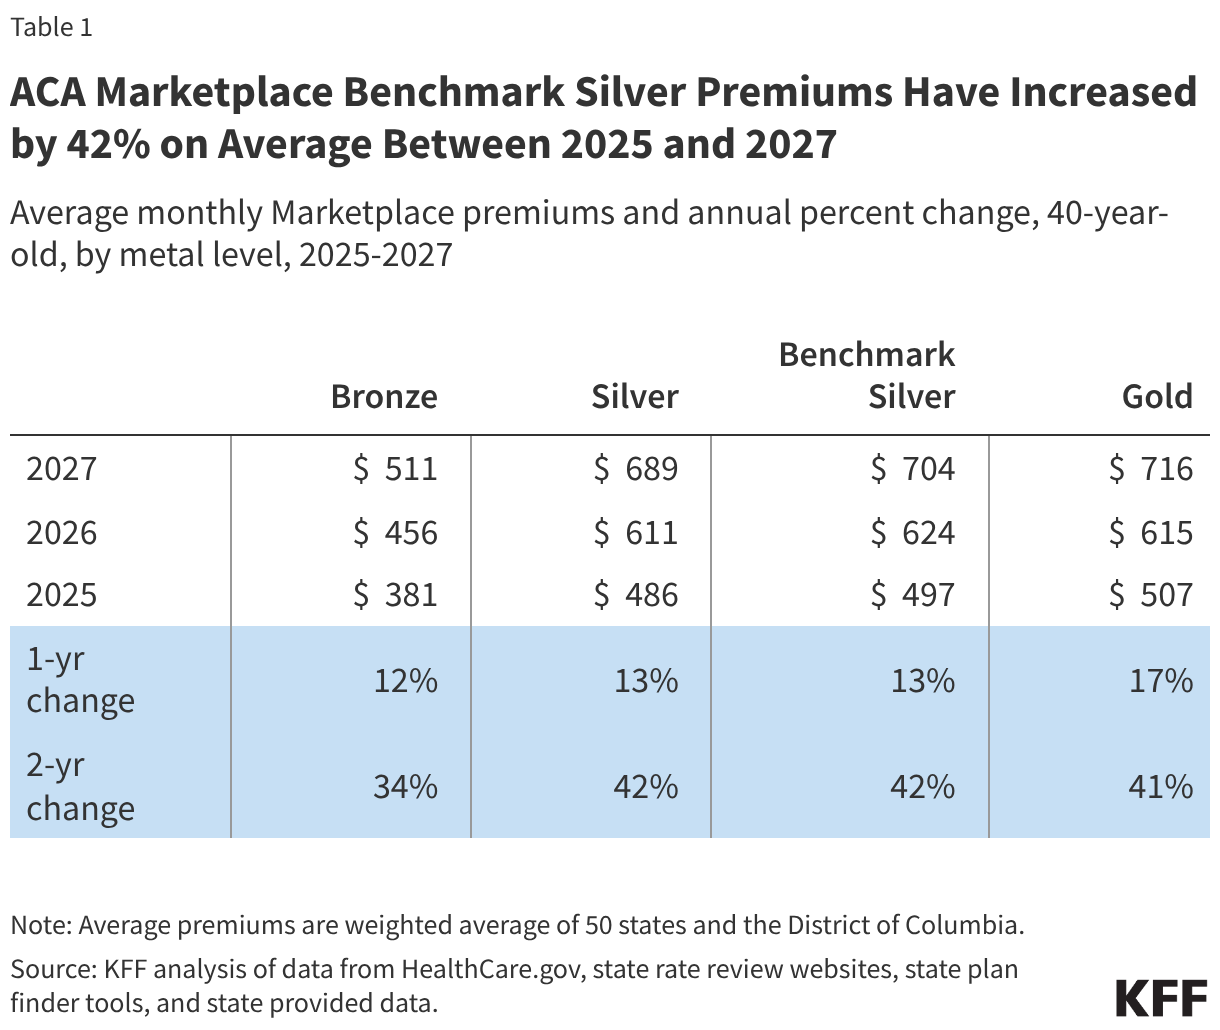
Data indicates a median proposed premium increase of 15%, with a finalized average benchmark silver premium increase of 13%. This follows a staggering 26% increase observed between 2025 and 2026. The disparity between state-based platforms and the federal Healthcare.gov system is also widening; states operating their own exchanges report average increases of 16%, while Healthcare.gov states report 11%.
Chronology of Market Shifts (2025–2027)
- Early 2025: The federal budget reconciliation law is enacted, setting the stage for future changes to tax credit eligibility, Medicaid work requirements, and the elimination of repayment caps for excess tax credits.
- Late 2025/Early 2026: Enhanced premium tax credits expire, immediately increasing the net cost of insurance for millions.
- February 2026: Effectuated Marketplace enrollment drops by 12% (approximately 2.6 million people) as the financial burden shifts to consumers.
- Summer 2026: Individual market enrollment continues a downward trend, with total enrollment falling by 18% by June 2026.
- September 2026: The Department of Health and Human Services (HHS) cancels coverage for 760,000 "phantom enrollees" and implements a moratorium on new agent/broker registrations.
- November 1, 2026: Official commencement of the 2027 Open Enrollment period.
Supporting Data: Enrollment and Financial Trends
The Congressional Budget Office (CBO) projections paint a sobering picture of the market’s trajectory. From a peak of 22.4 million enrollees in 2025, the CBO anticipates a contraction to 13.1 million by 2027. This decline is fueled by three primary factors: the loss of affordability for middle-income earners (those above 400% of the Federal Poverty Level), the exclusion of certain lawfully present immigrants from subsidy eligibility, and the administrative removal of "phantom" enrollees.
Insurer participation is also contracting. As of October 2026, 11 carriers have announced exits from at least one state, while only seven have entered new markets. The departure of major players like Cigna from the individual market in all 11 states of current operation highlights the volatility insurers face in this high-risk environment.
Regulatory and Legislative Implications
The "One Big Beautiful Bill Act" and Eligibility
The 2025 reconciliation law fundamentally altered the criteria for subsidized coverage. Perhaps most critically, it established stricter requirements for lawfully present immigrants. While refugees, asylees, and victims of human trafficking remain eligible for Marketplace access, they are now largely excluded from premium tax credits. The CBO estimates this single provision will result in one million more uninsured individuals by 2035.
Furthermore, the introduction of Medicaid work requirements across 43 states and the District of Columbia creates a new barrier to entry. Consumers denied Medicaid for failing to meet these work requirements are now barred from receiving premium tax credits in the Marketplace, leaving them in a coverage "dead zone" where they are technically eligible for insurance but priced out by the full cost of premiums.
The Elimination of Repayment Limits
For the 2026 tax year, the government removed the "repayment caps" that previously limited how much an enrollee had to return if their income exceeded their projections. Because the first tax season under these rules occurs in early 2027, many consumers are enrolling in plans without fully grasping their potential tax liability. If a household’s income spikes mid-year, they may face substantial, uncapped repayment bills, a reality that complicates the financial planning for low-to-middle-income families.
Official Responses and Litigation
The current regulatory environment is heavily contested in the federal courts. Litigation surrounding the "2025 program integrity rule" and the "2027 Payment Notice" has led to several stays on proposed reforms.
The HHS has adopted a more adversarial stance toward broker fraud, culminating in the September 2026 decision to pause the registration of new agents and brokers through February 2027. While the government claims this is necessary to protect consumers from fraudulent sign-ups—often referred to as "phantom enrollments"—industry groups argue that these restrictions, combined with a 90% cut to the federal Navigator program, severely limit the access consumers have to legitimate assistance.
In response to these federal shifts, some states have attempted to backfill the gaps. New Mexico has taken the lead by fully replacing the expired federal subsidies, a move that helped the state avoid the enrollment declines seen elsewhere. Similarly, California is expanding its state-funded subsidy program to cover households with incomes between 165% and 200% of the FPL, demonstrating a clear divide between states willing to invest in coverage and those relying entirely on federal frameworks.
Implications for the Consumer
For the average enrollee, the 2027 landscape requires a high level of vigilance.
- Increased Financial Risk: Without the safety net of capped tax credit repayments, accuracy in income reporting is no longer just a procedural necessity; it is a financial imperative.
- Reduced Access to Assistance: With the temporary moratorium on new brokers and the reduction in Navigator funding, finding reliable, independent advice on plan selection will be significantly harder than in previous years.
- The "Healthy Enrollee" Flight: As premiums rise, there is a legitimate concern that healthier individuals will drop their coverage, leaving a risk pool comprised of higher-cost, sicker enrollees. This creates a feedback loop: higher costs drive away healthy people, which in turn forces insurers to raise premiums again to cover the remaining risk.
- Disruption of Care: With 11 major insurers exiting markets, thousands of Americans will be forced to change plans and potentially switch provider networks. This disruption can lead to gaps in care for those managing chronic conditions.
Conclusion
The 2027 ACA Marketplace represents a pivotal shift in American health policy. The era of expanded, universally accessible subsidies has ended, replaced by a more restrictive, market-driven approach that prioritizes cost-containment and fraud mitigation over broad enrollment growth. As the courts continue to weigh the legality of these new rules, the burden of navigating this increasingly precarious system falls squarely on the individual. Consumers are advised to meticulously verify their income estimates, check their provider networks for insurer-exit disruptions, and explore whether their specific state offers supplementary subsidies that could mitigate the sharp increase in federal-level costs.
As the mid-term election cycle progresses and the effects of these policies become more visible, the future of the individual health insurance market remains as uncertain as it is costly. The 2027 enrollment period will likely be remembered as the moment the ACA transitioned from a growth-oriented social program to a lean, consolidated marketplace—one that offers coverage to many, but remains increasingly unaffordable to those outside the protective scope of state-based interventions.
About the Author