Editorial Note: Originally published on June 11, 2026, this report has been updated to reflect the latest carrier participation strategies for the 2027 plan year.
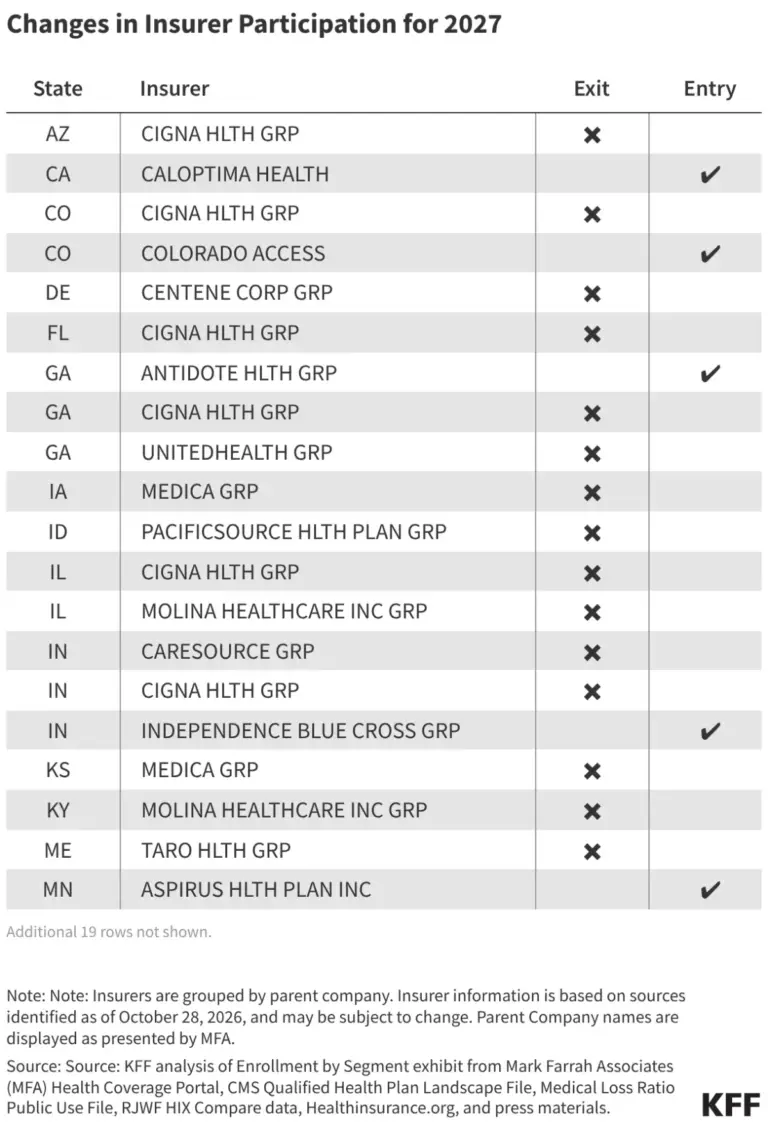
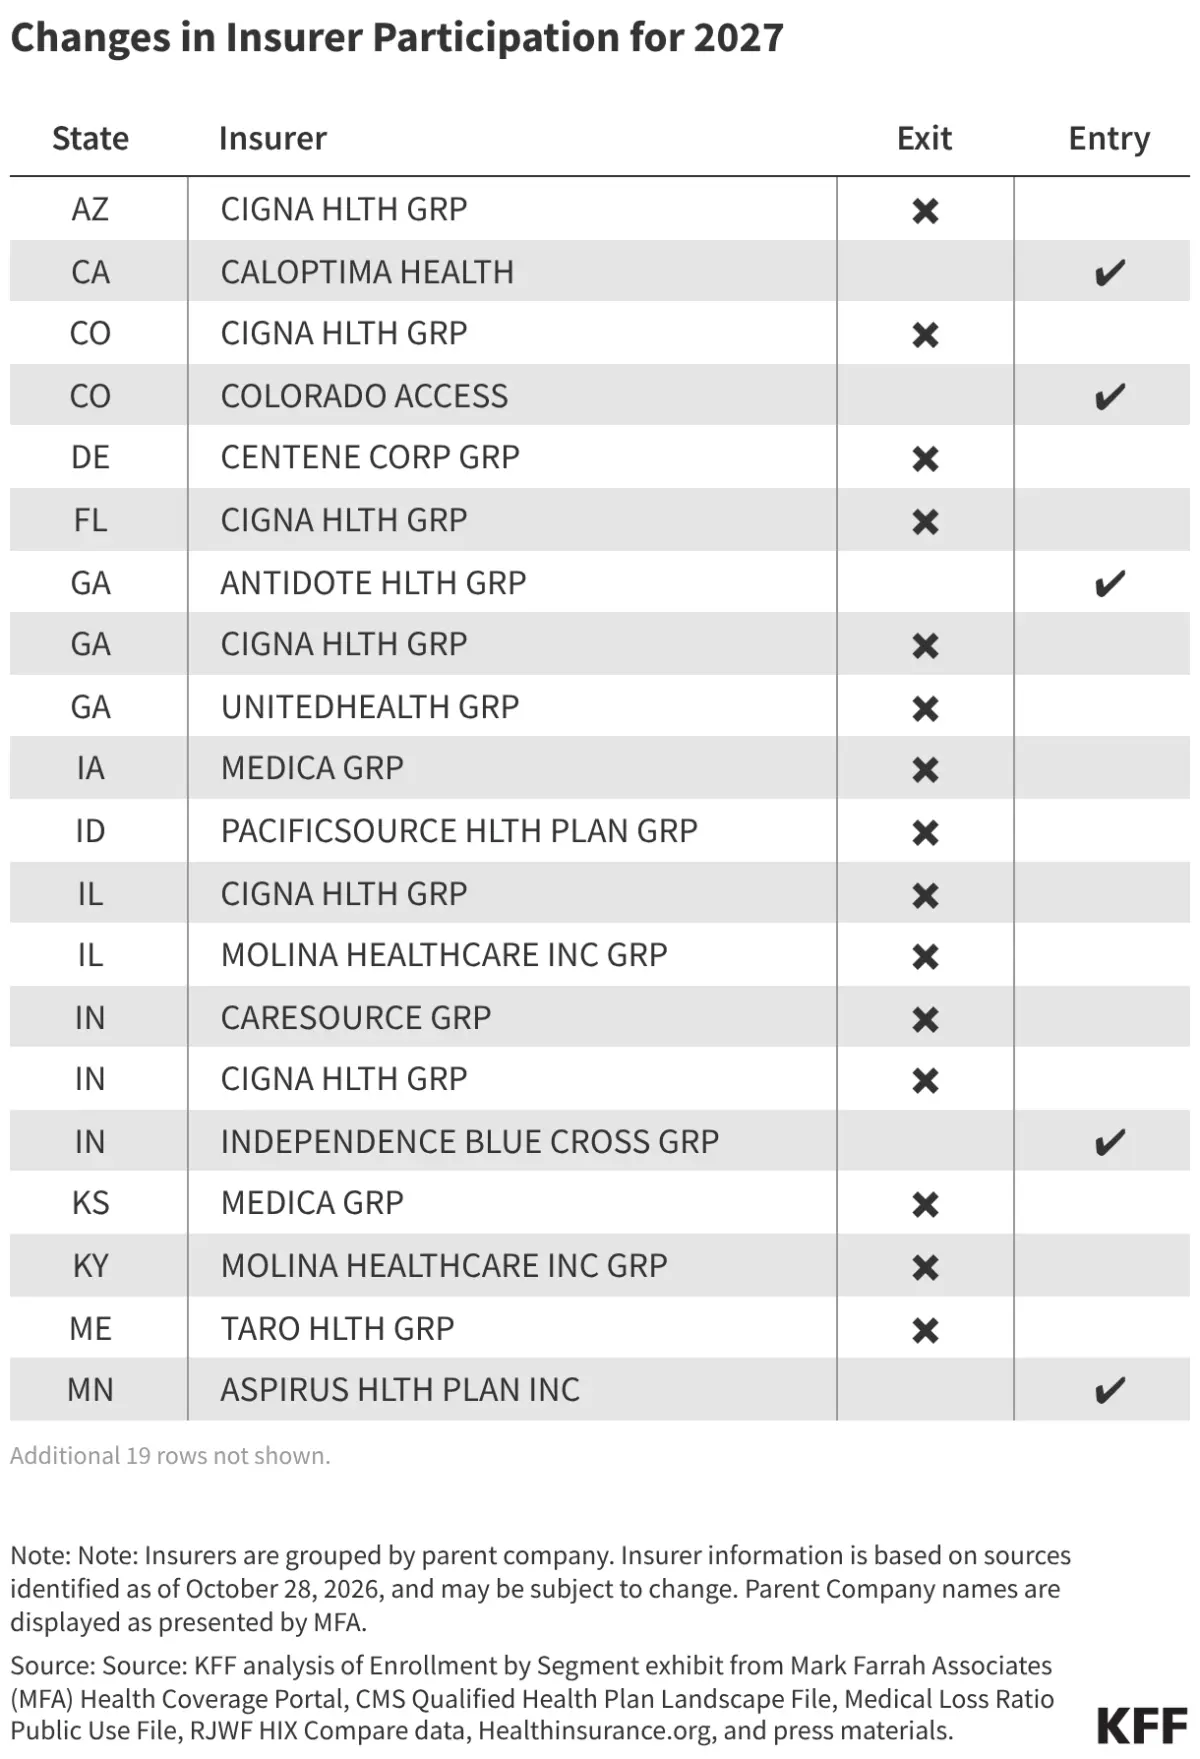
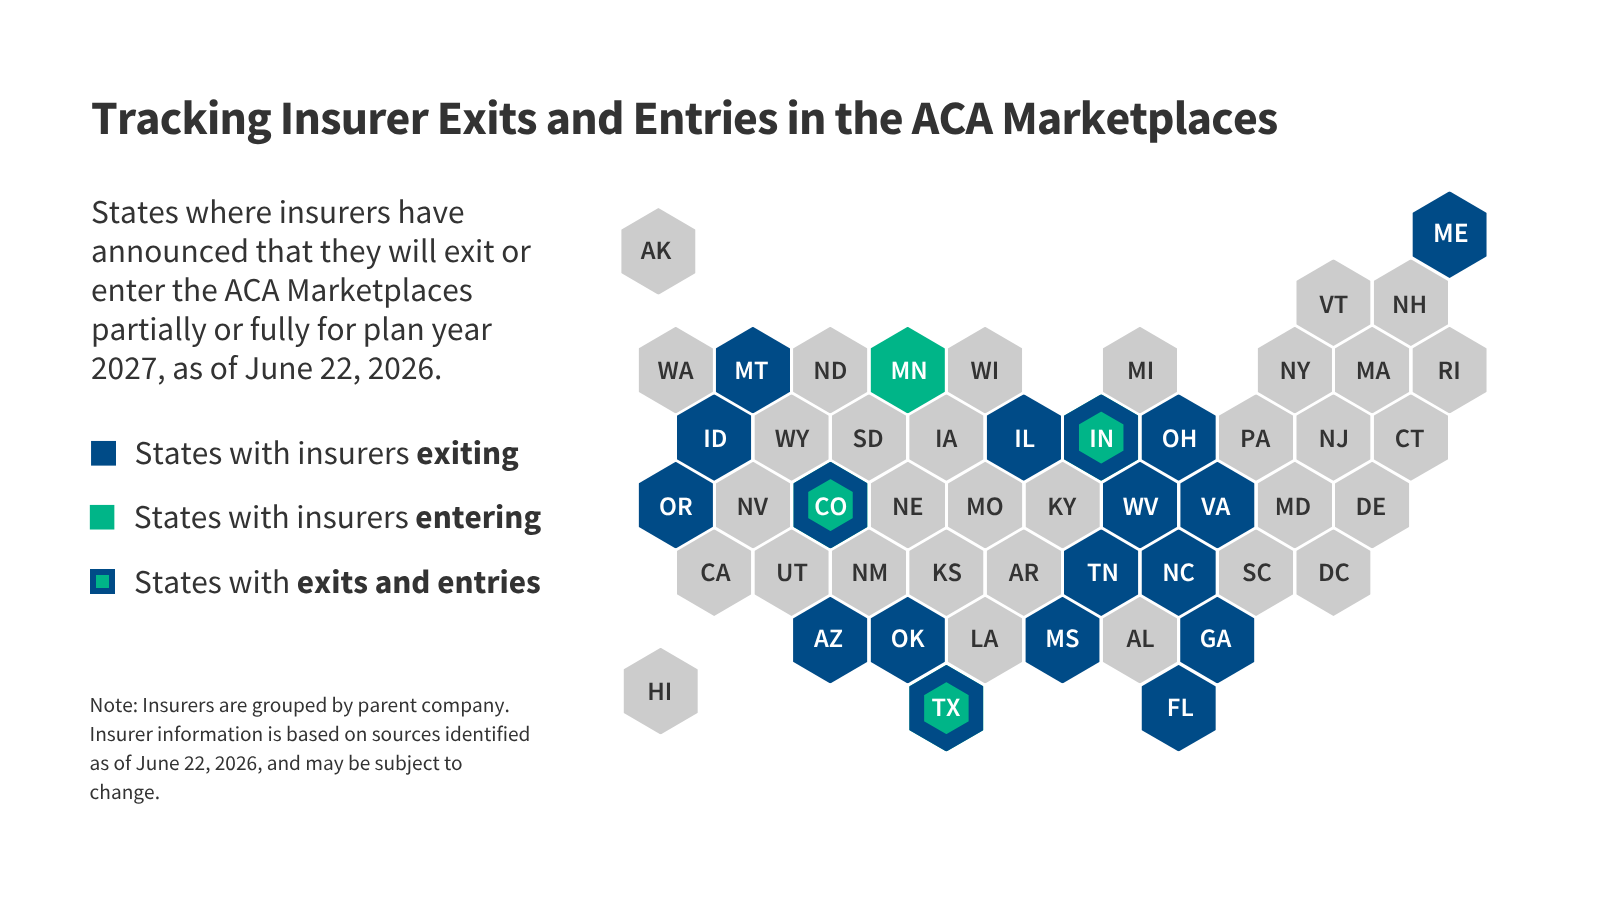
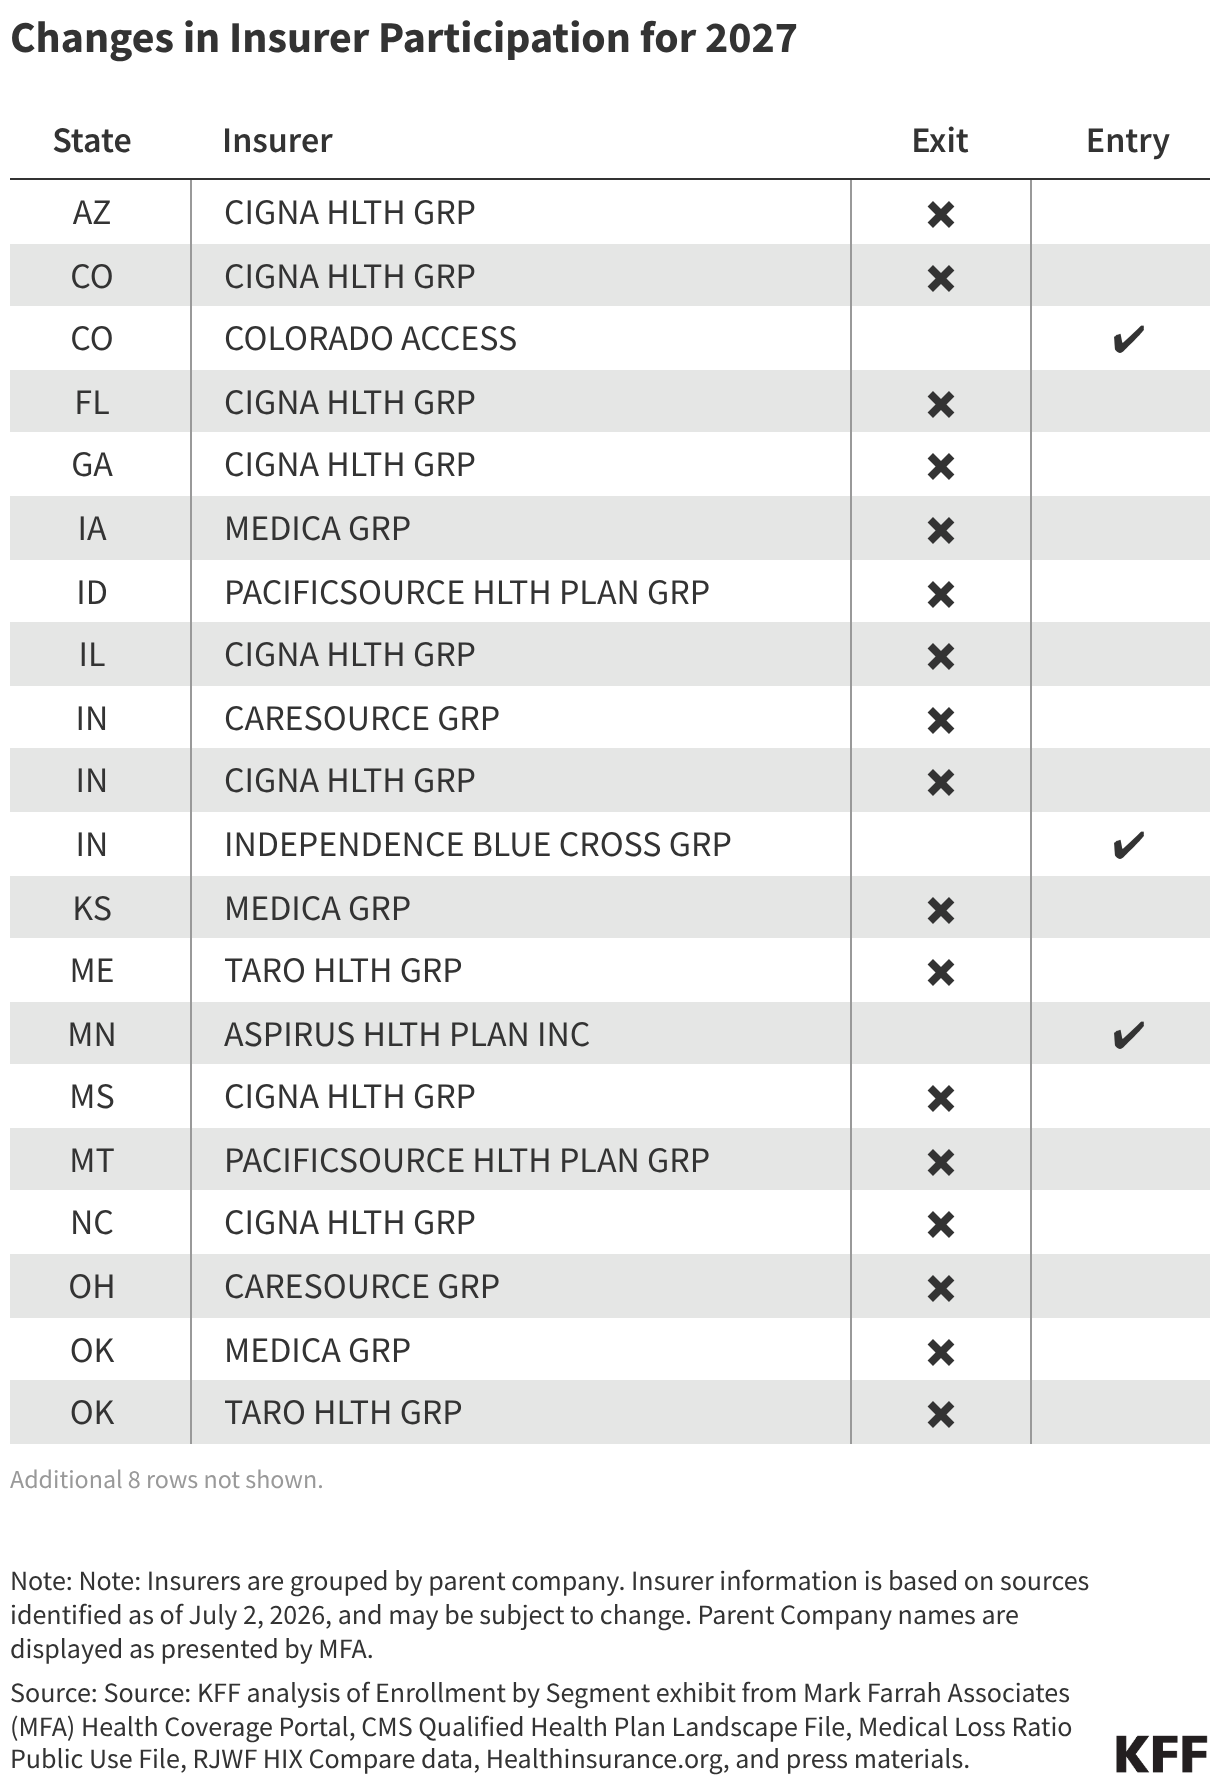
The landscape of the Affordable Care Act (ACA) Marketplaces is undergoing a significant transformation as the industry navigates the post-subsidy era. As of October 28, 2026, the market is bracing for a wave of instability: 11 insurance carriers have confirmed their intent to exit ACA Marketplaces for the 2027 plan year—either partially or entirely—across their current operational states. While seven other carriers have announced plans to enter new state markets, the net effect is a palpable sense of contraction in a sector that had enjoyed years of unprecedented expansion.
This structural shift follows the expiration of enhanced premium tax credits at the end of 2025, a policy sunset that has already precipitated a sharp decline in enrollment. Between the 2025 and 2026 Open Enrollment Periods, the marketplace saw over a million individuals drop their coverage. Experts anticipate that this downward trend will persist throughout 2026 and into 2027, raising fundamental questions about the long-term viability of the ACA individual market.
The Chronology of Market Contraction
The current volatility did not happen in a vacuum. To understand the 2027 exit announcements, one must look at the timeline of legislative and market-driven pressures:
- Late 2025: The expiration of enhanced premium tax credits removed a critical financial buffer that had kept premiums artificially low and accessibility high for millions of middle-income Americans.
- Early 2026: Initial data from the 2026 Open Enrollment Period confirmed the fears of policy analysts: enrollment figures plummeted by over one million participants. This initial exodus signaled that for many, health insurance had once again become a discretionary expense rather than a guaranteed utility.
- Mid-2026: Insurers began conducting internal audits of their "exchange" portfolios. With smaller risk pools and reduced federal subsidies leading to lower overall volume, the administrative costs of maintaining these plans began to outweigh the potential for growth.
- October 2026: The formal announcement window for 2027 plan year participation closed, revealing that 11 major carriers would retreat from specific state markets. This development solidified the current trend of consolidation.
Supporting Data: The Ripple Effect of Declining Enrollment
The math behind insurer participation is relatively straightforward: insurers require a broad, diverse risk pool to remain profitable. When enrollment declines, it is rarely a uniform process. Research suggests that healthier enrollees—who are often the most price-sensitive—are the first to drop coverage when premiums rise or subsidies vanish.
As these healthier individuals exit, the remaining risk pool becomes "sicker" on average, leading to higher claims costs. This creates a "death spiral" dynamic that forces insurers to either raise premiums further (making the product even less attractive) or exit the market entirely to protect their bottom lines.
The data from the 2026 enrollment period acts as a precursor to these 2027 exits. With total membership numbers declining, the "addressable market" for private insurers has shrunk significantly. For a company like Cigna, which reported over 350,000 on-exchange enrollees in early 2026, the decision to leave is a strategic pivot toward more lucrative, high-growth segments of their business.
Official Responses and Strategic Pivots
The decision-making process for these departures is driven by corporate strategy and the pursuit of shareholder value.
The Case of Cigna
Cigna’s decision to exit the individual market in 2027 is perhaps the most notable example of this corporate reassessment. During recent earnings calls, Cigna leadership characterized their ACA business as a shrinking segment that no longer aligned with the company’s long-term growth trajectory.
"This is small business for us today, and it’s been shrinking in recent years," noted Chris Evanko, a senior executive at The Cigna Group. "The decision will allow us to further intensify focus on our core growth platforms."
This sentiment is echoed across the industry. When a major player like Cigna exits, it leaves a void in 11 states where they were previously a cornerstone of both on- and off-exchange offerings. For the remaining carriers, this may initially seem like an opportunity to capture market share, but it also reflects a deeper concern: if a giant like Cigna cannot find profitability in the current ACA environment, smaller, regional insurers may soon find themselves in the same position.
Implications: A Future of Fewer Choices
The implications of these exits for the average consumer are profound. In several states, the departure of multiple insurers will lead to a "coverage desert" where consumers are left with a limited number of plans, or, in extreme cases, a single provider.
Reduced Competition and Pricing Power
When competition declines, pricing power shifts toward the remaining insurers. Without the pressure of a crowded marketplace, insurers are less incentivized to offer aggressive pricing or expanded provider networks. This lack of competition effectively negates one of the primary goals of the ACA: to provide a competitive marketplace that drives down costs for the consumer.
The Risk Pool Problem
As mentioned previously, the "adverse selection" problem is the most dangerous implication for the ACA’s future. If the market continues to contract, and the only people who can afford or justify insurance are those with chronic, expensive health conditions, the risk pool will become unsustainable. This will necessitate higher premiums, which in turn will drive more healthy people out of the market. This feedback loop is precisely what policymakers and health advocates are working to prevent.
The Political Dimension: Health Care in the 2026 Midterms
The timing of this market contraction is particularly sensitive as the nation navigates the 2026 midterm election cycle. Health care remains a top-tier issue for voters, and the stability of the ACA is a central point of debate.
KFF’s ongoing series, Health in the 2026 Midterm Elections, highlights that voters are increasingly aware of the link between legislative subsidies and their monthly premiums. As insurance carriers announce their 2027 exits, the political discourse has sharpened, with candidates on both sides of the aisle attempting to frame the market instability as a failure of their opponents’ policy frameworks.
The debate is no longer about the implementation of the ACA, but about its survival in a post-subsidy environment. Proponents of extended subsidies argue that the market cannot function without federal support, while critics argue that the reliance on subsidies proves the market was never truly "self-sustaining" in the first place.
Conclusion: The Path Forward for 2027
As we look toward 2027, the ACA Marketplace is at a critical juncture. The combination of legislative sunsets, shifting insurer strategies, and shrinking risk pools has created a perfect storm of uncertainty.
For the 11 carriers exiting, the decision is a calculated business move intended to protect their bottom lines. For the seven carriers entering new states, there may be a strategic belief that they can succeed where others have failed, or that they can leverage specific regional demographics to maintain a viable risk pool.
However, for the millions of Americans who rely on the ACA for their health coverage, the next year will be defined by uncertainty. The ability of states to mitigate these exits through aggressive outreach, potential state-level subsidies, or increased regulation will be the primary factor in determining whether the ACA remains a functional safety net or continues to fragment.
As the 2027 Open Enrollment Period approaches, all eyes will be on the enrollment data. If the downward trend continues, the federal government may face mounting pressure to intervene—either through new legislative efforts to restore premium supports or through fundamental structural reforms to the ACA itself. Until then, the marketplace remains in a state of flux, characterized by the uneasy tension between private corporate strategy and the public need for affordable, accessible health care.
About the Author