The pharmaceutical landscape for obesity and diabetes treatment has been fundamentally altered by the meteoric rise of GLP-1 receptor agonists. While demand for blockbuster drugs like Wegovy and Ozempic (semaglutide) and Zepbound and Mounjaro (tirzepatide) has revolutionized weight management, it has also spawned a massive, largely unregulated shadow market. As of mid-2026, the intersection of aggressive telehealth marketing, questionable pharmacy compounding practices, and a persistent surge in adverse event reports has created a perfect storm for regulators, lawmakers, and, most importantly, patients.
Recent data indicates that the FDA has logged more than 1,700 adverse event reports linked to compounded semaglutide and tirzepatide. This figure, while significant, is widely viewed by experts as a conservative estimate of the actual clinical impact, given that many state-licensed compounding pharmacies are not under federal mandates to report such occurrences.
The Rise of the "Copycat" Empire
The gold rush surrounding GLP-1 agonists has attracted a new breed of tech-forward, direct-to-consumer enterprises. Among these, MEDVi emerged as a prominent player, with reports suggesting it was on track for $1.8 billion in sales in 2026, following a $401 million performance in 2025.
However, the rapid growth of these entities has invited intense scrutiny. In February 2026, the FDA issued a scathing warning letter to MEDVi, alleging that the company was masking the origins of its compounded products and misleading consumers by implying they were equivalent to FDA-approved, mass-produced pharmaceuticals. MEDVi countered that the letter was directed at an affiliate, yet archival evidence of its digital footprint—routing users through complex intake systems and naming MEDVi LLC as the primary contracting party—suggests a highly integrated, if opaque, corporate structure.
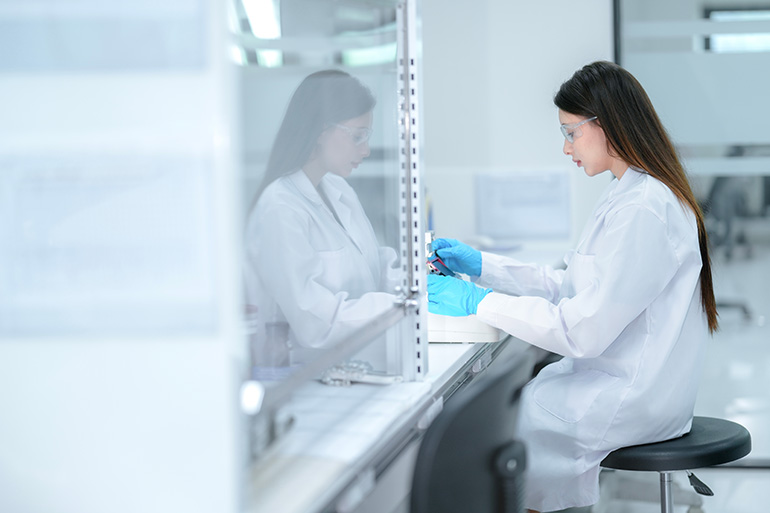
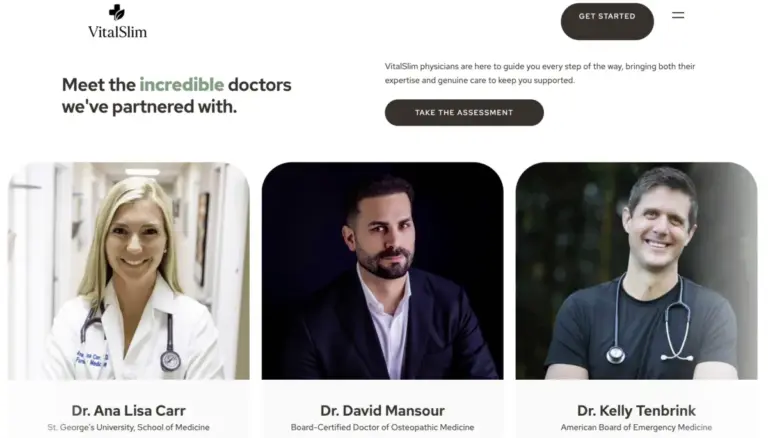
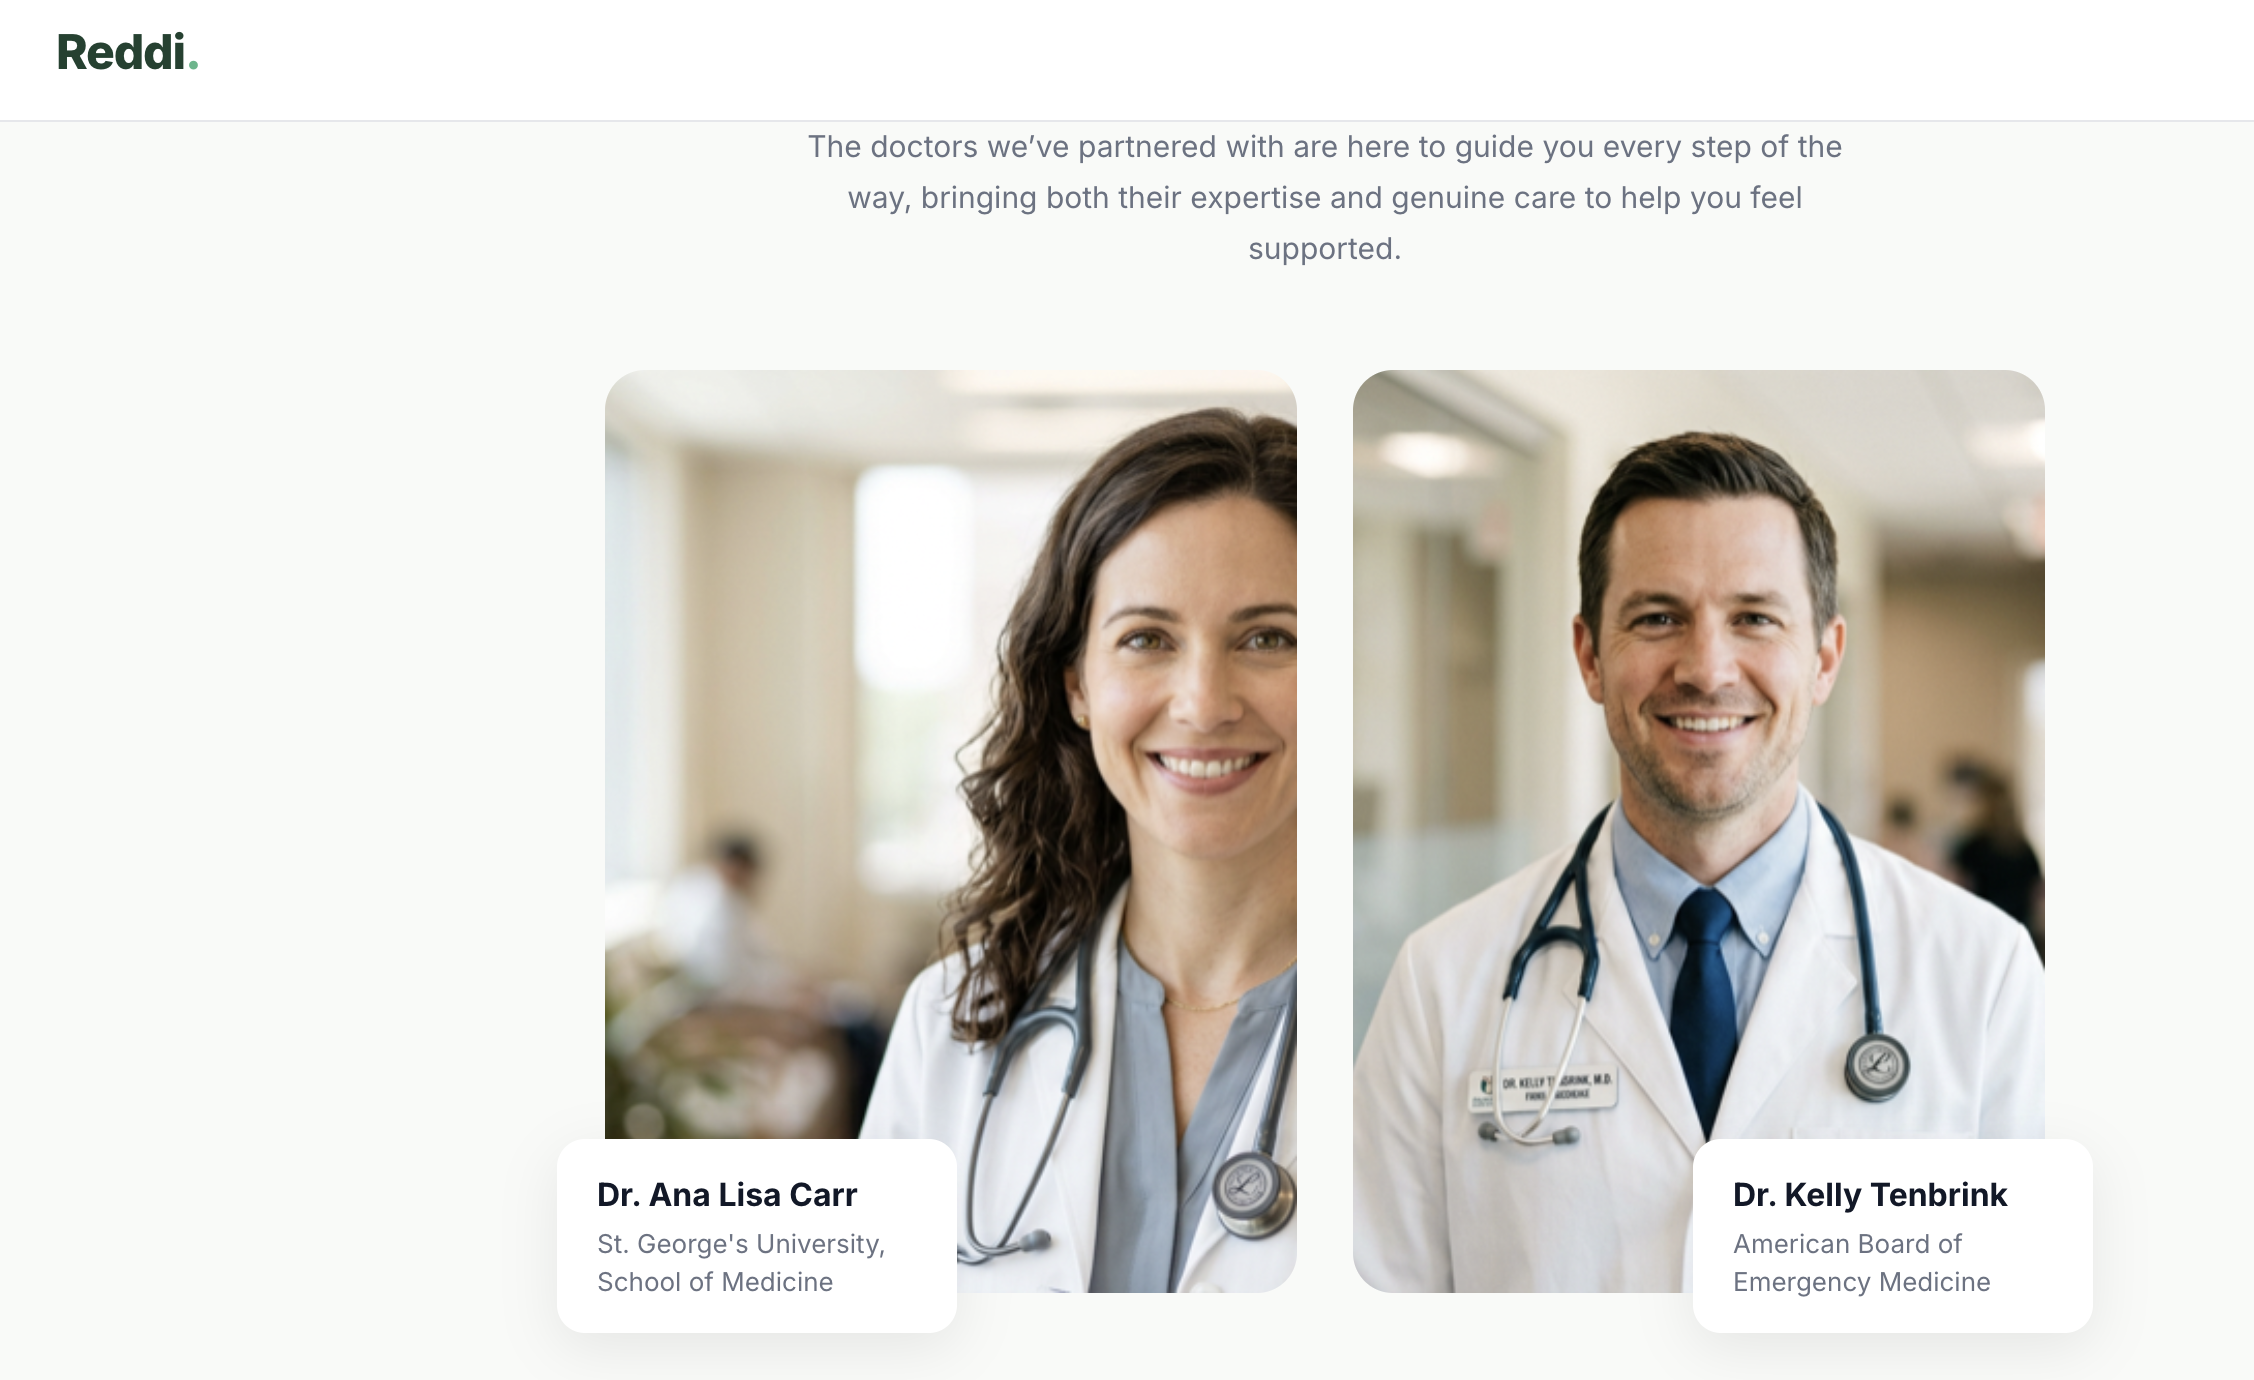
This playbook appears to be industry-wide. A pattern has emerged where multiple telehealth "storefronts" share identical clinician rosters, pharmacy networks, and marketing materials. Sites like VitalSlim and MDRxLabs have featured the same physicians previously utilized by MEDVi, all while relying on a centralized medical-provider network, such as OpenLoop Health. This ecosystem of interconnected companies creates a "whack-a-mole" scenario for regulators: if one site is shut down or warned, the underlying infrastructure of medical providers and pharmacies remains largely intact, fueling a new iteration of the same business model.
A Chronology of Regulatory Friction
The path to the current crisis began in 2022, when the FDA officially placed Wegovy, Ozempic, and tirzepatide on the national drug shortage list. This designation provided a narrow, temporary legal window for compounding pharmacies to create "essentially copies" of these drugs, provided they were not made under unsanitary conditions.
- March – December 2022: The FDA adds Wegovy, Ozempic, and tirzepatide to the shortage list, effectively legalizing the compounding of these agents.
- September 2025: Facing an explosion of illicit online sales, the FDA issues a massive wave of over 55 warning letters to telehealth companies in a single day.
- December 2024 – February 2025: The FDA declares the shortages of tirzepatide and semaglutide resolved, officially signaling the end of the compounding loophole.
- May 22, 2025: The final window of "enforcement discretion" for compounding these drugs closes.
- 2026: The FDA ramps up enforcement, issuing dozens of additional warning letters in March and June, citing violations of the Federal Food, Drug, and Cosmetic Act (FDCA) regarding misbranding.
Despite these actions, the industry has proven resilient. The Outsourcing Facilities Association even initiated litigation against the FDA in late 2024, contesting the agency’s decision to remove the drugs from the shortage list, arguing that the supply had not sufficiently stabilized to meet demand.
Supporting Data: The Safety and Economic Toll
The clinical data behind these reports is increasingly alarming. America’s Poison Centers reported a staggering 1,500% increase in GLP-1 agonist exposure cases between 2019 and 2025, totaling 22,966 cases. While many of these instances involved accidental therapeutic errors with FDA-approved pens, the compounded market presents unique dangers.
The primary concern involves dosing errors. Unlike the pre-filled, precision-engineered pens provided by manufacturers like Novo Nordisk and Eli Lilly, compounded versions often require patients to use vials and syringes. This has led to a documented prevalence of 10-fold dosing mistakes, where patients, confused by complex measurement units, self-administer dangerously high doses.
Economically, the scale is unprecedented. Empower Pharmacy, a Houston-based entity, reported $377 million in revenue for 2024, with GLP-1 formulations comprising two-thirds of that total. Bankers estimate that the entire compounded weight-loss sector is now generating roughly $1 billion annually, creating a powerful financial incentive for companies to continue operating in the gray market despite mounting regulatory pressure.
Official Responses and Legislative Intervention
The response from both the federal government and the pharmaceutical giants has been aggressive. Novo Nordisk has filed over 130 lawsuits across 40 states to protect its patents and address safety concerns, securing dozens of permanent injunctions. Eli Lilly has taken similar steps, targeting both the pharmacies producing the drugs and the telehealth companies marketing them.
In Congress, the response has taken the form of the SAFE Drugs Act of 2025. This bipartisan legislation seeks to strictly limit the compounding of drugs that are "essentially copies" of commercially available products. If passed, it would cap such compounding to no more than 20 units per month, unless a specific clinical necessity is documented. While the bill aims to restore safety standards, it faces stiff opposition from the Alliance for Pharmacy Compounding and the National Community Pharmacists Association, who argue that the limitations would unnecessarily restrict patient access to care.
Implications: The Future of Telehealth and Patient Safety
The implications of this crisis are far-reaching. Beyond the immediate health risks, there is a growing concern regarding the "telehealth-as-a-service" model. Investigations have revealed that many of these platforms are less concerned with medical outcomes than with subscriber acquisition. Reports of recurring, unauthorized charges, difficulties in canceling subscriptions, and opaque pricing structures are rampant.
Furthermore, there are allegations of systemic fraud. A pending civil RICO complaint involving OpenLoop and Triad Rx alleges that these companies provided the hidden infrastructure for a network of storefronts selling oral tirzepatide—a formulation that medical experts claim has no demonstrated absorption or efficacy. This highlights a terrifying reality: the patient is often the last to know the actual source, composition, or medical validity of the product they are injecting into their bodies.
As the FDA continues to refine its enforcement strategies and Congress debates the future of compounding, the onus remains on the patient to exercise extreme caution. The "GLP-1 boom" has proven that the allure of rapid weight loss can easily overshadow the risks of unregulated medical products. For the pharmaceutical industry, the focus is now on containment—protecting the reputation of life-saving medications from being tarnished by a dangerous, profit-driven secondary market that prioritizes speed over science.
The coming months will likely see further legal battles and a tightening of the regulatory net. Whether these measures will be sufficient to curb the tide of adverse events remains to be seen, but one thing is clear: the era of the "wild west" in GLP-1 compounding is facing its most significant reckoning to date.
About the Author