In September 2026, the Trump administration announced a high-profile initiative to distribute one-time, $500 "refund checks" to approximately one million Americans enrolled in Affordable Care Act (ACA) plans through the federal HealthCare.gov platform. The administration framed these payments as a return of "excess user fees" collected from insurers during the Biden administration—fees that, according to the White House, were unfairly levied on consumers.
However, the reality of these payments is complex. While the announcement suggests a straightforward return of taxpayer money, the mechanics of how these funds were collected, why they accumulated, and whether a $500 check provides meaningful relief to those grappling with soaring healthcare costs remain subjects of intense debate among policy experts.
The Genesis of the $500 Refund
The policy targets a specific segment of the population: the roughly 5% of all ACA Marketplace enrollees who signed up for coverage in 2026 without the benefit of federal premium tax credits. These individuals, who bear the full burden of their monthly premiums, were identified as the primary victims of the "excess user fees" collected under the previous administration.
The user fee in question is a percentage of the total premium that participating insurance companies pay to the federal government to fund the operation of the Marketplace. These operations include IT maintenance, eligibility verification, consumer outreach, and the functioning of the HealthCare.gov portal. Because insurers fold these fees into the premiums they charge, they are effectively paid by consumers or, in the case of subsidized enrollees, by the federal government itself via tax credits.
A Chronology of Marketplace User Fees
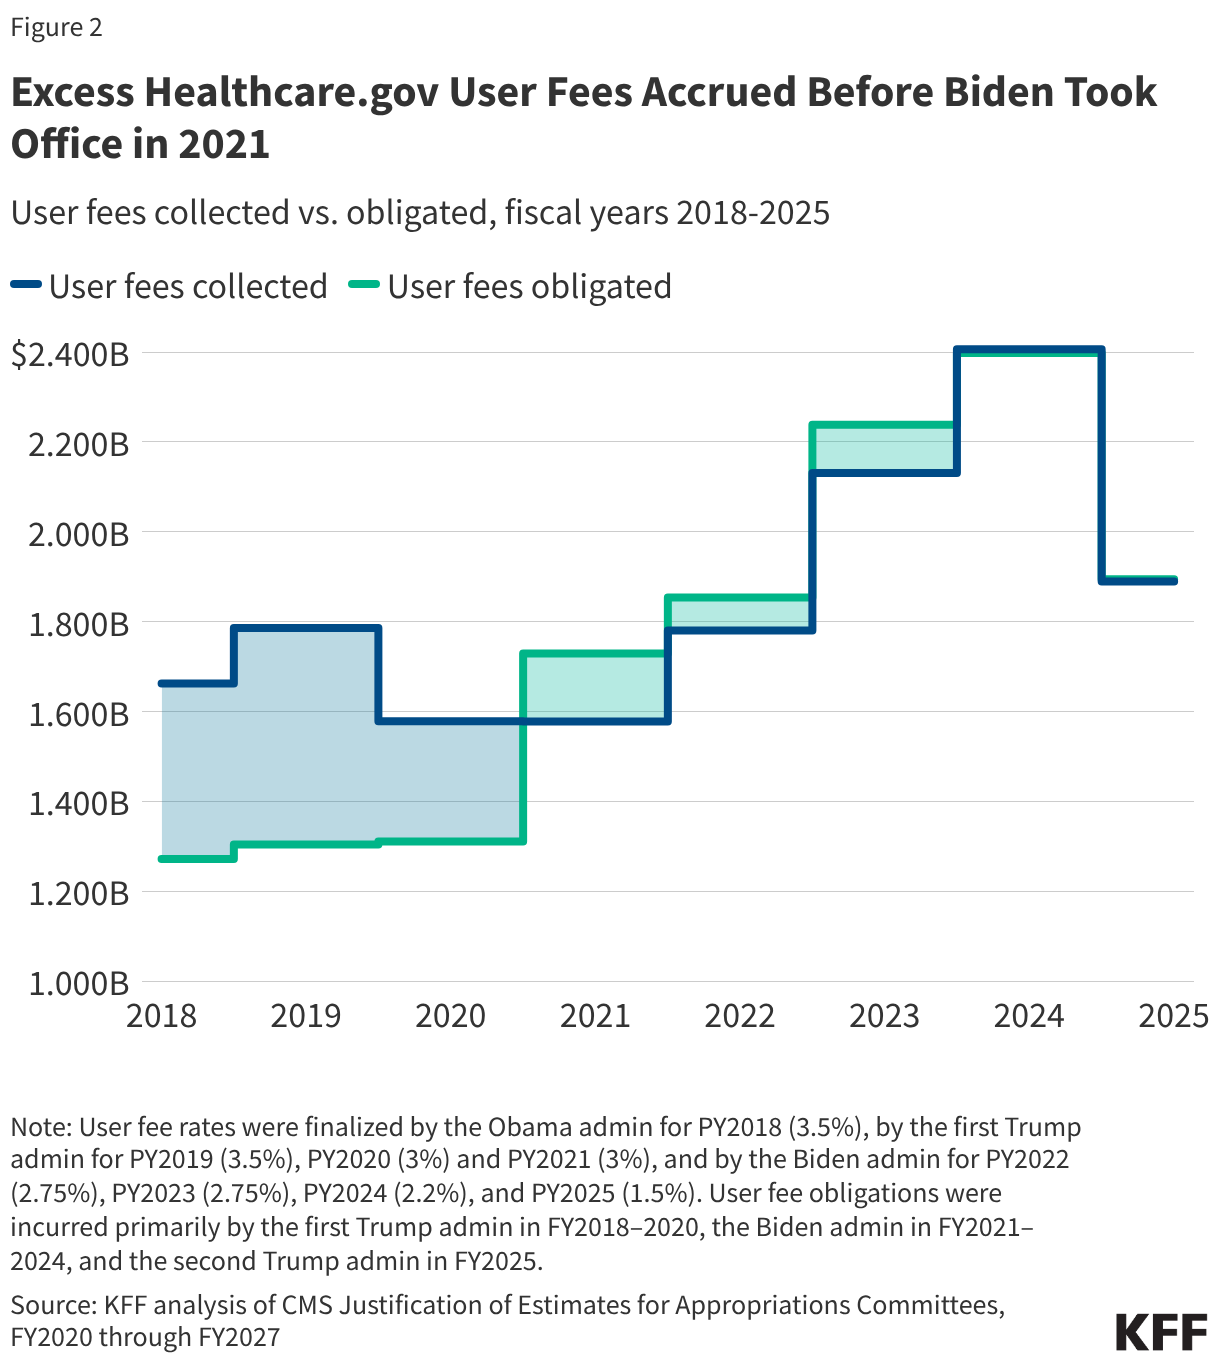
To understand the current "refund" strategy, one must look at the historical trajectory of user fee rates, which have fluctuated significantly across presidential administrations.
The 3.5% Era (2014–2019)
From the inception of the ACA Marketplace in 2014 through the early years of the first Trump administration, the Federally Facilitated Marketplace (FFM) user fee remained steady at 3.5%. This rate was intended to ensure a robust budget for outreach and the development of the nascent insurance exchanges.
The Shift Toward Efficiency (2020–2021)
In 2020, the first Trump administration lowered the user fee to 3.0%. The administration argued that "operational efficiencies"—specifically in IT functionality and a streamlined approach to consumer outreach—allowed the government to maintain the exchange with lower costs. This rate remained in effect through 2021.
The Biden Administration’s Reinvestment (2022–2025)
Upon taking office, the Biden administration re-evaluated these costs. In 2022, the user fee was adjusted to 2.75% to account for increased contract costs and a surge in enrollment. Following this, the administration leaned into an aggressive strategy of funding consumer navigation and enrollment assistance. While the user fee rate eventually hit an all-time low of 1.5% in 2025, the total volume of fees collected grew substantially because of the massive increase in enrollment triggered by the availability of enhanced premium tax credits.
The Second Trump Administration (2026–2027)
Following the expiration of enhanced premium tax credits, the second Trump administration set the 2026 user fee at 2.5%. By 2027, this was further reduced to 1.9%. The $500 checks, announced in the fall of 2026, serve as a retroactive adjustment to the revenue surplus accumulated during the final years of the Biden-era enrollment surge.
Supporting Data: Where Did the Money Go?
The federal government is not legally required to return unused user fees to insurers or consumers. In the past, surplus revenue has been carried over to cover future operational costs or used to lower future fee requirements. The current administration’s decision to issue checks is a departure from historical precedent, raising questions about the source of the funds and the methodology used to calculate the $500 amount.
Spending Trends: The "Outreach" Gap
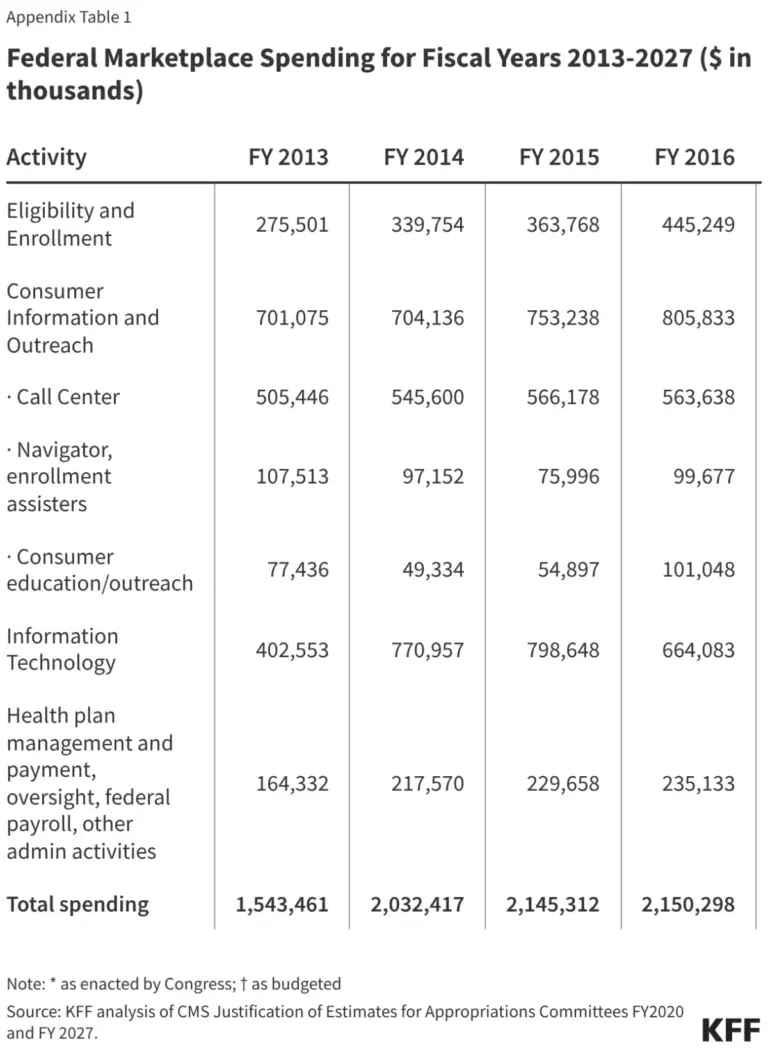
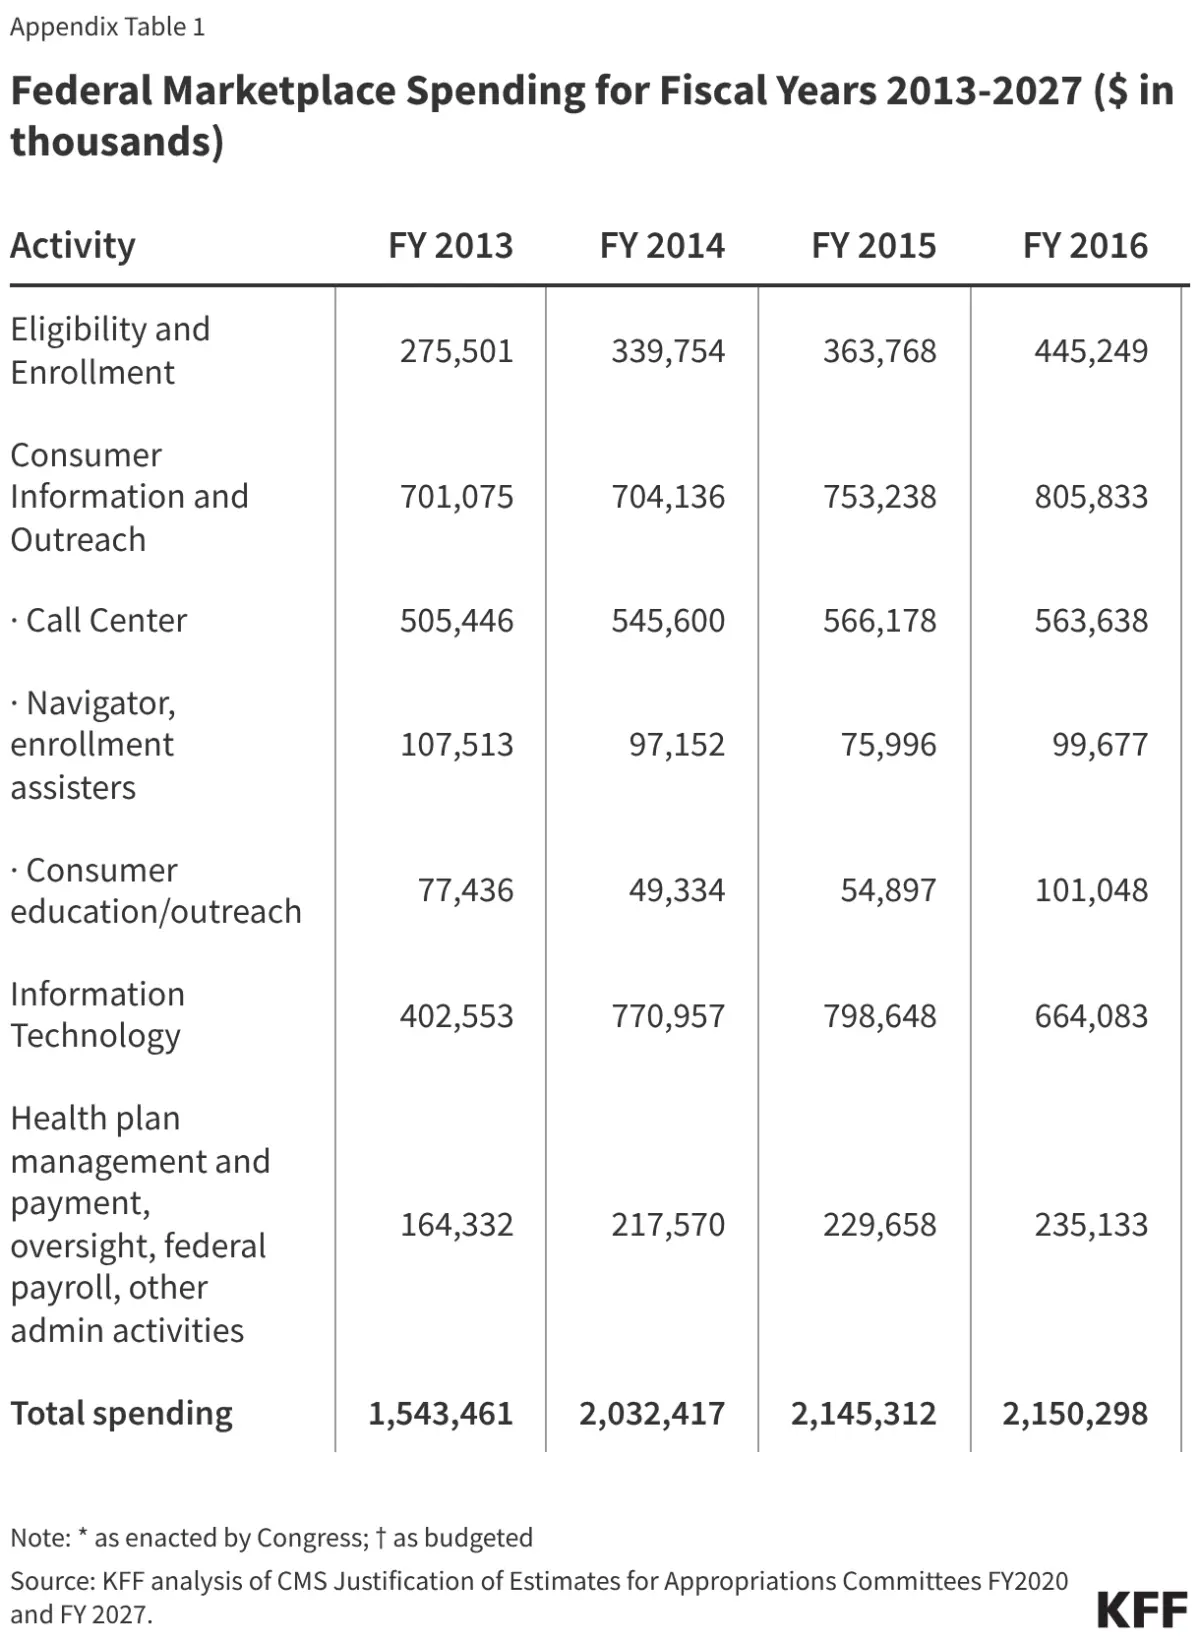
A review of CMS budgetary documents reveals that the primary variable in Marketplace spending is not IT or administration, but rather "consumer information and outreach."
- FY 2016–2020: During the first Trump administration, spending on Navigators and enrollment assisters plummeted from nearly $100 million to approximately $20 million. Overall consumer outreach spending dropped by nearly 40%.
- FY 2021–2023: The Biden administration reversed this trend, ramping up outreach spending to $1.2 billion by 2023. This investment coincided with record-high enrollment numbers.
- FY 2025–2026: Spending on outreach declined once more under the current administration, dropping to $778 million in 2025, effectively aligning spending more closely with the incoming revenue stream.
Official Responses and Legal Ambiguity
The White House has touted these payments as a victory for the "working families" of America, emphasizing that the government is returning money that rightfully belongs to the consumer. However, the administration has provided little in the way of a legal framework for these payments, nor has it explained the "flat-rate" nature of the $500 check.
Critics in the policy community note that the user fee is a percentage of the premium, meaning a person’s contribution to the surplus is relative to their plan’s cost. A flat $500 check, therefore, results in a "windfall" for some and a "pittance" for others, regardless of how much they actually paid into the system. Furthermore, millions of taxpayers—who subsidized the premiums of others through the ACA—are effectively paying for these refunds through the broader federal budget, despite having no claim to the "user fee" surplus.
Implications: The Reality of Rising Premiums
While $500 may seem like a generous gesture, an analysis of current market trends suggests that it is insufficient to address the broader financial reality faced by unsubsidized enrollees.
The "Missing" Subsidy Gap
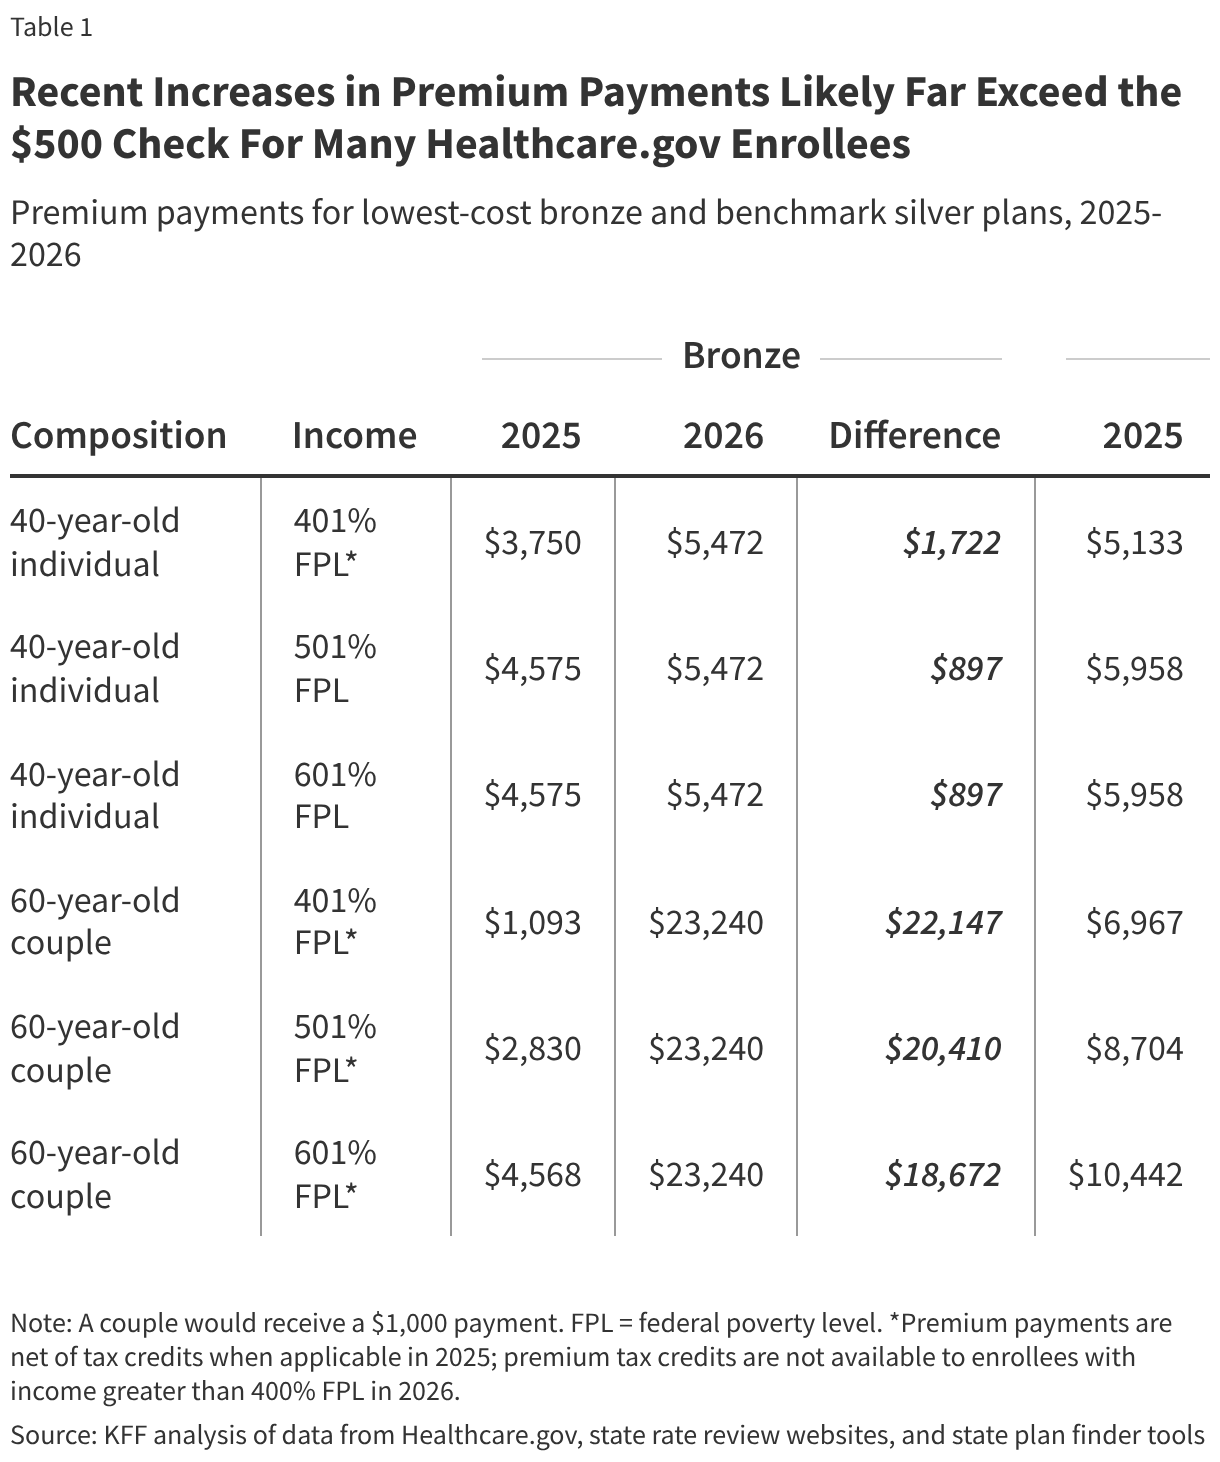
For many, the loss of enhanced premium tax credits has been a devastating financial blow. The average premium for a HealthCare.gov enrollee without a tax credit rose from $6,660 in 2025 to $8,844 in 2026—an increase of over $2,100. A $500 refund covers less than a quarter of this increase.
The Demographic Impact
The burden is not shared equally. Older adults, who frequently purchase bronze-level plans, are facing the most significant hikes. For a 60-year-old couple, the national average annual premium rose by thousands of dollars between 2025 and 2026. In this context, a $500 check acts as a minor cushion rather than a systemic solution.
Looking Toward 2027
The financial outlook for 2027 remains grim for those without subsidies. Projections indicate that benchmark premiums could rise by another 11%, potentially adding $876 or more to the annual cost of coverage for a 40-year-old. For older populations, the projected increases could exceed $2,000.
Conclusion
The $500 "refund" checks are a symbolic policy maneuver that attempts to reconcile the surplus of the previous administration’s user fees with the political goal of providing direct, tangible aid to consumers. However, when measured against the backdrop of rising premiums, the expiration of federal tax credits, and the structural costs of the healthcare market, the payment functions more as a temporary gesture than a sustainable fix.
As the federal government continues to balance the books on Marketplace operations, the fundamental challenge remains: how to maintain a functional, accessible exchange system when the cost of coverage is outpacing the ability of the average American household to pay. For now, the million recipients of these checks will see a small, one-time relief, while the broader, more persistent issue of premium affordability remains an unresolved crisis in the American healthcare landscape.
About the Author