Editorial Note: Originally published on June 11, 2026, this report has been updated to incorporate the latest filings and carrier strategy announcements as of October 7, 2026.
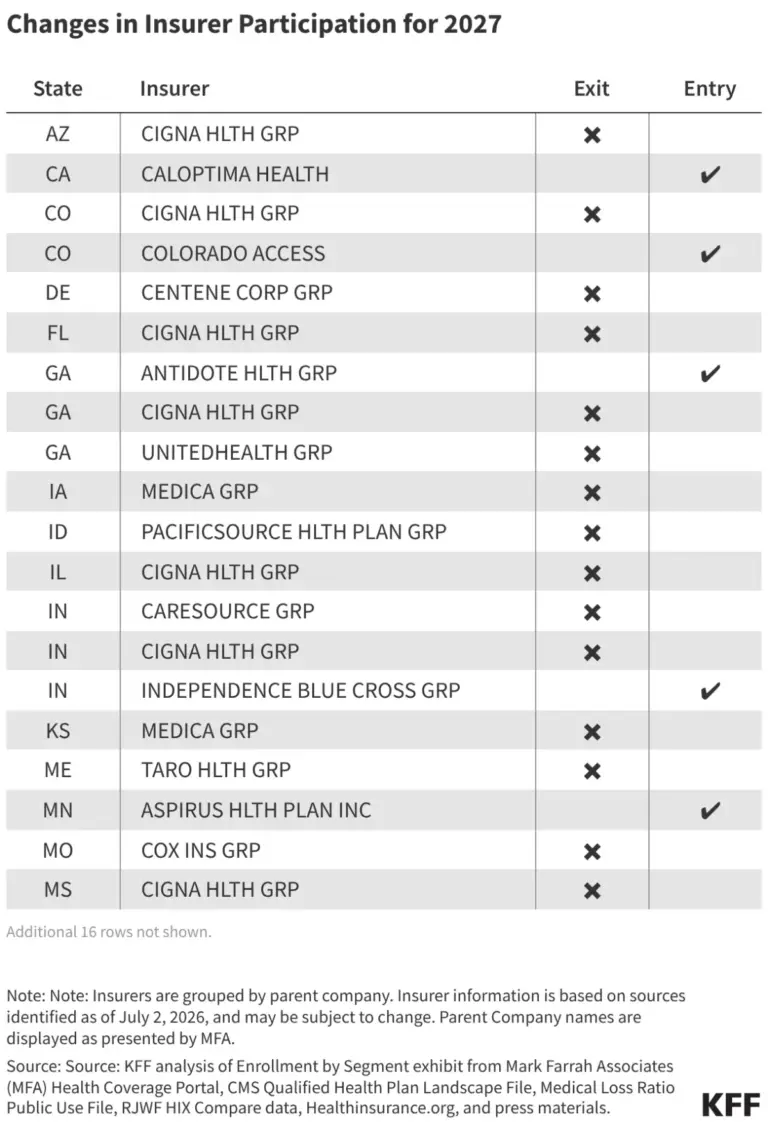
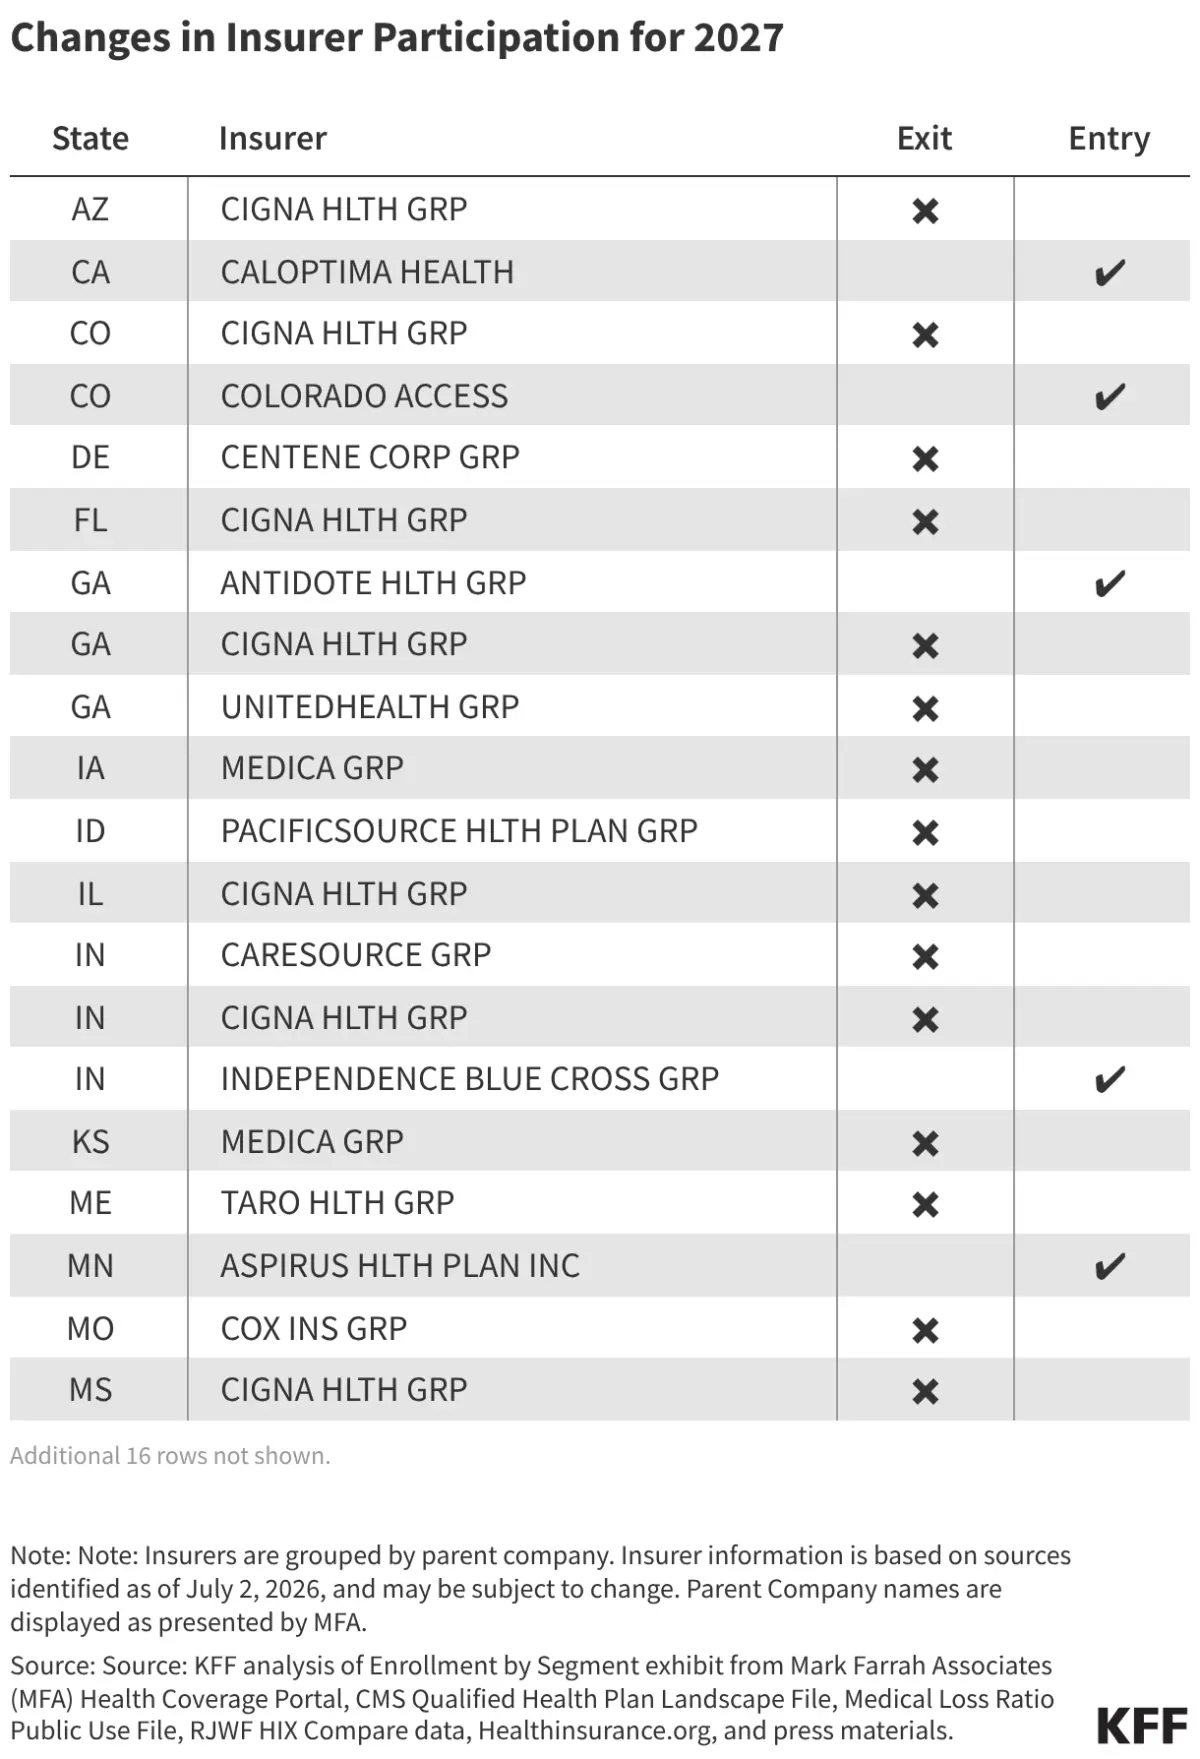
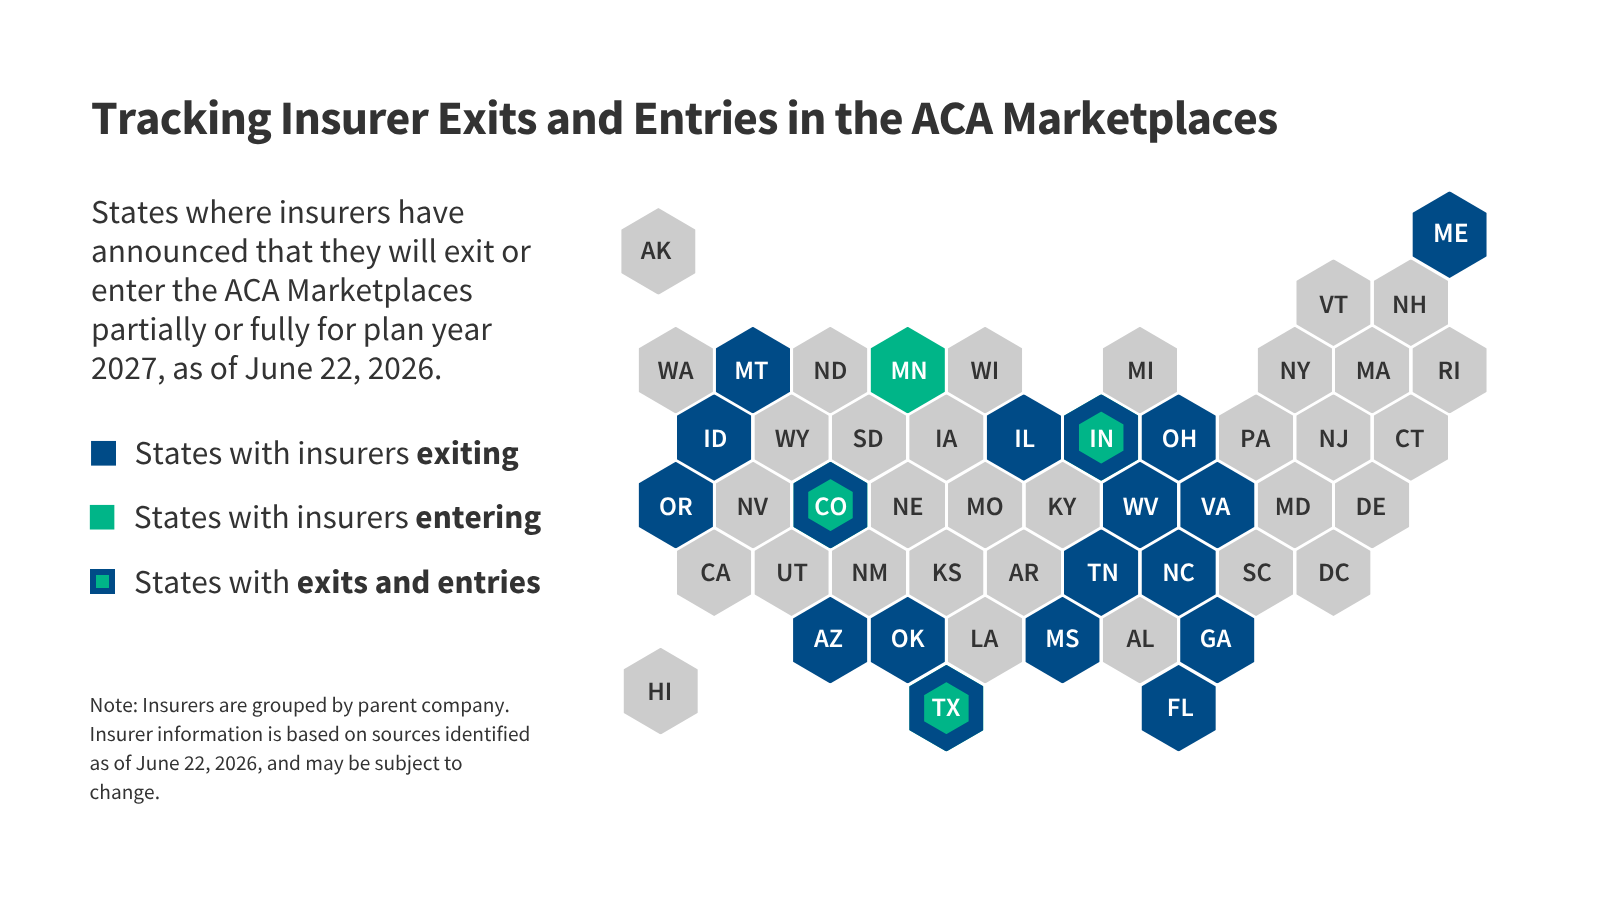
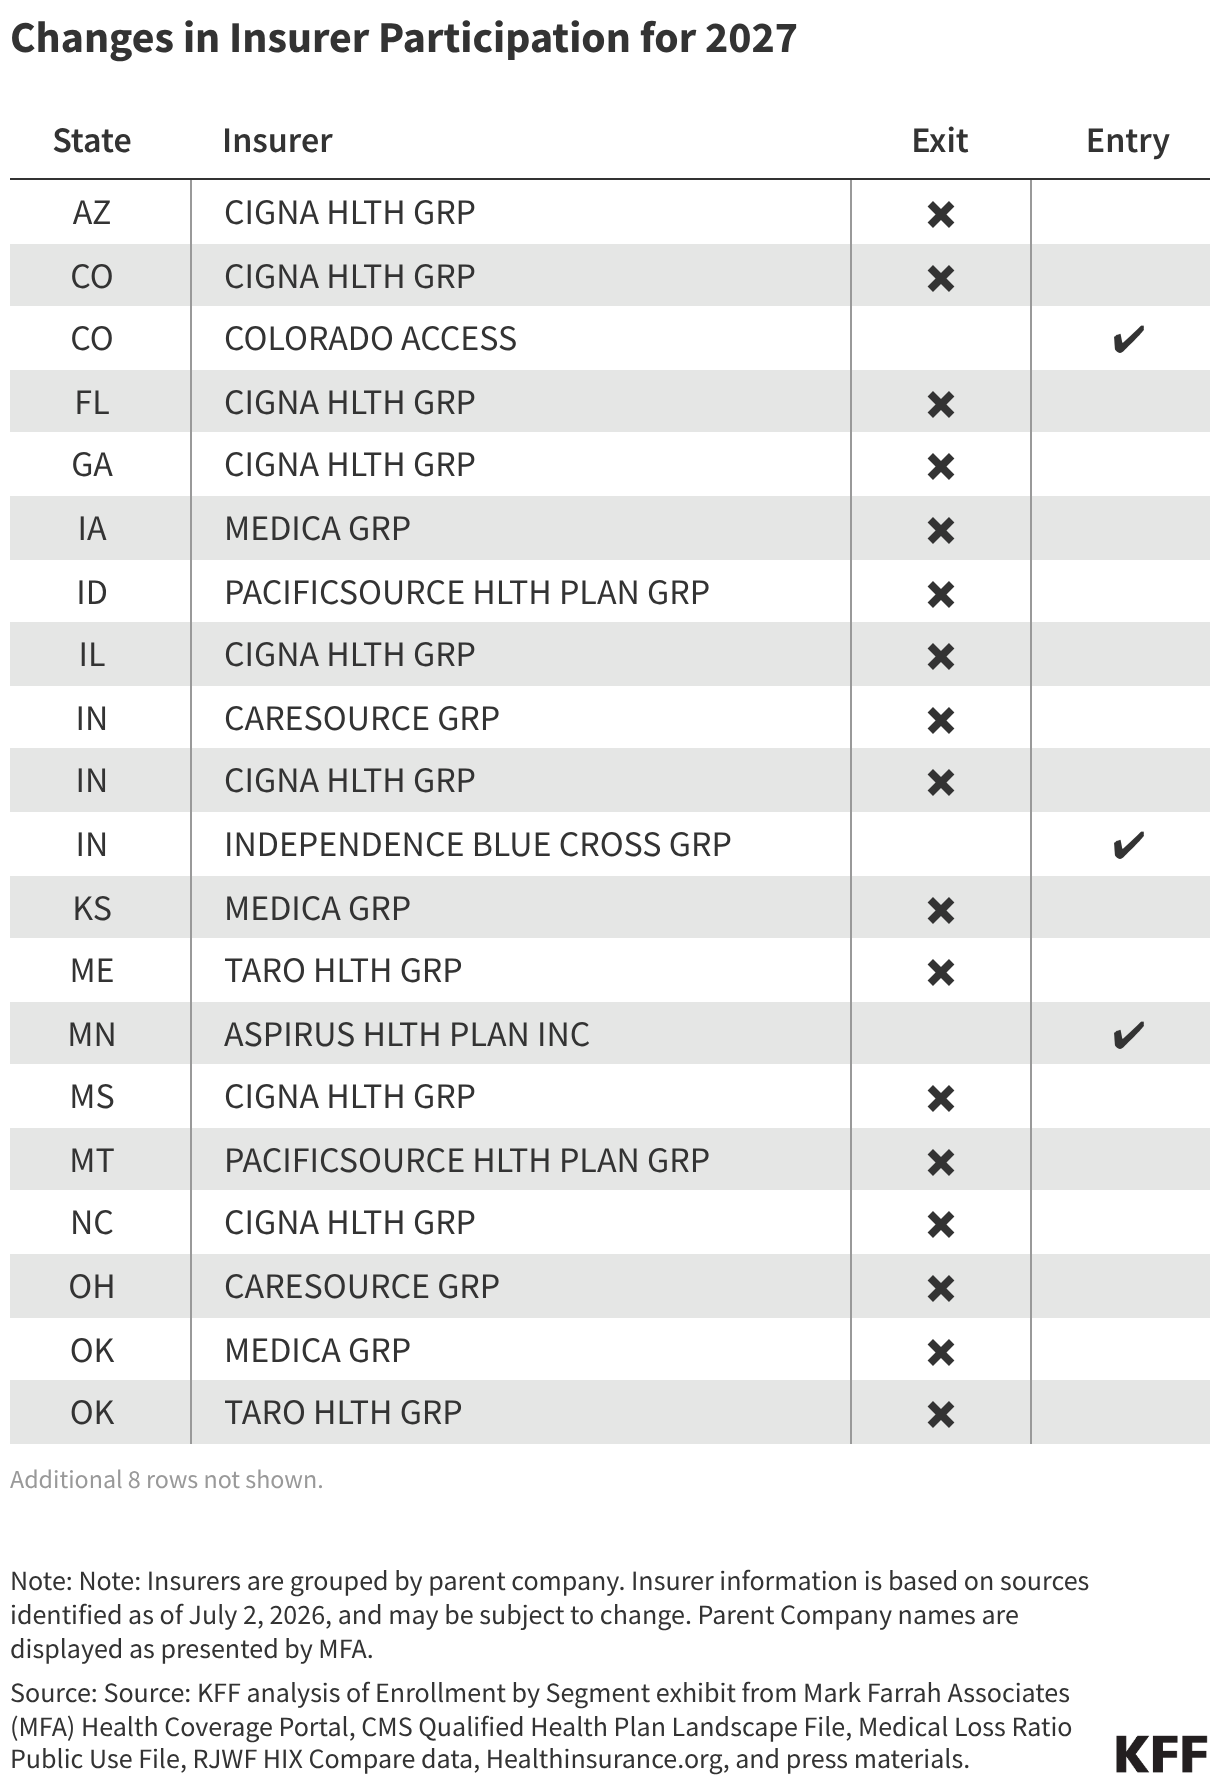
The landscape of the Affordable Care Act (ACA) Marketplaces is undergoing its most significant structural shift in recent years. As of October 7, 2026, the industry is bracing for a wave of instability: 11 insurance carriers have officially announced their intentions to exit the ACA Marketplace for the 2027 plan year, either in full or in specific geographic regions. While six carriers have signaled their intent to enter new state markets, the net sentiment across the insurance sector is one of consolidation and strategic withdrawal.
This pivot follows the seismic expiration of enhanced premium tax credits at the end of 2025. These subsidies had previously kept premiums artificially low and enrollment numbers at historic highs. With those supports removed, the market has begun to contract, fueling concerns about long-term sustainability, consumer choice, and the health of the individual insurance risk pool.
Main Facts: The 2027 Insurance Exodus
The latest data paints a picture of a market in flux. The decision by 11 carriers to pull back from the ACA exchange represents a direct response to a shrinking addressable market. When the enhanced tax credits expired, the immediate financial impact was a surge in premium costs for consumers, which subsequently triggered a decline in enrollment.
According to data from the 2026 Open Enrollment Period, plan selections fell by over a million compared to the previous year. Industry analysts predict that this decline is not a momentary blip but a sustained trend that will continue to erode the Marketplace membership base throughout 2027.
For the insurance companies, these enrollment declines are not merely statistical—they are existential. Smaller pools of enrollees often lead to increased volatility in risk pools, as healthier participants are more likely to drop coverage when premiums rise, leaving insurers to cover a disproportionately higher share of high-utilization, chronically ill patients.
Chronology of Market Shifts
To understand the current state of the Marketplace, one must look at the timeline of policy and corporate reactions:
- Late 2025: The sunsetting of enhanced premium tax credits creates immediate pricing pressure on the ACA individual market.
- Early 2026: Initial enrollment data reveals a significant drop in sign-ups, confirming industry fears that the market’s "sugar high" from federal subsidies is over.
- June 2026: KFF publishes the initial findings on the decline, highlighting the correlation between subsidy expiration and reduced plan selection.
- Summer 2026: Major carriers begin their annual rate-setting and market participation evaluations for the 2027 cycle.
- October 7, 2026: Current update confirms 11 carriers are exiting, while six new entrants are attempting to capture market share in specific, potentially underserved, regions.
This chronology underscores a "correction" phase. The market is attempting to recalibrate to a reality where federal support is lower, and the cost burden falls more heavily on the individual consumer.
Supporting Data and Trends
The financial viability of the ACA Marketplace is tied inextricably to the "size and shape" of the risk pool. When a carrier like Cigna—a major player in the industry—decides to exit the individual market, it serves as a bellwether for the broader sector.
The Cigna Case Study
Cigna’s decision to exit the individual market for 2027 is rooted in a fundamental mismatch between their growth targets and the realities of the ACA exchange. With over 350,000 on-exchange members reported in the first quarter of 2026, the company nevertheless deemed the segment to be "small business" with limited scalability.
In a statement reflecting the sentiments of many exiting carriers, Cigna indicated that the decision allows them to refocus resources on "core growth platforms." This suggests that for many large insurers, the ACA Marketplace is no longer viewed as a strategic growth engine but rather a low-margin, high-complexity environment that distracts from more profitable segments like Medicare Advantage or employer-sponsored plans.
Competitive Thinning
In several states, the exit of multiple carriers simultaneously is creating "choice deserts." When three or four insurers pull out of a specific state or county, the remaining carriers face significantly less competitive pressure. For consumers, this translates to:
- Higher premiums due to lack of competition.
- Narrower provider networks.
- Fewer plan design options that meet their specific health needs.
Official Responses and Strategic Rationales
The insurance industry’s response to the 2027 landscape is largely defensive. Executives are under pressure from shareholders to demonstrate fiscal discipline in a post-subsidy environment.
"The marketplace is currently undergoing a painful transition," says one senior healthcare analyst. "When you remove the financial cushion of tax credits, you expose the underlying cost-of-care issues that the ACA has struggled with since its inception. Insurers are simply reading the room."
Conversely, the six carriers entering new markets are often smaller, regional players or specialized health plans that operate on leaner cost structures. These companies may find success in niche markets where the "Big Five" insurers have retreated, betting that they can manage the risk pool more effectively through tighter care coordination and localized provider partnerships.
Implications: The Future of the ACA Marketplace
The implications of this market contraction are far-reaching, touching on policy, public health, and political discourse.
1. Risk Pool Degradation
As healthier individuals—often those with the most price-sensitive habits—drop their coverage, the remaining risk pool becomes "sicker." This creates a death-spiral risk, where insurers are forced to raise premiums to cover the high-cost patients, which in turn drives out the remaining healthy members.
2. The Political Lens
This shift is occurring against the backdrop of the 2026 Midterm Elections. Healthcare remains a top-tier issue for voters. The instability in the ACA Marketplace is expected to become a central talking point in campaign debates. Supporters of the ACA will argue that the instability is the direct result of "legislative negligence" in letting the subsidies expire, while opponents will argue that the market is finally reflecting the true, unsubsidized cost of healthcare, which they contend is unsustainable under the current regulatory framework.
3. Consumer Protection and Access
The most vulnerable group in this scenario is the middle-income demographic—those who earn too much to qualify for significant remaining subsidies but not enough to easily absorb the sharp increases in premiums. These consumers are at risk of becoming "uninsured by price," a category that could grow significantly if more carriers continue to exit in 2028 and beyond.
4. The Potential for Federal Intervention
If the exodus of 2027 proves to be a trend rather than a one-time correction, policy analysts anticipate that lawmakers will be forced to revisit the subsidy structure. Whether the solution involves a permanent extension of tax credits, a reform of the Essential Health Benefits (EHB) requirements to lower premiums, or a push toward a "public option" to fill the gaps left by private carriers, the status quo is clearly under extreme duress.
Conclusion
The 2027 ACA Marketplace will be defined by its smaller, more fragmented footprint. While the market is not collapsing, it is undeniably shrinking. For consumers, the coming year will require increased diligence during open enrollment, as the departure of established carriers will necessitate a thorough review of remaining plan options, provider networks, and cost structures.
For the healthcare industry, the path forward is uncertain. The era of rapid expansion for the ACA is over, replaced by a period of strategic retreat and financial caution. How the government responds to this contraction—and whether it chooses to bolster the market or allow it to find a new, smaller equilibrium—will define the trajectory of American healthcare policy for the remainder of the decade.
About the Author