Editorial Note: This report was updated on September 29, 2026, to incorporate the latest polling data from KFF, providing a contemporary lens on an issue that has remained a persistent challenge for U.S. households since the original publication in December 2021.
For millions of Americans, the promise of quality healthcare is frequently overshadowed by the crushing weight of its price tag. Recent polling data underscores a sobering reality: for the average U.S. family, healthcare costs are not merely a line item in a budget—they are a primary source of economic anxiety, a barrier to essential medical services, and a leading cause of long-term financial instability. Despite various policy shifts and legislative interventions, the burden of medical expenses remains the top financial worry for adults across the nation, transcending socioeconomic status, geographic location, and partisan affiliation.
The Architecture of Financial Anxiety
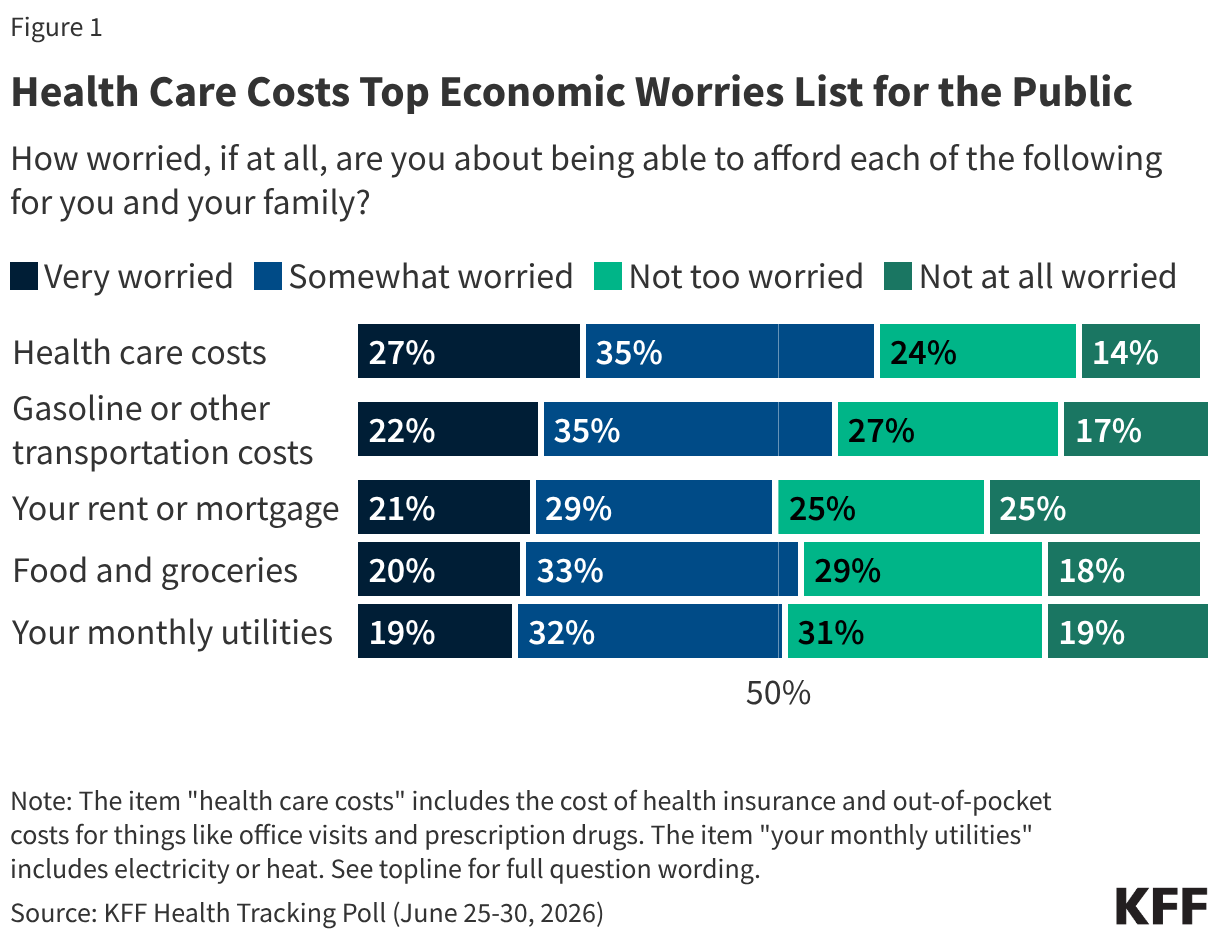
Throughout 2026, economic sentiment has been dominated by the escalating costs of basic necessities. However, data indicates that healthcare consistently sits at the apex of the public’s financial dread. Approximately six in ten adults report feeling either "very" (27%) or "somewhat" (35%) worried about their ability to afford medical care, including health insurance premiums and out-of-pocket costs for office visits and prescription medications.
This level of anxiety significantly outstrips concerns regarding other household expenditures. For instance, roughly one in five adults expresses "very" high levels of concern regarding gasoline, transportation, rent, mortgage payments, groceries, or utilities. The ubiquity of this concern is striking: while 87% of uninsured adults under age 65 express significant worry, a surprising 64% of those with insurance coverage also report persistent anxiety regarding medical affordability. This data suggests that even for the "protected" population, insurance is often insufficient to insulate families from the volatility of healthcare pricing.
A Chronology of Declining Affordability
The trajectory of medical affordability has shown little improvement over the past five years. Since the initial KFF analysis in 2021, the narrative has shifted from one of sporadic hardship to systemic crisis.
- December 2021: The initial reporting highlighted the emergence of widespread medical debt, exacerbated by the COVID-19 pandemic and systemic gaps in coverage.
- February–March 2022: The KFF Health Care Debt Survey revealed that 41% of U.S. adults held some form of medical or dental debt, laying bare the fragility of household finances.
- July 2023: Public concern regarding prescription drug costs reached a new zenith, prompting increased scrutiny on pharmaceutical pricing transparency.
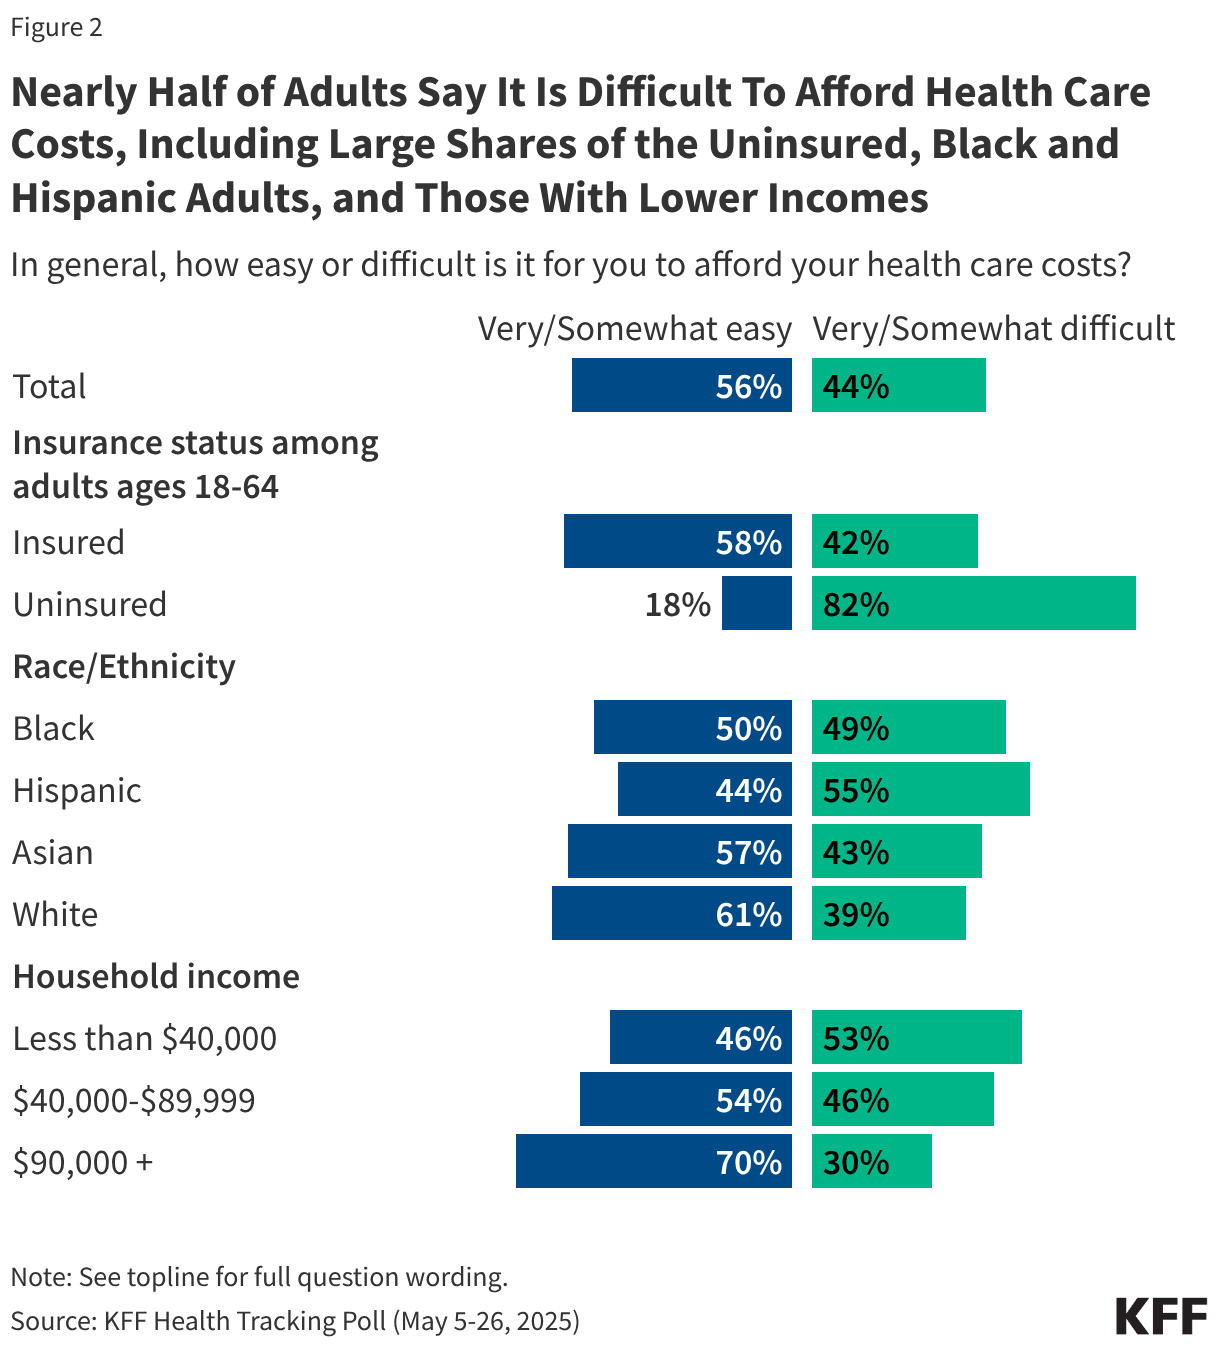
- May 2025: Polling indicated that the difficulty in affording care had become a majority concern among marginalized groups, with 55% of Hispanic adults and 49% of Black adults reporting significant obstacles to accessing care.
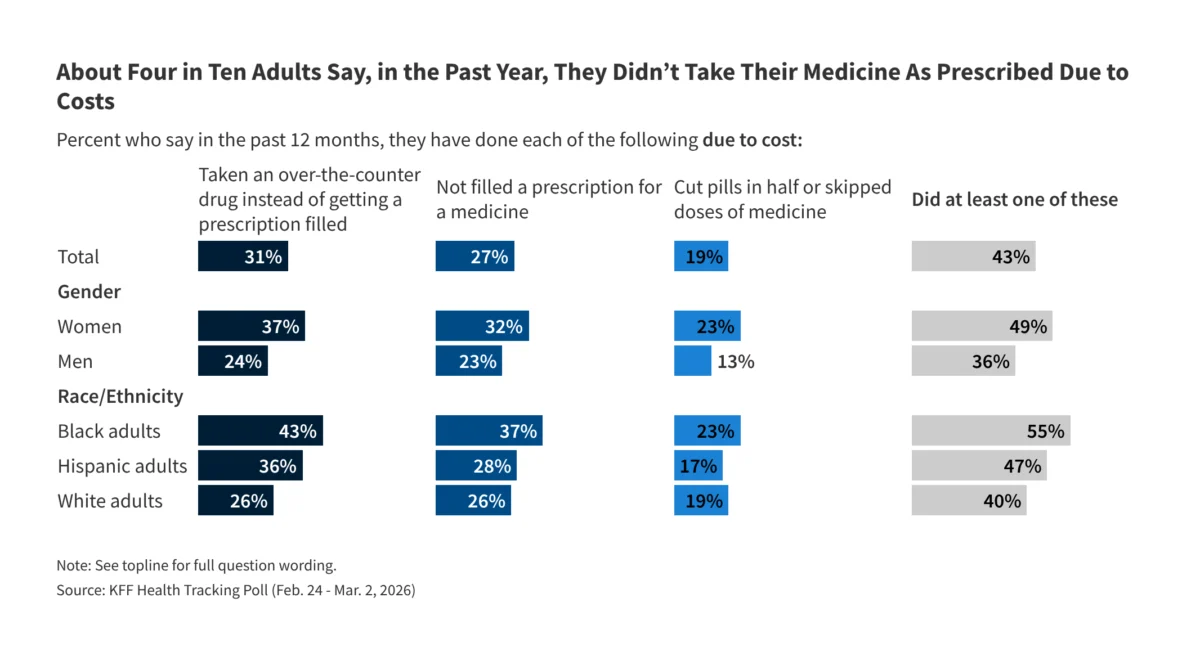
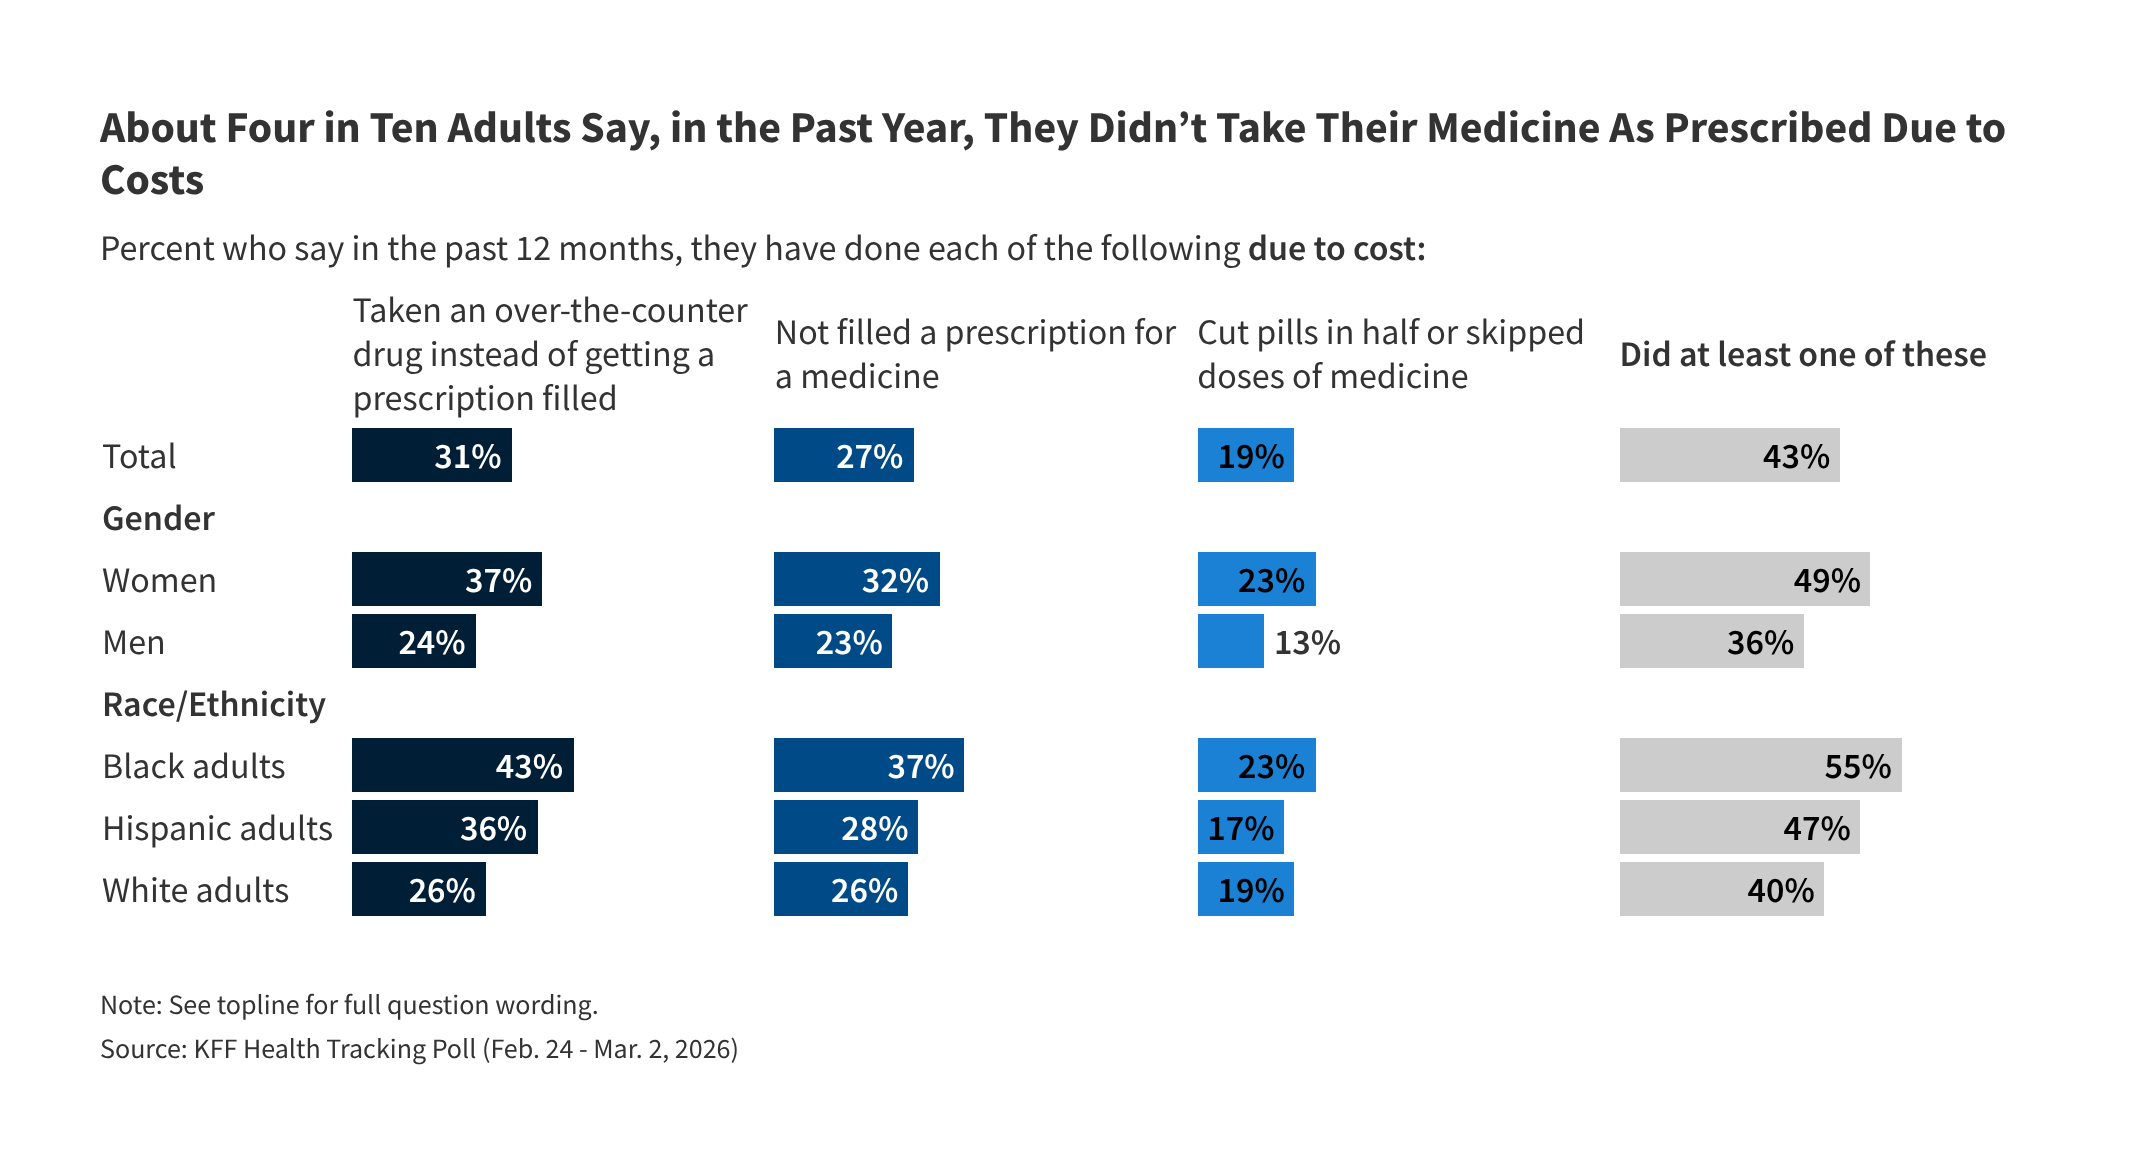
- March 2026: New data revealed that 43% of adults had resorted to "cost-saving" measures—such as skipping doses or opting for over-the-counter alternatives—to cope with prescription costs, marking a dangerous upward trend from previous years.
Supporting Data: The Ripple Effects of High Costs
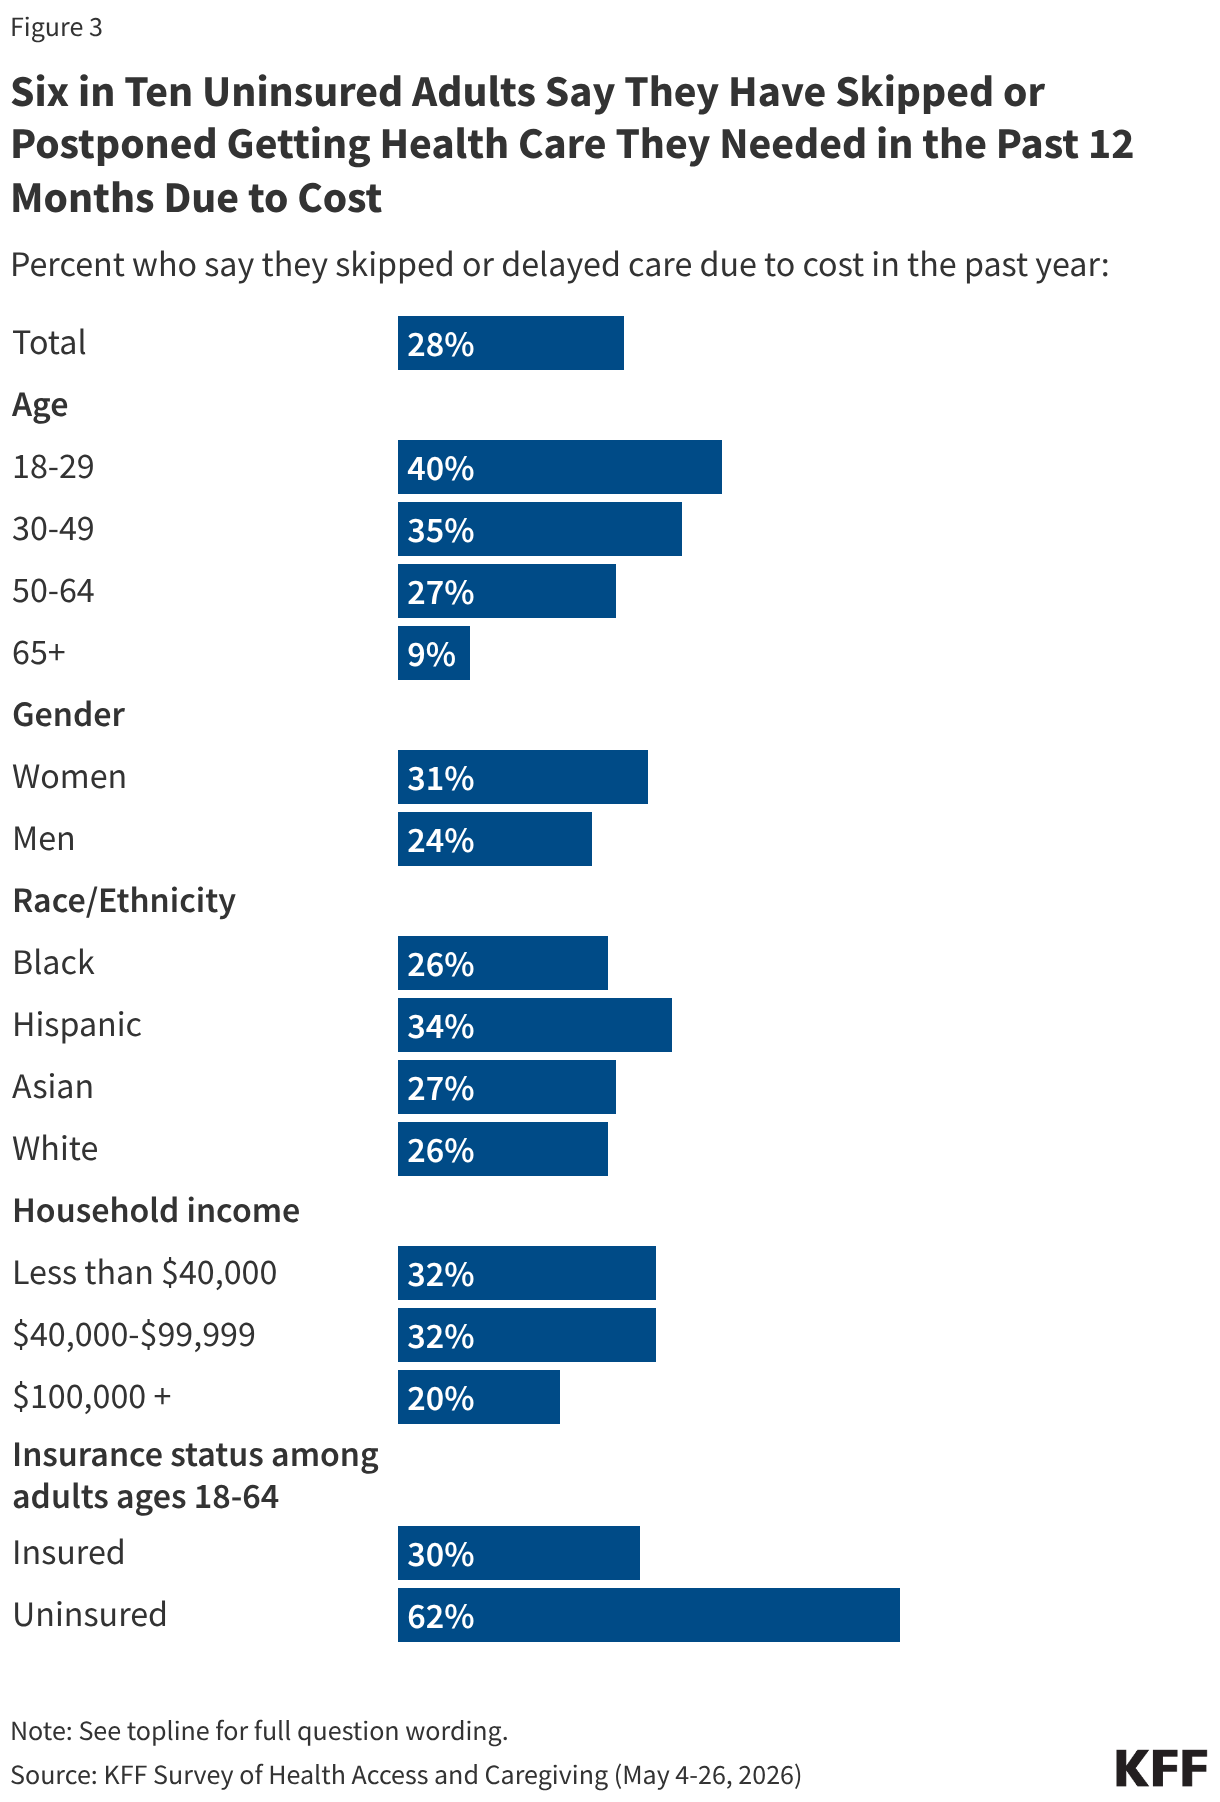
The implications of these costs are not limited to mental stress; they manifest as tangible public health failures. Roughly 28% of U.S. adults report having skipped or postponed needed medical care within the last 12 months due to financial constraints.
The Impact on Vulnerable Populations
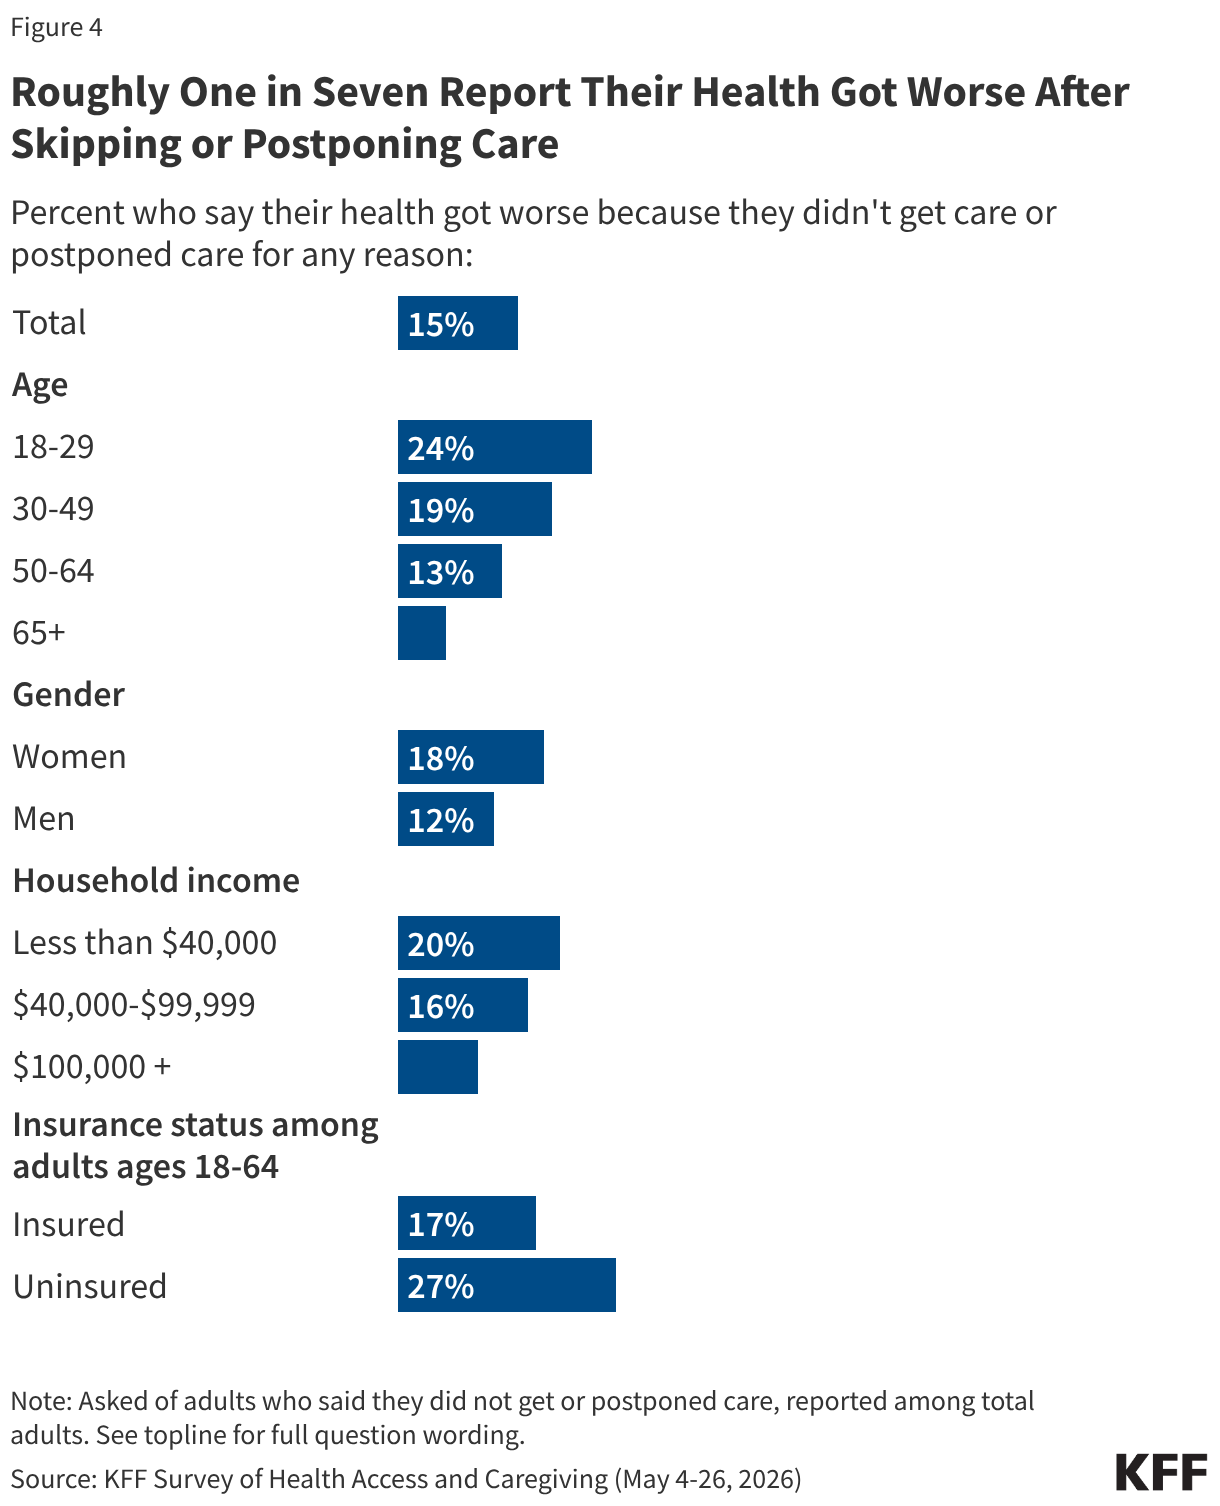
The burden is not distributed equally. Women, younger adults, and those from lower-income households are disproportionately represented among those delaying care. Furthermore, the correlation between delayed care and worsening health outcomes is undeniable. Among adults under age 65, those without insurance are significantly more likely to report that their health deteriorated as a result of deferred care (27% vs. 17% for the insured).
Perhaps most concerning is the data regarding the youth demographic. Adults under age 30 are four times as likely as those over 65 to report that their health worsened due to skipped care. This is largely attributed to the robust protection afforded by Medicare for the older cohort, suggesting that universal, comprehensive coverage is the most effective tool in mitigating health decline.
The Prescription Drug Dilemma
Pharmaceutical affordability represents a distinct sub-crisis. Nearly one-third of adults (31%) have chosen an over-the-counter medication over a prescribed one, while 27% have simply opted not to fill a prescription entirely. This behavior is increasingly common in middle-income households, proving that the affordability crisis has migrated well beyond the poverty line. In households earning between $40,000 and $90,000, nearly half report taking some form of cost-saving action regarding their medications.
Institutional and Official Perspectives
The healthcare industry and policymakers often point to the complexity of insurance structures as a primary hurdle. KFF’s Survey of Consumer Experiences with Health Insurance highlights a stark divide in satisfaction. While the majority of insured adults view their plans favorably regarding prescription coverage and co-pays, a persistent minority—roughly 30%—rate their coverage as "fair" or "poor."
Private insurance enrollees, particularly those in employer-sponsored plans or Marketplace tiers, report higher levels of dissatisfaction with premiums and out-of-pocket costs compared to those on Medicaid. Medicaid, which generally minimizes premiums and restricts co-pays, consistently receives the highest marks for affordability. This data serves as a compelling argument for those advocating for expanded public coverage as a mechanism to stabilize consumer finances.
Implications for the Future: Debt and Long-Term Care
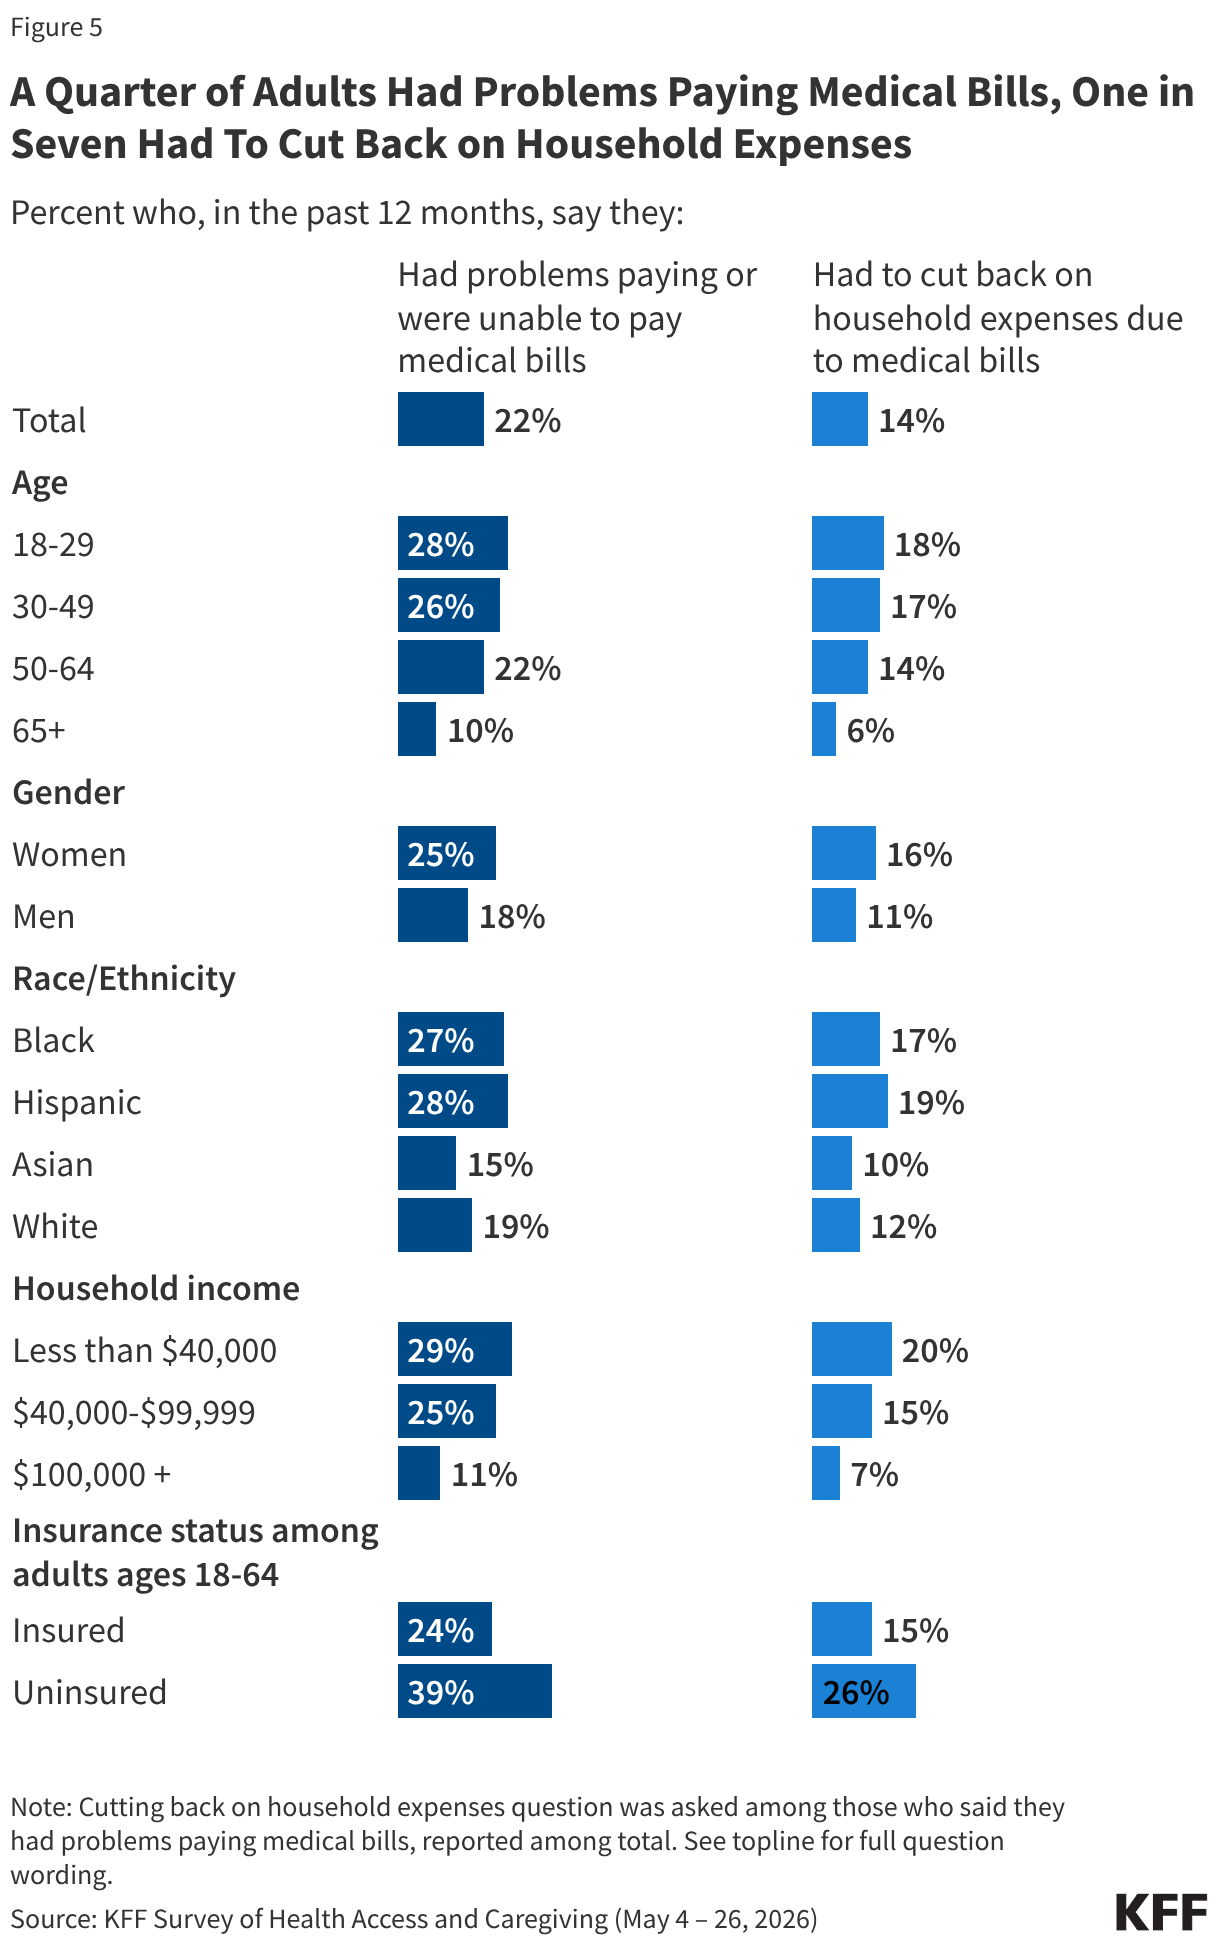
The long-term implications of current healthcare pricing extend into the realm of permanent debt. The 2022 Diagnosis Debt project revealed that 24% of adults have medical bills that are past due, and 17% have taken out loans or utilized credit cards specifically to manage medical debt.
The $500 Threshold
One of the most alarming metrics is the "unexpected bill" threshold. Nearly half of all U.S. adults (roughly 50%) stated they would be unable to pay an unexpected $500 medical expense without incurring debt or simply being unable to cover it. This indicates that a single minor medical emergency is enough to catalyze a downward financial spiral for millions of families.
The Long-Term Care Crisis
Looking toward the future, the demographic shift toward an aging population creates a new frontier of anxiety: long-term care. More than seven in ten adults between the ages of 50 and 64 express significant concern about affording nursing homes or assisted living facilities. As the "Silver Tsunami" approaches, the lack of a national strategy for affordable, long-term care support looms as a massive, unresolved economic threat.
Conclusion: A System at a Crossroads
The evidence provided by years of KFF polling paints a clear picture: the American healthcare system is failing to provide financial security. When citizens are forced to choose between groceries and medication, or when they postpone life-saving treatments due to the threat of debt, the system is no longer functioning as a service, but as a barrier.
The data suggests that affordability is not merely a matter of insurance coverage—it is a matter of the depth of that coverage, the rising cost of pharmaceutical goods, and the absence of a safety net capable of catching those faced with unexpected health events. As the country moves into the latter half of the decade, the demand for structural reform—focused on price transparency, pharmaceutical regulation, and the protection of vulnerable, high-need populations—will undoubtedly remain the central pillar of the national health policy debate.
About the Author