In the landscape of modern corporate innovation, the traditional boundaries between Silicon Valley and the pharmaceutical industry are rapidly dissolving. For decades, Big Pharma held a monopoly on the high-stakes, capital-intensive world of drug discovery. Today, that hierarchy is being challenged by a new class of research powerhouses: the technology giants.
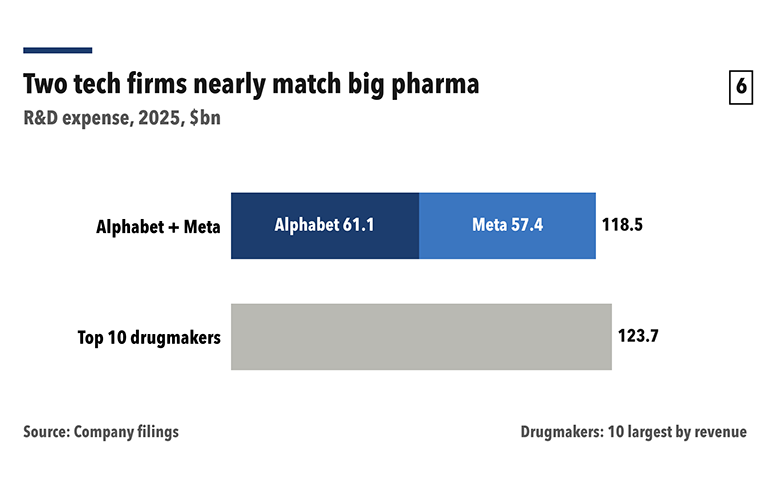
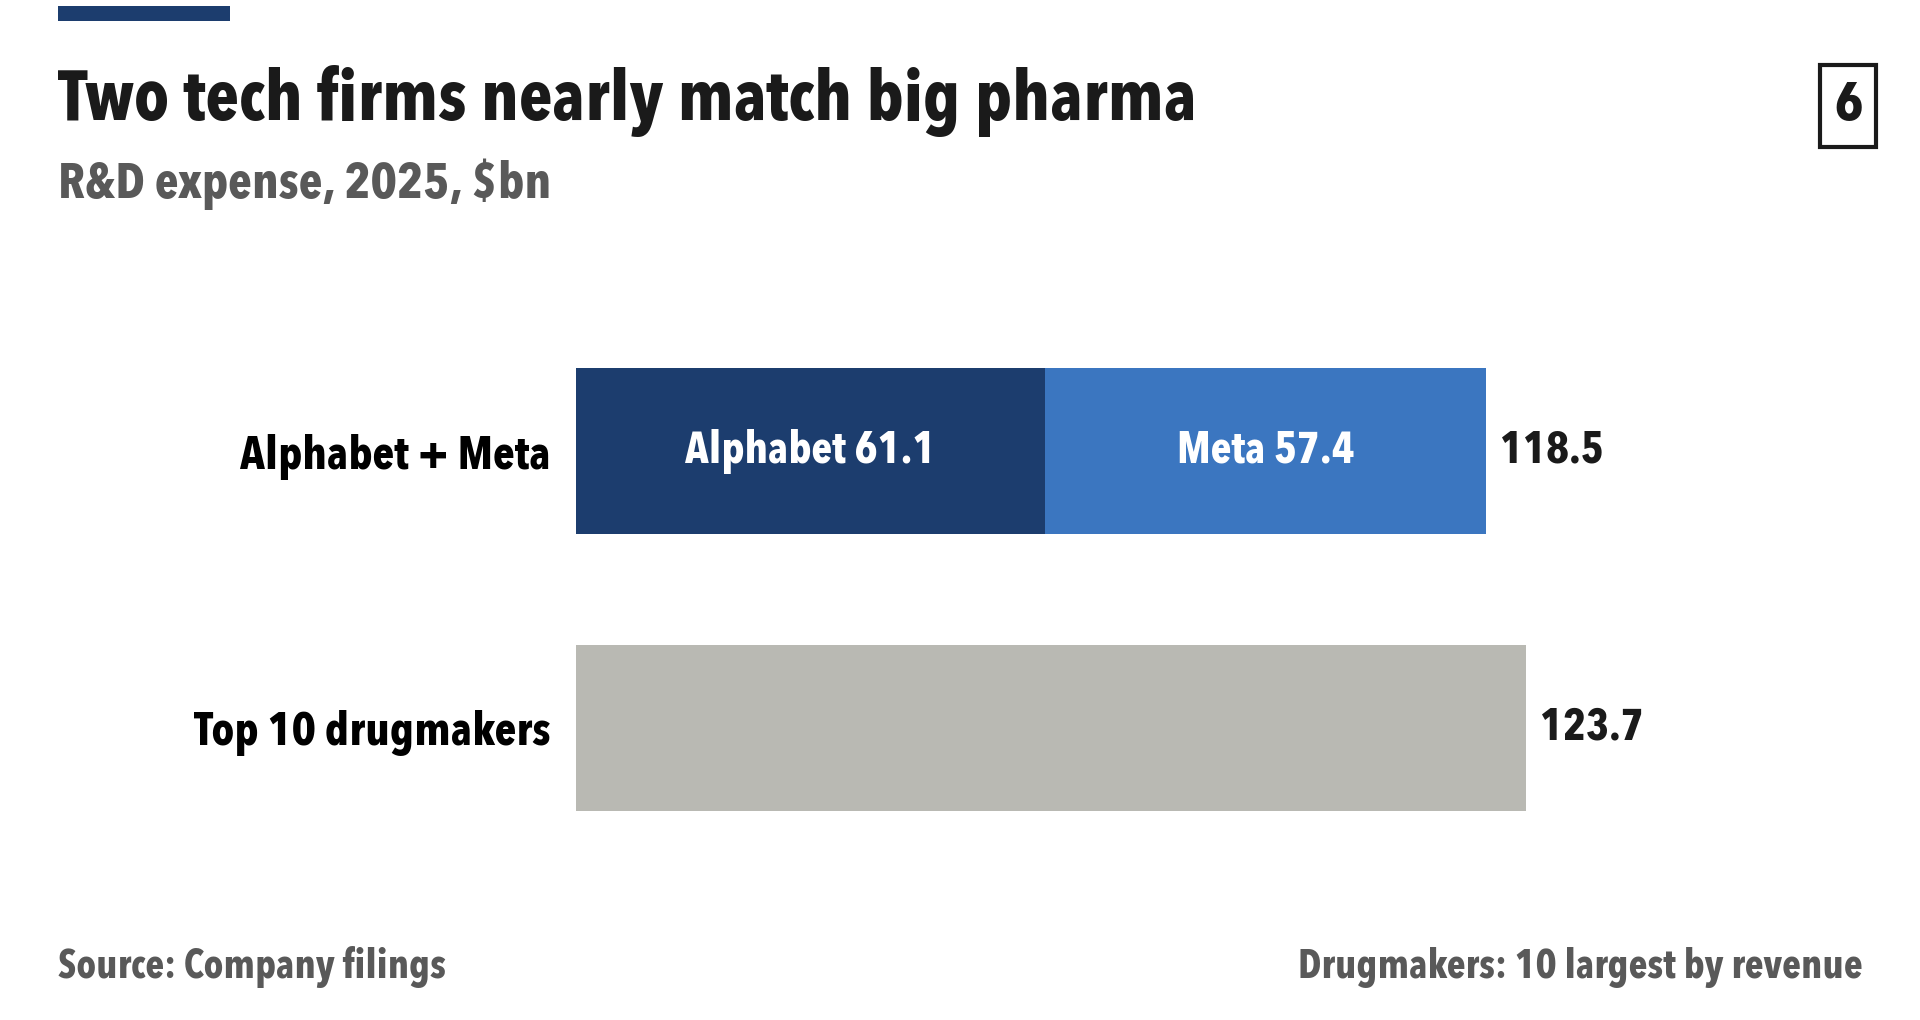
According to recent data, Google parent Alphabet and Meta reported a combined $118.5 billion in research and development (R&D) expenditure for 2025. This staggering figure is rapidly closing the gap with the world’s ten largest drugmakers, whose combined R&D budget sits at $123.7 billion—a figure that, notably, includes significant investments in medtech and diagnostics. This shift is not merely a matter of capital allocation; it represents a fundamental migration of the "knowledge factory" from the chemistry lab to the cloud-native supercomputer.
The Financial Shift: A Tale of Two Budgets
To understand the magnitude of this pivot, one must look at the trajectory of individual companies. In 2013, Merck & Co. and Google were essentially peer entities in the research space; Merck’s R&D spend of $7.5 billion slightly edged out Google’s $7.1 billion. By 2025, that parity had evaporated. Alphabet’s R&D spend surged to $61.1 billion, nearly four times the $15.8 billion invested by Merck.
This financial divergence tells a clear story: Big Tech is betting that its core competency—processing massive datasets with artificial intelligence—can solve the "productivity crisis" that has long plagued pharmaceutical R&D. For drugmakers, the challenge is no longer just about discovering new molecules; it is about scaling the computational infrastructure required to analyze them.
Chronology of Convergence: From Collaboration to Integration
The integration of tech into life sciences has accelerated significantly over the last 24 months, moving from superficial software licensing to deep, infrastructure-level partnerships.
- January 2026: Eli Lilly and NVIDIA announce a co-innovation lab in the Bay Area, backed by $1 billion over five years. Simultaneously, Genmab begins building custom, Claude-powered agents to streamline clinical development.
- February 2026: Lilly’s "LillyPod" supercomputer, built in partnership with NVIDIA, goes live in Indianapolis.
- March 2026: Roche signals a massive hardware expansion, announcing the installation of 2,176 Blackwell GPUs on-premises, pushing its total compute capacity above 3,500 units.
- April 2026: Merck & Co. cements its digital transformation with a multi-year alliance with Google Cloud, valued at up to $1 billion. Meanwhile, OpenAI launches "GPT-Rosalind," a specialized life sciences model, with Amgen and Moderna as early adopters.
- May 2026: Isomorphic Labs raises $2.1 billion to expand its AI-driven drug discovery efforts. Bristol Myers Squibb announces a strategic rollout of "Claude Enterprise" to over 30,000 employees.
- September 2026: Anthropic confirms the establishment of a physical biology "wet lab" in the San Francisco Bay Area, signaling a move toward in-house experimentation. Novo Nordisk signs a major drug-discovery collaboration with Anthropic, its third major AI partnership of the year.
The Rise of the AI Factory
The term "AI Factory" has become the industry standard for describing the new R&D facilities emerging across the life sciences sector. Bristol Myers Squibb is currently constructing its second NVIDIA-based supercomputer, building upon the operational success of its first DGX SuperPOD. These machines are not merely tools; they are the new engines of discovery.
At Eli Lilly, the results are already being realized. Chief AI Officer Thomas Fuchs has reported that the company’s supercomputer—running NVIDIA’s 550-billion-parameter Nemotron 3 Ultra model—has successfully co-designed a small-molecule candidate featuring a novel chemical fragment. With "no token or budget limits," the system represents a departure from the traditional, iterative, and often failed laboratory cycles of the past.
Anthropic: The New Frontier of Biological Intelligence
Perhaps the most significant development in 2026 is the blurring of the line between software providers and biotech companies. Anthropic, traditionally viewed as a frontier AI lab, has moved aggressively into the life sciences sector. By acquiring Coefficient Bio—a startup founded by former Genentech computational biologists—for $400 million, and by establishing its own wet lab for physical biology experiments, the company is positioning itself as a vertically integrated participant in drug development.
While Anthropic has publicly stated that its lab is not currently aimed at clinical drug discovery, the implications are clear: the future of AI in pharma will not be confined to software. By bridging the gap between digital models and physical validation, Anthropic is mirroring the strategy of tech giants who control their own hardware, software, and data pipelines.
Supporting Data and Industry Implications
The following data points highlight the depth of this transformation:
- Compute Capacity: Major firms like Roche have moved beyond cloud-only strategies, opting for massive on-premises GPU deployments to maintain sovereignty over sensitive R&D data.
- Enterprise Adoption: The adoption of large language models (LLMs) has reached an enterprise scale. Bristol Myers Squibb’s deployment of Claude to 30,000 employees suggests that AI is being treated as a foundational "operating system" for the entire corporate structure, from manufacturing to commercial strategy.
- Capital Flow: The $2.1 billion funding round for Isomorphic Labs and the $1 billion investments from Merck and Lilly underscore that top-tier pharma is willing to pay a premium for "compute-first" discovery platforms.
The Challenges Ahead: Clinical Realities
Despite the optimism surrounding generative AI and supercomputing, the industry faces significant hurdles. Isomorphic Labs, for instance, has pushed back its target for reaching the clinical stage to the end of 2026. This serves as a sober reminder that while AI can accelerate the design of a molecule, it cannot accelerate the biology of a human patient.
Furthermore, competition concerns remain a primary barrier. Anthropic has noted that it is holding off on its own clinical trials partly to avoid direct competition with its pharmaceutical partners—a delicate balancing act that all tech firms in this space must navigate.
The Future of the "Pharma-Tech" Hybrid
As we look toward 2027 and beyond, the definition of a "pharmaceutical company" is likely to evolve. We are moving toward a model where the most successful drugmakers will look more like technology conglomerates, and the most successful tech companies will be those that have successfully "wet-lab-enabled" their AI models.
The implications for the broader healthcare ecosystem are profound. If AI can truly reduce the time and cost of drug development, we may see a resurgence in interest for "neglected" disease areas—conditions that were previously deemed financially unattractive due to the high cost of traditional R&D. Companies like Anthropic have already begun signaling an intent to tackle these areas, potentially democratizing access to discovery platforms that were once the exclusive domain of global pharmaceutical giants.
Conclusion
The marriage of Big Tech and Big Pharma is no longer a trend; it is the new reality of the life sciences industry. With R&D budgets at the tech giants now rivaling those of the drugmakers, the race is on to see who can best harness the power of generative AI and supercomputing to crack the code of human biology. While the digital tools are revolutionary, the ultimate measure of success will remain the same as it has for the last century: the ability to safely and effectively deliver life-saving medicines to patients in need. The companies that master the integration of these two worlds—silicon and serum—will define the next era of medicine.
About the Author