For millions of Americans, the cost of health insurance remains one of the most significant line items in the household budget. As medical inflation continues to impact the broader economy, the financial architecture provided by the Affordable Care Act (ACA) serves as a critical safety net. By providing sliding-scale subsidies and cost-sharing protections, the ACA ensures that coverage remains accessible for those with low to moderate incomes.
As we look toward the 2027 coverage year, understanding the nuances of these financial mechanisms—premium tax credits and cost-sharing reductions—is more essential than ever for consumers navigating the federal and state-based Health Insurance Marketplaces.
Main Facts: How ACA Financial Assistance Works
The ACA’s financial assistance framework is bifurcated into two primary categories designed to address different aspects of healthcare affordability.
1. Premium Tax Credits (PTCs)
The premium tax credit is designed to lower the monthly "sticker price" of health insurance. These credits are tied to the cost of a "benchmark" plan—the second-lowest-cost silver plan available in an enrollee’s specific geographic area. The amount of the credit is determined by household income: as income rises, the required contribution from the consumer increases, and the tax credit decreases.
2. Cost-Sharing Reductions (CSRs)
While PTCs manage monthly premiums, CSRs manage the "hidden" costs of healthcare. These reductions lower the amount an enrollee pays out-of-pocket (OOP) when they actually access medical services, such as deductibles, copayments, and coinsurance. Critically, CSRs are only available to those who select a silver-level plan, creating a unique incentive for lower-income enrollees to choose these specific middle-tier options.
Chronology: The Evolution of ACA Subsidies
The landscape of federal health subsidies has undergone significant shifts in recent years, reflecting changing legislative priorities and economic conditions.
- 2010–2020: The original ACA framework established the foundational structure of premium tax credits for individuals between 100% and 400% of the Federal Poverty Level (FPL).
- 2021 (The American Rescue Plan Act): In response to the COVID-19 pandemic, Congress introduced "enhanced" subsidies. This policy expanded eligibility to individuals earning above 400% FPL and eliminated premiums for the lowest-income earners.
- 2022–2025 (The Inflation Reduction Act): The enhanced subsidies were extended, maintaining the 8.5% of income cap on premiums for those earning above 400% FPL, providing significant stability for middle-income families.
- 2026 (Expiration of Enhanced Subsidies): The expiration of the enhanced tax credits at the end of 2025 marked a major turning point. The return to pre-2021 subsidy levels resulted in a 58% increase in average premium payments and a 37% rise in average deductibles as consumers adjusted to higher out-of-pocket requirements.
- 2027 (Current Policy): The 2025 federal budget reconciliation act ("The One Big Beautiful Bill Act") introduced new requirements for the reconciliation of tax credits, removing previous repayment caps for consumers who underestimate their income.
Supporting Data: Understanding Eligibility and Cost
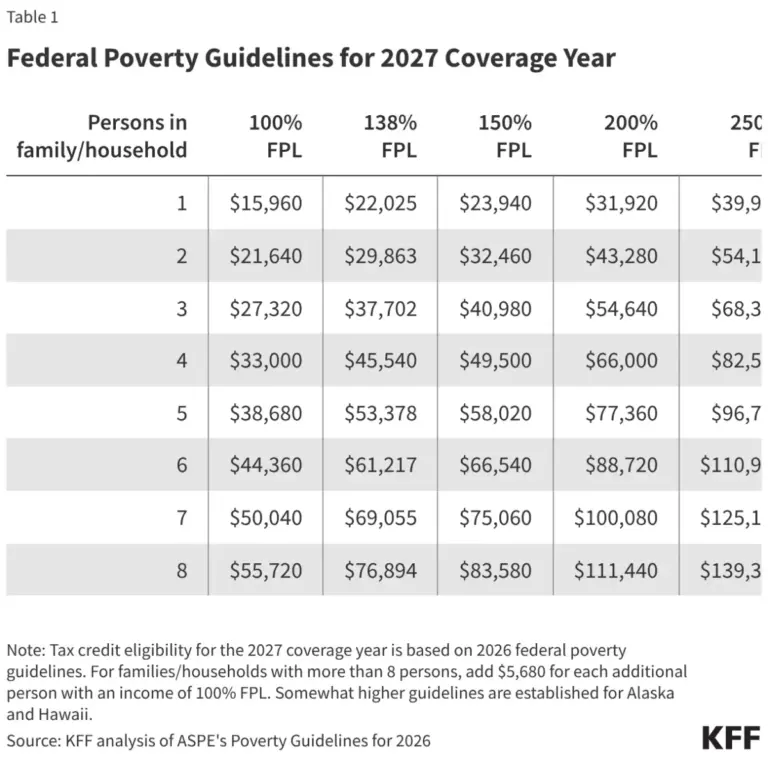
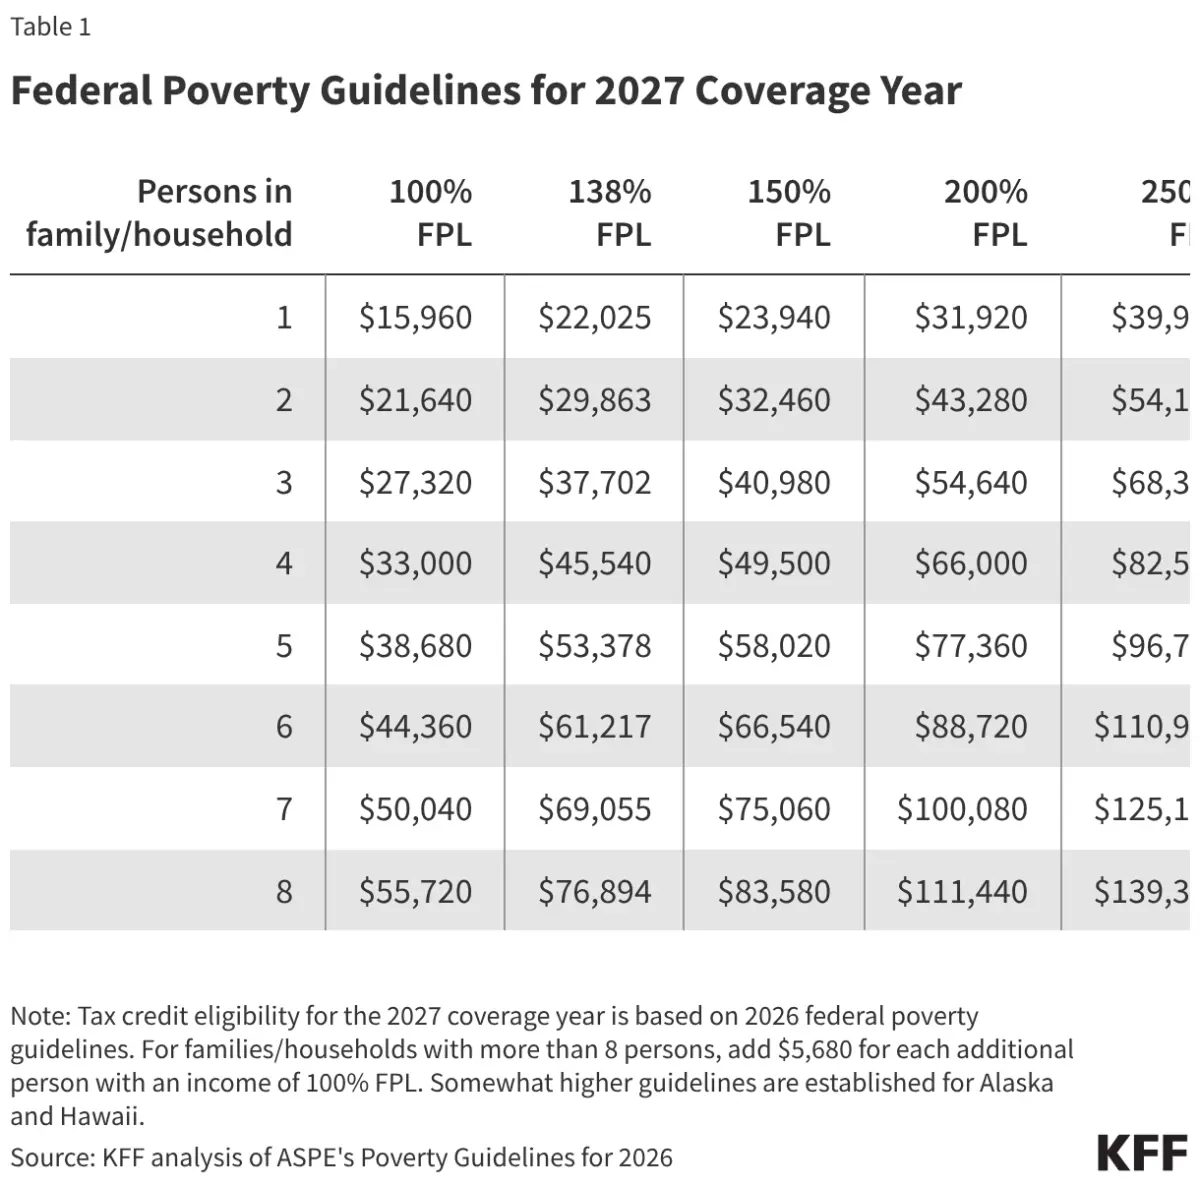
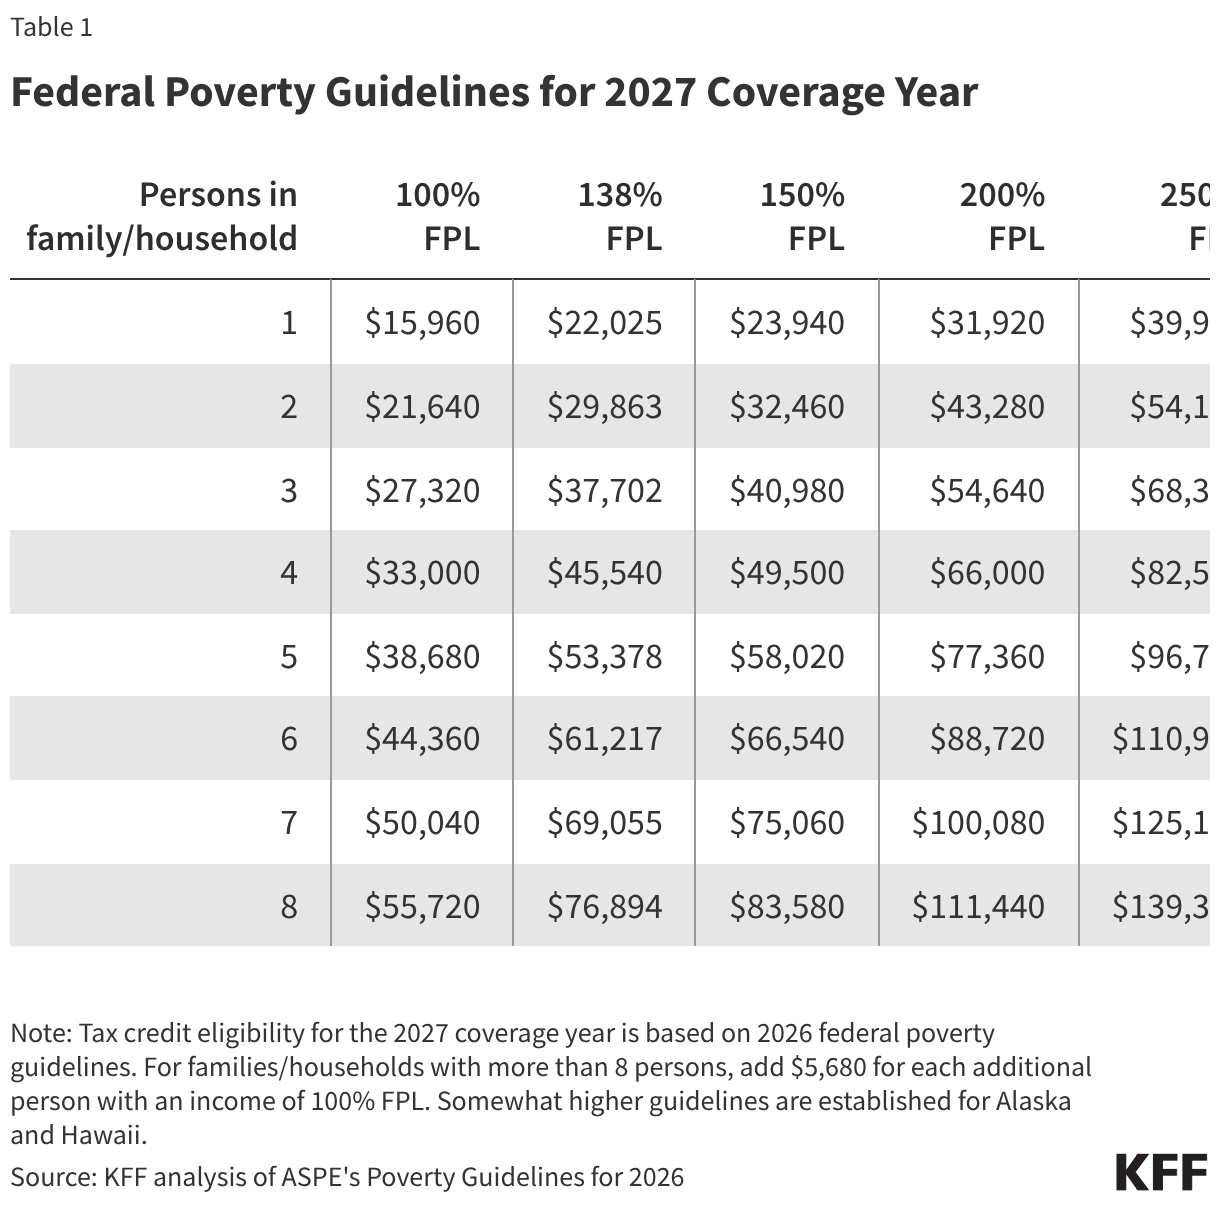
The math behind the 2027 marketplace is precise. Eligibility is determined primarily through Modified Adjusted Gross Income (MAGI) and proximity to the Federal Poverty Guidelines.
The Role of Employer Coverage
A common misconception is that those with employer-sponsored insurance are automatically ineligible for marketplace assistance. However, if an employer’s plan fails the "affordability test"—meaning the employee contribution for self-only coverage exceeds 10.22% of household income—the employee may qualify for marketplace subsidies. Furthermore, plans must meet "minimum value" standards, covering at least 60% of total allowed costs for covered benefits.
Immigration and the 2027 Threshold
Beginning in 2027, eligibility criteria regarding immigration status have been tightened. Only specific categories, such as Lawful Permanent Residents, Cuban/Haitian entrants, and COFA migrants, remain eligible for premium tax credits. Notably, DACA recipients remain ineligible for both marketplace subsidies and non-emergency Medicaid, highlighting a persistent gap in coverage for certain immigrant populations.
The "Benchmark" Calculation
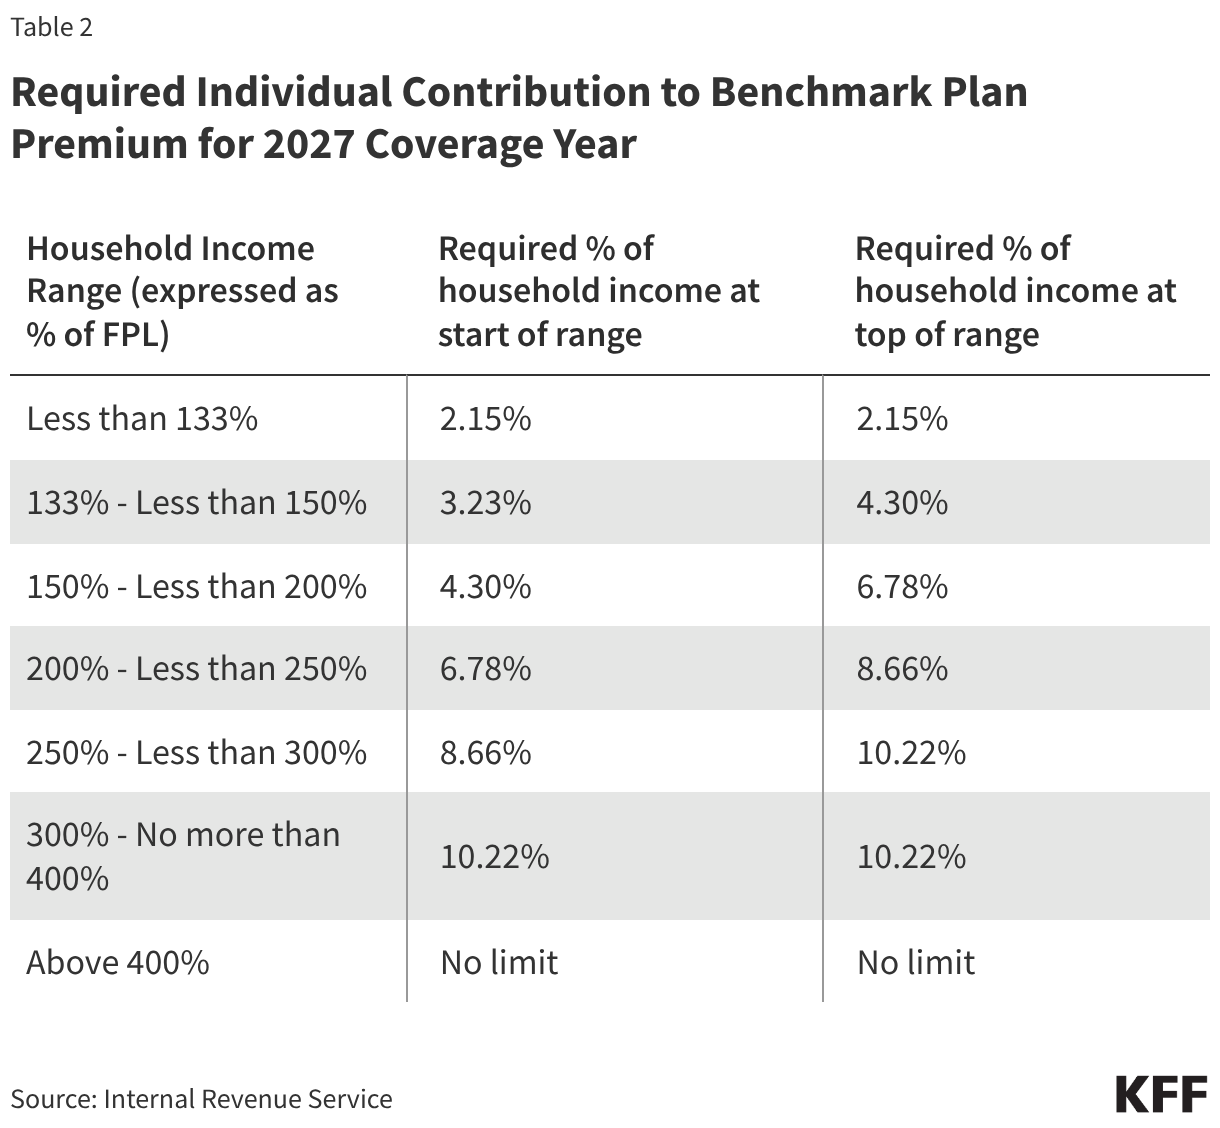
The premium tax credit is calculated by subtracting the required individual contribution from the cost of the benchmark plan. For instance, in 2027, an individual at 133% FPL is expected to contribute only 2.15% of their income toward their premium. At 300% to 400% FPL, that requirement rises to 10.22%. If an individual selects a plan more expensive than the benchmark, they must pay the difference; if they select a cheaper plan, the credit may reduce their premium to zero.
Official Responses and Regulatory Guidance
Government oversight agencies, including the IRS and the Centers for Medicare & Medicaid Services (CMS), have clarified the protocols for the 2027 plan year to ensure fiscal accountability.
The Reconciliation Requirement
The elimination of repayment caps for excess Advance Premium Tax Credits (APTC) is perhaps the most significant administrative change. Previously, if a consumer underestimated their income, there were limits on how much they had to repay the IRS. Under the current rules, all consumers who underestimate their income must repay the full amount of excess APTC. This move is intended to ensure that federal subsidies are precisely calibrated to actual yearly earnings, though it places a higher burden on taxpayers to accurately forecast their annual income.
Essential Health Benefits (EHB) and Exclusions
Official guidance maintains that premium tax credits cannot be applied to "non-essential" health benefits. Costs associated with adult dental care, for instance, are not covered by the credit. Furthermore, in compliance with federal law, the portion of a premium associated with "non-Hyde" abortion services requires a separate $1 monthly payment from the enrollee, as federal tax credits cannot be used to fund these specific services.
Implications: The Future of Consumer Health Costs
The transition out of the era of "enhanced" subsidies has profound implications for the average American household. As the market resets to 2027 parameters, several key trends are emerging.
The "Silver" Strategy
For those earning between 100% and 250% FPL, the silver-plan strategy remains the most potent tool for financial protection. By choosing a silver plan, these enrollees trigger cost-sharing reductions that can transform a high-deductible policy into one with the financial characteristics of a gold or platinum plan. The most generous tier, "CSR 94," can drop a deductible from thousands of dollars to negligible amounts, effectively shielding vulnerable households from the risk of medical bankruptcy.
The Coverage Gap
Despite the existence of the Marketplace, the "coverage gap" persists. In states that have not opted to expand Medicaid under the ACA, individuals earning below 100% FPL often find themselves in a precarious position: they earn too much for traditional, non-expansion Medicaid but too little to qualify for ACA premium tax credits. With an estimated 1.2 million Americans currently trapped in this gap, the failure of state-level adoption remains a primary barrier to universal coverage.
The Shift Toward Higher Deductibles
The data from 2026 clearly showed a migration of enrollees toward higher-deductible plans to offset rising premiums. As this trend continues into 2027, the focus shifts from "monthly premium affordability" to "total cost-of-care affordability." Consumers are increasingly tasked with managing significant out-of-pocket maximums—up to $12,000 for self-only and $24,000 for families—which represents a substantial financial risk for middle-income families.
Conclusion: A Dynamic Landscape
The ACA continues to function as a complex, evolving system. For the 2027 plan year, the emphasis has shifted back to the core principles of the original legislation: targeted assistance based on strict income definitions and a clear separation between premium support and out-of-pocket cost control. As consumers prepare for enrollment, the necessity of accurate income reporting and the strategic selection of plans—particularly the silver-tier CSR plans—has never been more critical to ensuring both physical and financial health.
While the removal of repayment caps and the expiration of pandemic-era enhancements present new challenges, the marketplace remains a vital resource. By meticulously comparing the benchmark plan options and understanding the long-term impact of their plan selection, individuals can navigate the current economic climate with greater security and confidence.
About the Author