As the calendar turns toward the final quarter of the year, millions of Americans are preparing for the annual ritual of evaluating their healthcare coverage. The Centers for Medicare and Medicaid Services (CMS) has officially released the data for the 2027 Medicare Advantage (MA) plan year, signaling a period of transition and consolidation in the marketplace. While officials emphasize the overall stability of the system, a deep dive into the numbers reveals a nuanced reality: for the second consecutive year, the average number of plan options available to beneficiaries is on the decline.
For those navigating the complexities of Medicare, understanding these shifts is critical. With open enrollment fast approaching, beneficiaries must balance the promise of a stable marketplace against the practical reality of shrinking choices and evolving plan benefits.
Main Facts: A Shift in Market Dynamics
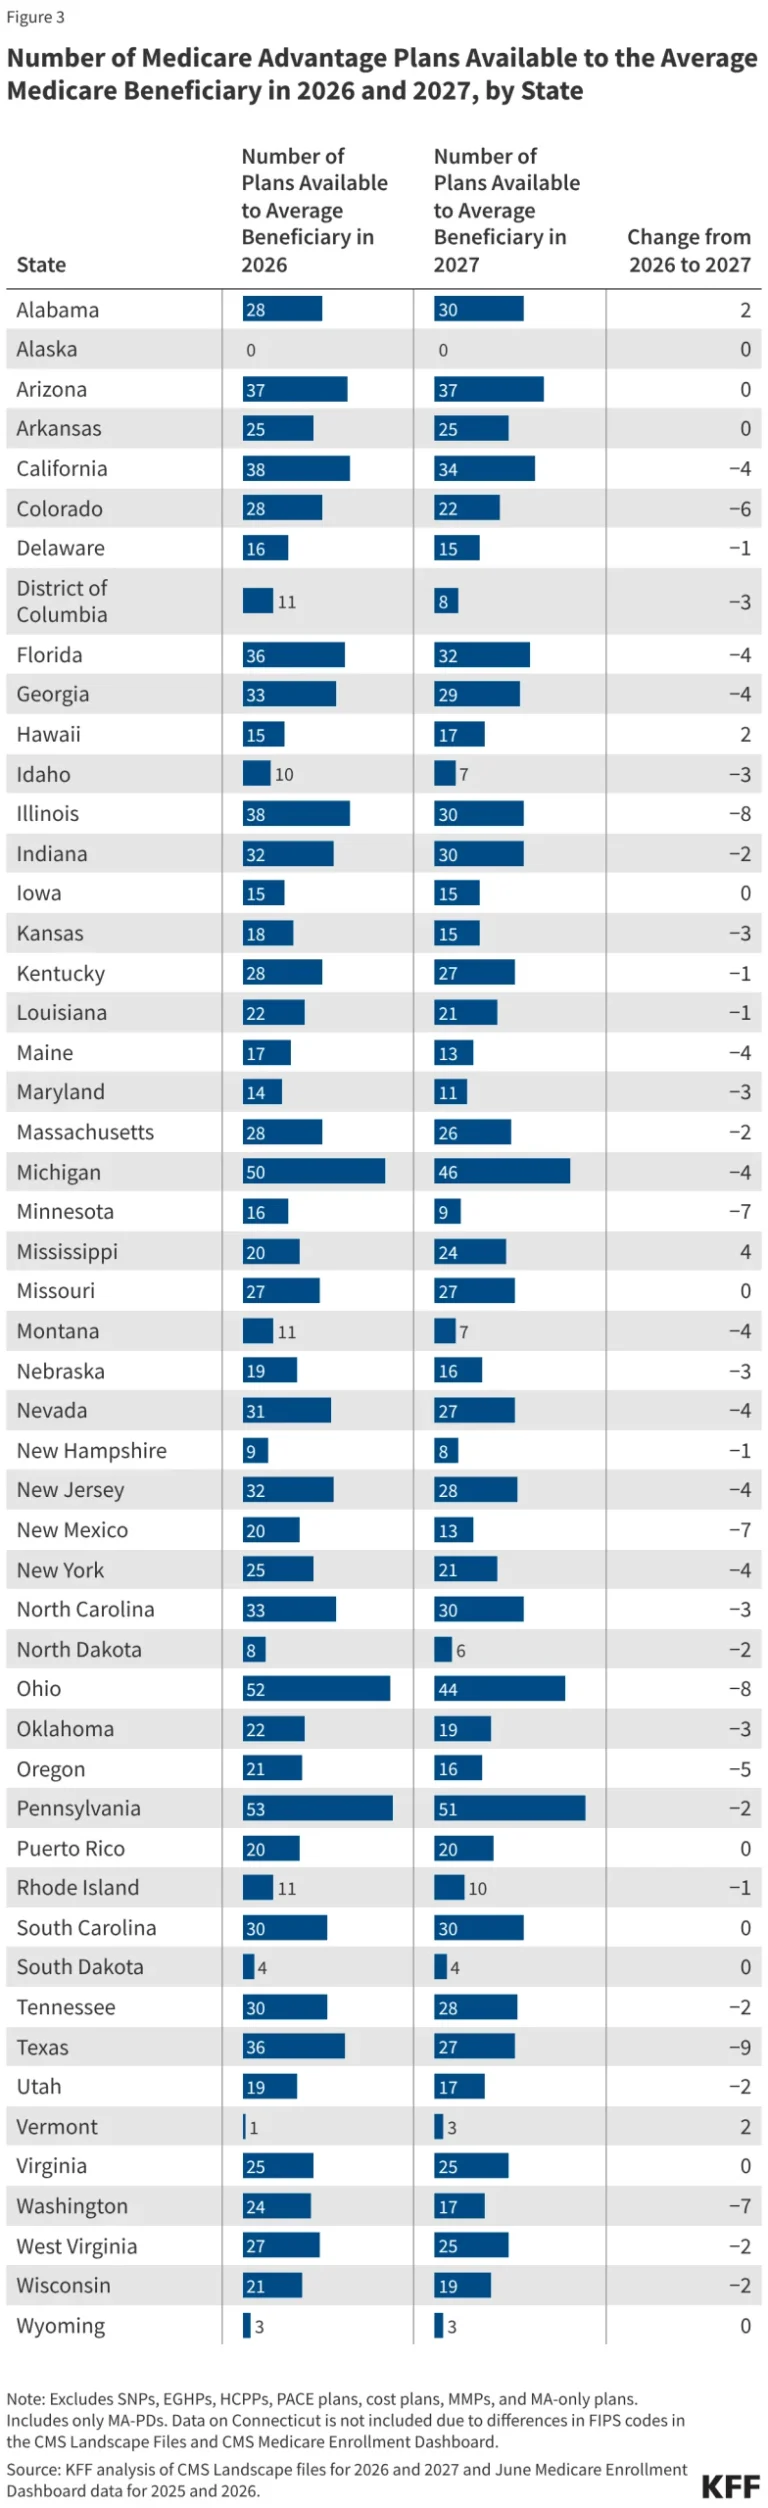
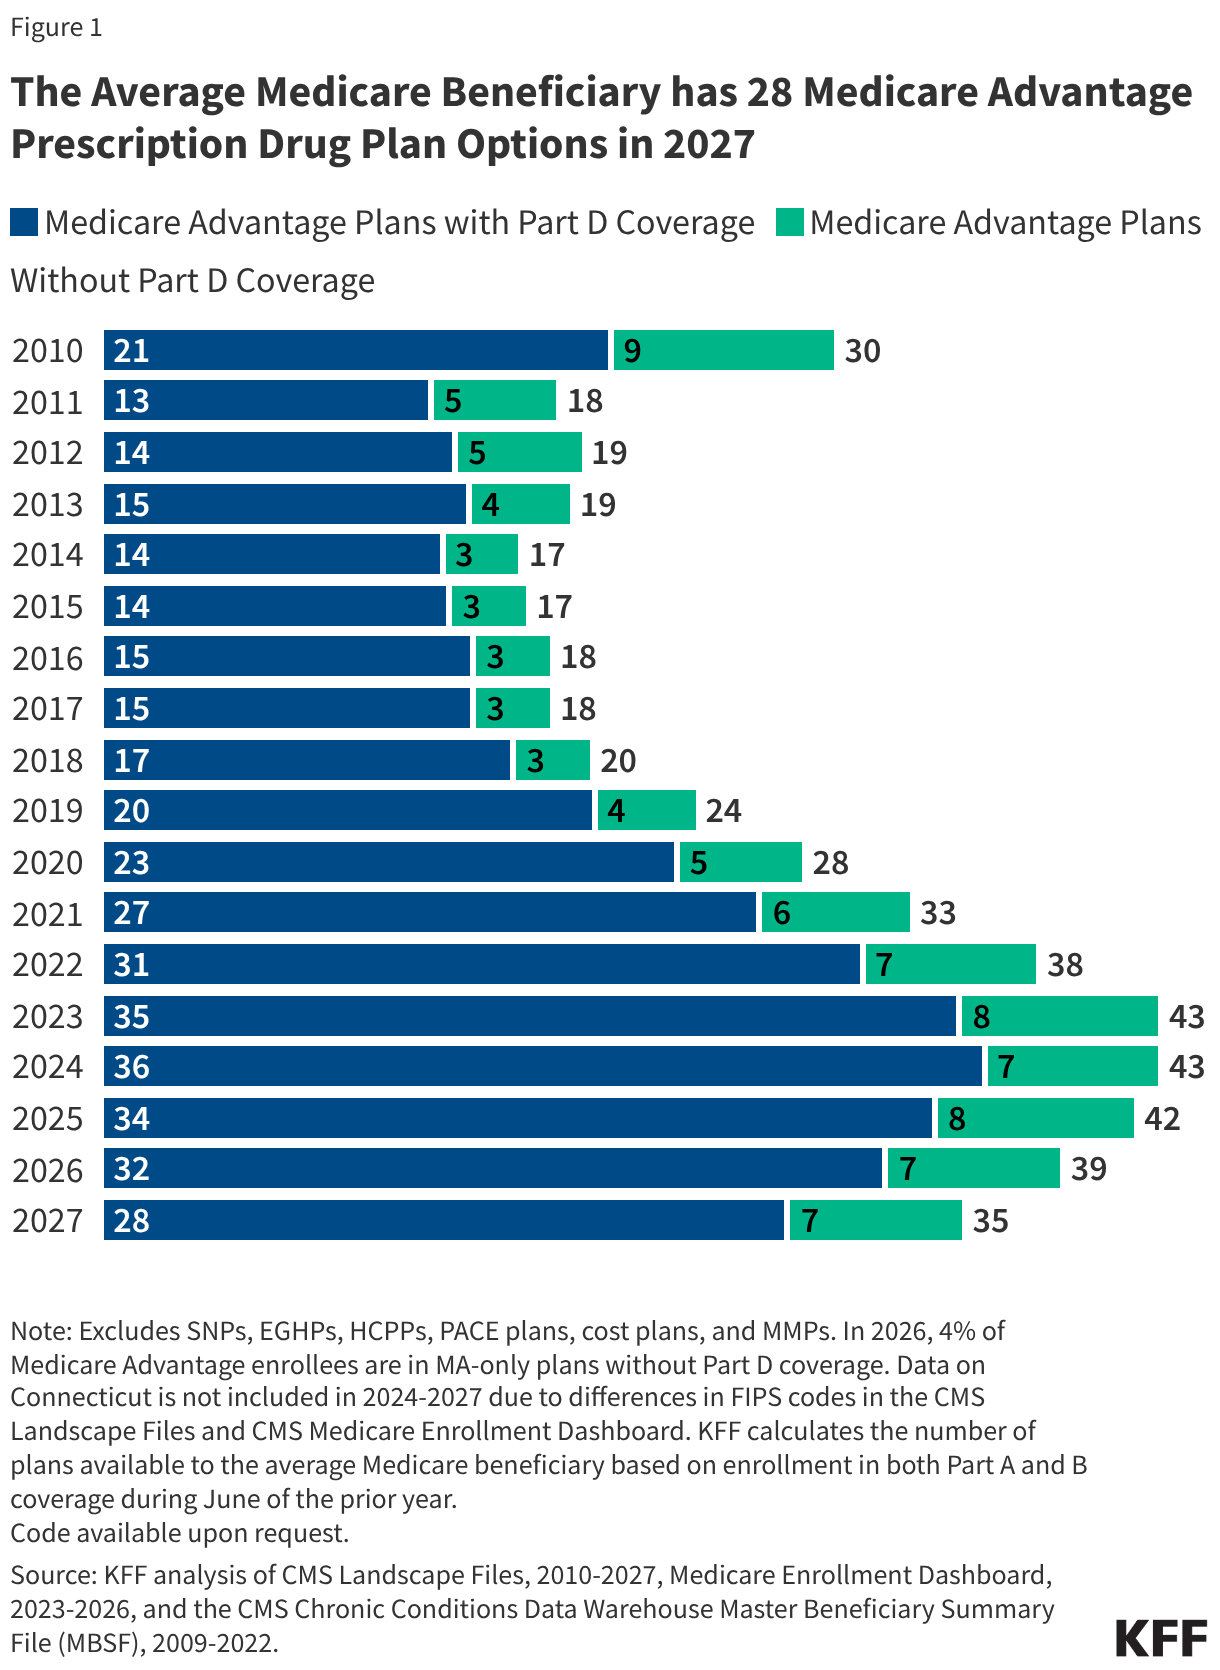
The most significant takeaway from the 2027 CMS data is the tightening of the Medicare Advantage market. According to a recent analysis by KFF, the average Medicare beneficiary will have access to 28 Medicare Advantage Prescription Drug (MA-PD) plans in 2027. This represents a notable decline from the 32 options available in 2026.
When looking at the broader landscape of all Medicare Advantage plans—which includes those both with and without prescription drug coverage—the average beneficiary will have 35 plan choices in 2027, down from 39 the previous year.
Despite this downward trend, it is important to place these figures in their proper historical context. The current levels remain well above the landscape observed between 2010 and 2021. The market saw an unprecedented surge in plan availability that peaked in 2024 with an average of 36 MA-PD options. While the 2027 figures indicate a retraction, they are not indicative of a "collapse," but rather a recalibration of a market that had perhaps reached an unsustainable level of saturation.
Chronology of Market Trends
To understand why the 2027 numbers look the way they do, one must look at the trajectory of the Medicare Advantage program over the last fifteen years.
- 2010–2020: Steady Growth: Following the implementation of the Affordable Care Act and subsequent regulatory adjustments, the number of MA plans began a steady, predictable climb. Insurers saw Medicare Advantage as a lucrative growth engine, leading to an expansion of regional and national offerings.
- 2021–2024: The Era of Expansion: This period saw a massive influx of new plan offerings. By 2024, the average beneficiary was faced with a historic high of 36 MA-PD options. This "choice overload" became a focal point for consumer advocates who argued that too many options often led to "analysis paralysis" among seniors.
- 2025–2026: The Beginning of Consolidation: As federal reimbursement rates were adjusted and insurers faced rising medical costs and administrative burdens, the industry began to trim its portfolios. The drop from 32 to 28 options in the latest data confirms that this trend of consolidation is continuing.
- October 1, 2027: The formal marketing period begins. Insurers, brokers, and third-party entities are permitted to engage with the public to discuss plan changes.
- October 15 – December 7, 2027: The Annual Enrollment Period (AEP). During this critical window, beneficiaries can make fundamental changes to their coverage, switching between traditional Medicare and Medicare Advantage, or changing plans within the Advantage ecosystem.
Supporting Data: Regional Variations and Disparities
The national average of 28 plans masks significant regional disparities. Medicare Advantage is inherently local, and the number of plans available to a beneficiary depends heavily on their zip code.
State-Level Variability
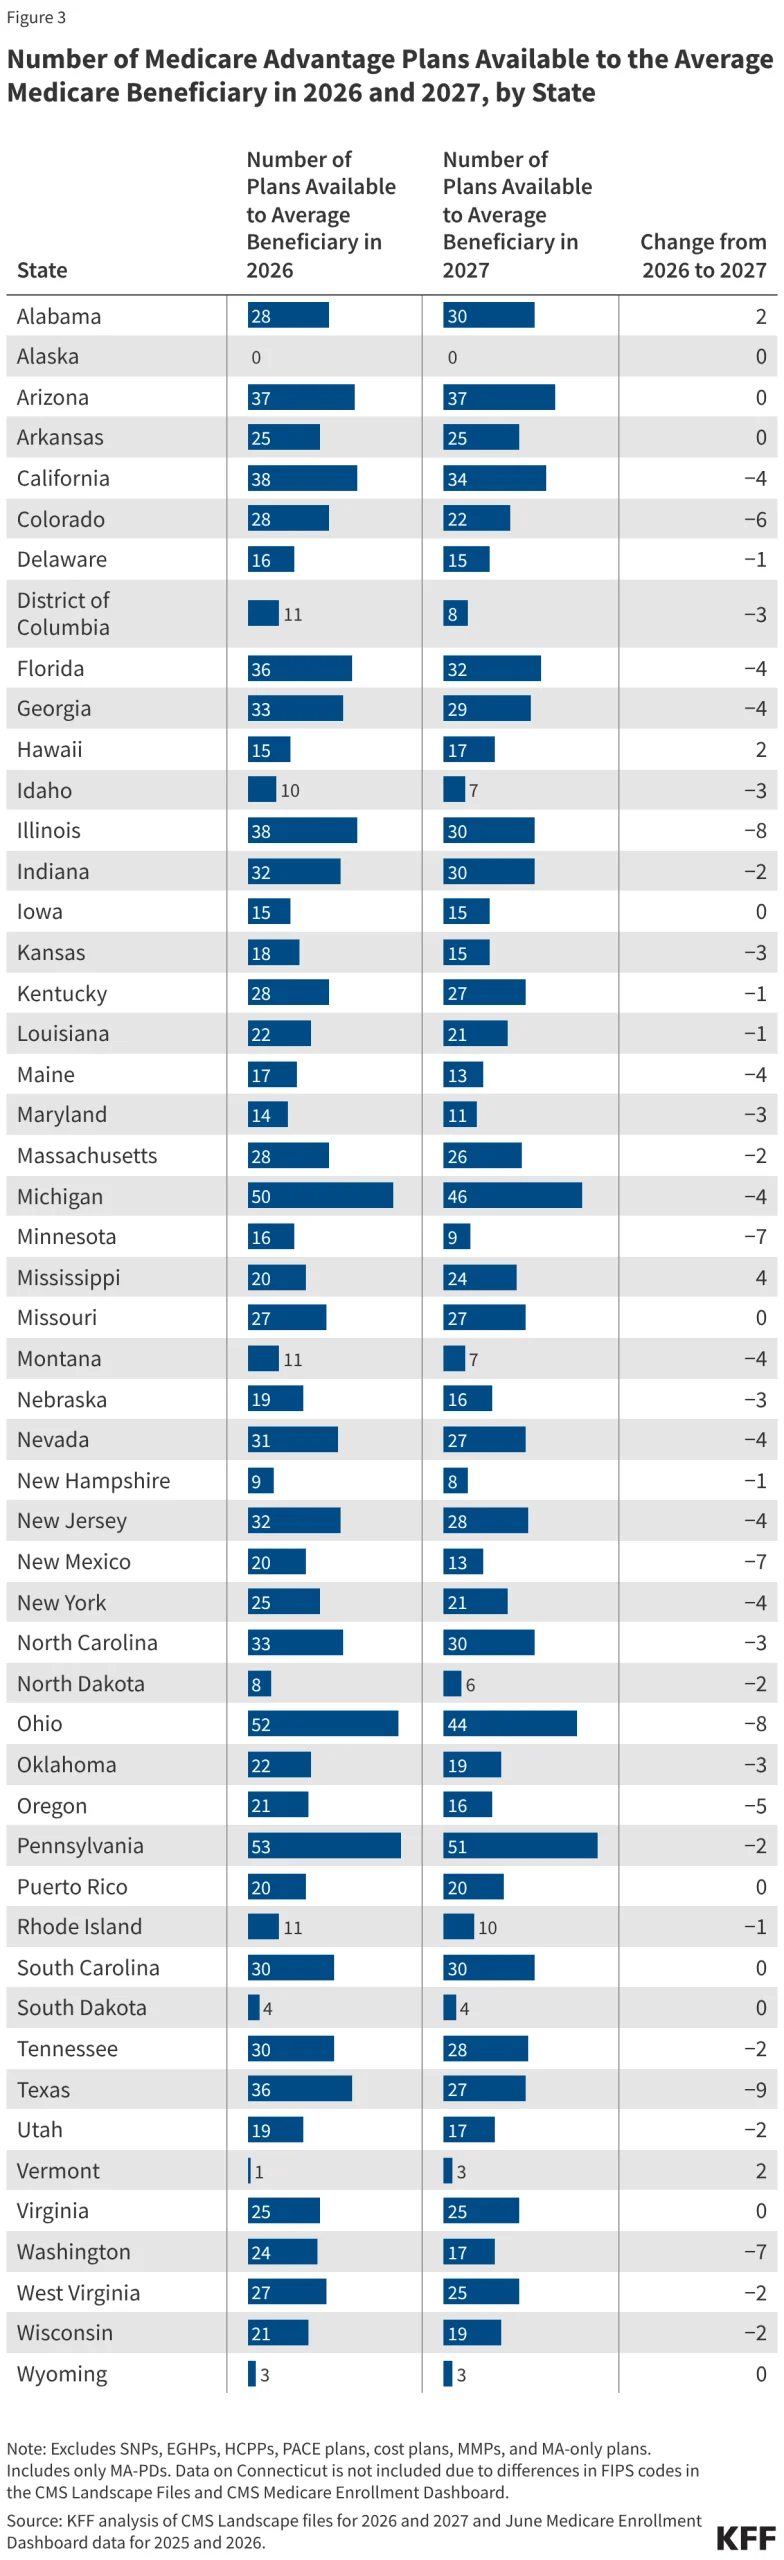
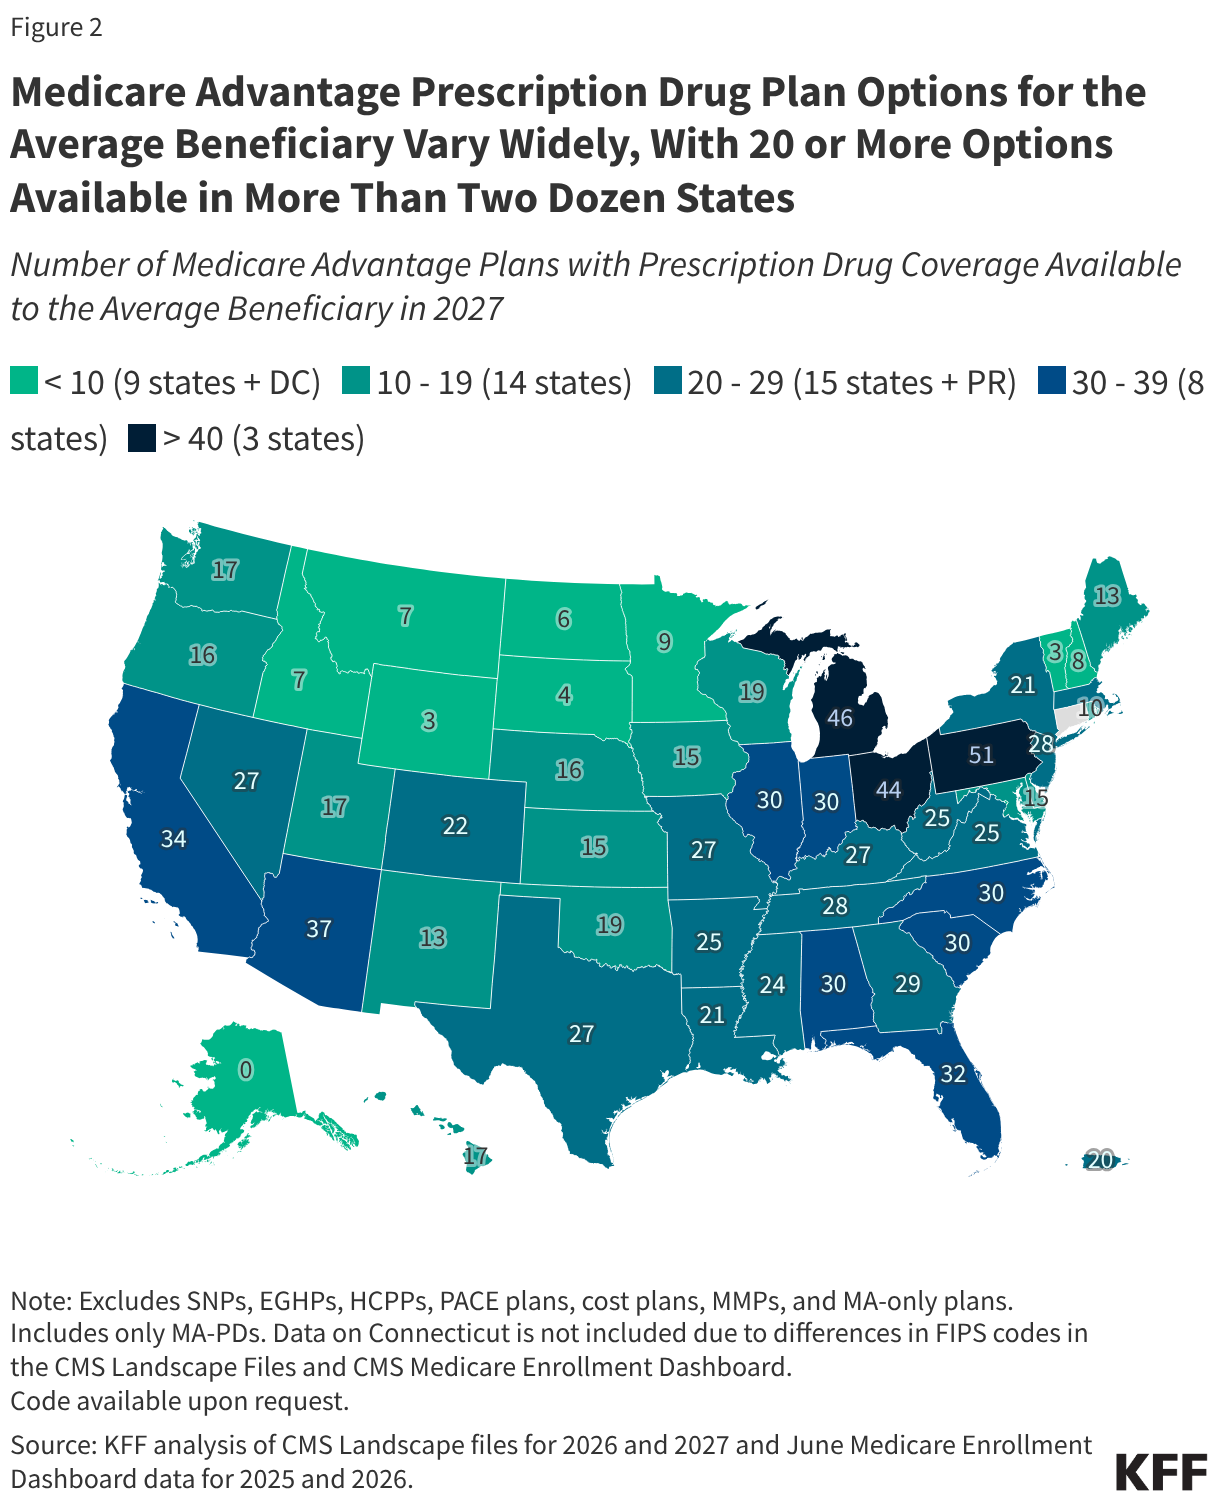
The 2027 data shows a stark divide across the country. In 26 states and Puerto Rico, beneficiaries enjoy at least 20 MA-PD options. In states like Pennsylvania, Michigan, and Ohio, the market remains highly competitive, with the average beneficiary having access to 40 or more MA-PD plans.
Conversely, in nine states and the District of Columbia, the average beneficiary has fewer than 10 MA-PD options. Alaska remains an outlier, with virtually no Medicare Advantage plans available for general enrollment, a status that has persisted for several years. This highlights a persistent urban-rural divide: while urban centers often have dozens of competing plans, rural areas frequently struggle to attract insurers willing to provide broad-based network coverage.
States with the Sharpest Declines
The contraction is not felt equally. The states experiencing the most significant drop in available plans include:
- Texas: A reduction of 9 plans.
- Illinois and Ohio: A reduction of 8 plans.
- Minnesota, New Mexico, and Washington: A reduction of 7 plans.
For residents in these states, the potential for plan disruption is higher. If a specific insurer decides to exit a county or consolidate its offerings, beneficiaries may find their current plan no longer exists for the 2027 year.
Official Responses and Regulatory Outlook
In its official press release, the Centers for Medicare and Medicaid Services (CMS) has maintained a message of "marketplace stability." CMS argues that while the number of plans is decreasing, the core functions of the Medicare Advantage program—providing comprehensive coverage for Part A and Part B benefits—remain intact.
Regulatory bodies have been working to balance the needs of insurers with the protection of beneficiaries. Recent adjustments to the "rebate" system, which allows plans to use federal payments to cover supplemental benefits or reduce premiums, have been a subject of intense lobbying. Insurers argue that tighter margins make it difficult to offer the same generous supplemental benefits (such as vision, dental, or fitness programs) that became common during the expansion years. CMS, however, maintains that the program remains robust and that beneficiaries continue to have access to high-quality care, even if the sheer volume of choices is lower.
Implications: The Challenge for the Beneficiary
The most pressing implication of the 2027 data is the increased burden placed on the beneficiary. When a plan exits the market, the transition process is often automated, but not always optimized.
The Automated Transition
In many instances, if an insurer exits a market, they may "map" enrollees to a similar plan within the same company. While this prevents a total loss of coverage, it is not a guarantee that the new plan will match the beneficiary’s specific needs regarding drug formularies or provider networks. For the passive enrollee who does not review their mail, this could result in higher out-of-pocket costs or a doctor being removed from their network.
The "Analysis Paralysis" Factor
Despite the complexity of these changes, research from KFF suggests that nearly 7 in 10 Medicare beneficiaries do not compare their coverage options annually. The combination of declining options and the potential for "hidden" changes—such as shifting prior authorization requirements, changing out-of-pocket limits, and narrowing provider networks—makes this status quo dangerous.
Preparing for Open Enrollment
As the October 15th start date approaches, stakeholders suggest three primary steps for all Medicare beneficiaries:
- Read the ANOC: Every beneficiary should receive an "Annual Notice of Change" (ANOC) from their current plan. This document details exactly how costs and benefits will change in 2027. Do not ignore it.
- Check the Formulary: If you take prescription medications, ensure that your specific drugs remain on your plan’s formulary for 2027. A plan might remain the same in name, but its drug coverage rules may have shifted.
- Evaluate the Network: Use the Medicare Plan Finder tool on Medicare.gov to ensure your preferred physicians and hospitals remain in-network for the coming year.
Conclusion: A Time for Diligence
The 2027 Medicare Advantage market is undergoing a necessary shift. While the reduction in plan options may simplify the shopping process for some, it brings with it the risk of disruption for those whose plans have been consolidated or eliminated.
The stability touted by federal regulators is a macroeconomic reality, but for the individual senior, healthcare is inherently personal. The shrinking number of plans serves as a reminder that the Medicare landscape is not static. Beneficiaries who take the time to review their options, understand the changes in their specific region, and proactively manage their coverage will be in the best position to protect their health and their finances in the year ahead. As the market consolidates, the value of being an informed consumer has never been higher.
About the Author