The intersection of artificial intelligence and pharmaceutical development has long been framed as the next great frontier of medicine. In theory, AI offers the ability to compress years of discovery into months, mapping the vast, complex landscape of biological targets with unprecedented precision. Yet, for the public markets, the narrative has been starkly different. While investors have clamored for companies developing Large Language Models or AI-integrated semiconductors, they have remained decidedly wary of "tech-bio" firms.
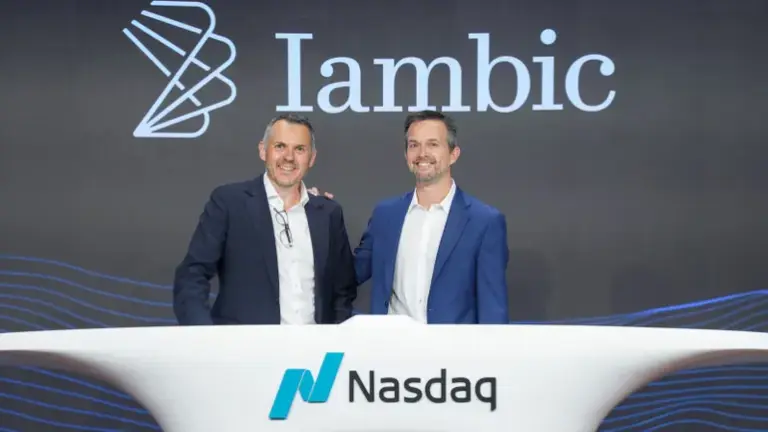
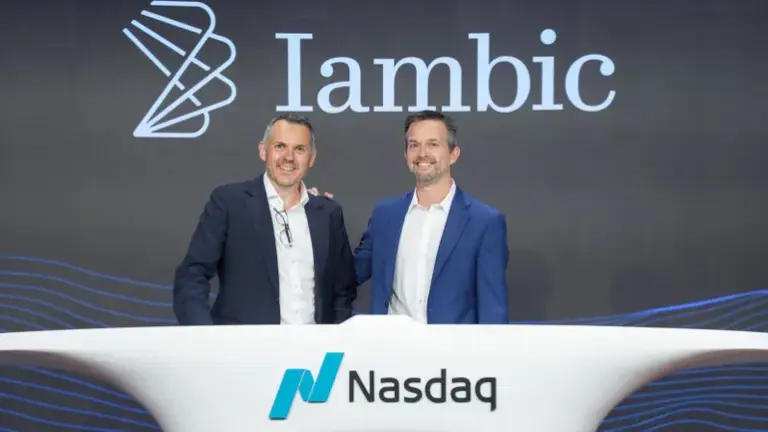
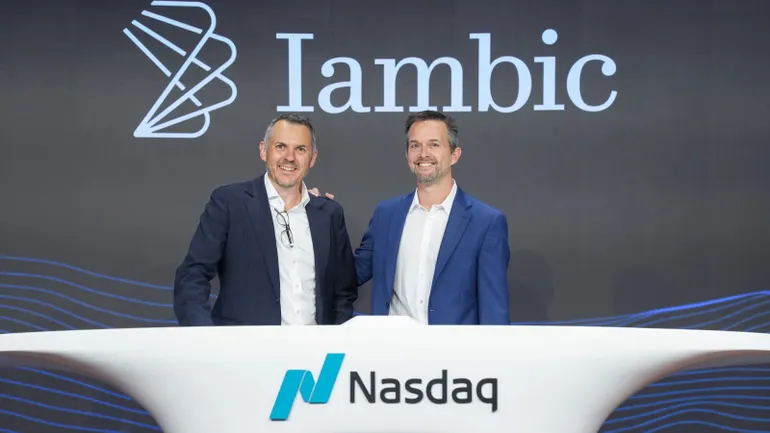
As Iambic Therapeutics officially joins the public markets following a $150 million initial public offering (IPO) this week, it enters a sector marked by skepticism. Investors have watched as high-profile predecessors—most notably Exscientia and Recursion Pharmaceuticals—saw their market valuations eroded following their transitions from private startups to public entities. Iambic now faces the critical challenge of proving that its marriage of machine learning and clinical execution can withstand the scrutiny of Wall Street.
A Turbulent History: The AI Drug Discovery IPO Struggle
The skepticism surrounding AI-driven drug discovery is not born from a lack of potential, but from a track record of underperformance. The promise of AI in this space is often characterized by the "platform" model—the idea that a company can build a proprietary engine to repeatedly churn out drug candidates.
However, investors have increasingly demanded proof of results, not just a description of the engine. The market has been unforgiving to firms that struggle to translate computational output into clinical reality. Exscientia, once a darling of the AI-biotech scene, saw its shares plummet roughly 80% from their debut price, ultimately leading to its acquisition by Recursion in 2024. Recursion itself has faced significant headwinds; after listing at $18 per share, its stock has languished, recently trading under the $4 mark.
These outcomes have fostered a "show-me" mentality among biotech investors. They are no longer impressed by the novelty of the technology alone. They are looking for tangible clinical data, successful regulatory milestones, and a clear path to commercialization. It is against this backdrop that Iambic Therapeutics has chosen to test the public markets.
The Iambic Approach: A Different Path to Public Valuation
Founded in 2019, Iambic Therapeutics has taken a deliberate approach to its growth. By securing nearly half a billion dollars in private funding from a syndicate of seasoned life sciences investors—including Nexus, Abingworth, and Catalio Capital Management—the company has focused on building a foundation of both intellectual property and clinical validation before seeking public capital.
The recent $150 million IPO was met with a degree of cautious optimism. By the middle of Friday, shares were trading at approximately $24.50, reflecting a 50% gain over their Wednesday offering price. Yet, this haul was conservative compared to the massive "megarounds" seen in the private market or the more aggressive IPOs of traditional biotechs.
Tom Miller, co-founder and CEO of Iambic, suggests that this measured approach is a feature, not a bug. "Iambic came to the IPO with a very strong cash position on the basis of all our partnerships," Miller explains. "We priced it with an eye toward bringing in a broad syndicate of investors who not only understand technology but have deep understanding on the life science side of what it takes to build great medicines."
The "Tech-Bio" Balancing Act: Insights from CEO Tom Miller
In a conversation with BioPharma Dive, Miller articulated his vision for how Iambic differentiates itself from the companies that struggled before it. The core of his strategy is a relentless focus on clinical milestones.
Measuring Success Through Clinical Reality
"Iambic has really focused on bringing new molecules to and through clinical trials as our measure of success," Miller notes. He points to the company’s lead candidate, IAM1363, a highly selective HER2 inhibitor, which reached the clinic in under two years. According to Miller, the company is already planning for registrational trials by 2027, backed by data from over 100 patients.
"Technology is great," Miller argues. "We should be asking: Are you converting it to medicines?" This philosophy represents a shift from the "platform-first" narrative that characterized early AI-biotech IPOs toward a "medicine-first" narrative.
The Role of Strategic Partnerships
Iambic has been notably prolific in its partnership strategy, having secured agreements with pharmaceutical giants like Takeda, AbbVie, and Bayer. Rather than relying on these partnerships solely for cash, Miller views them as essential to the company’s maturation.
"Pharma recognizes Iambic is a partner that can execute," Miller says. "We don’t do it just for the logos on the slide." He emphasizes that these collaborations provide the company with increased expertise, access to broader data sets, and a mechanism to validate their technology across diverse therapeutic areas, including neurology, inflammation, and immunology.
Implications for the Future of Drug Development
The disconnect between the valuation of companies like Iambic and the astronomical sums being discussed for private entities like Isomorphic Labs (which has been rumored to be seeking a valuation in the tens of billions) highlights a deepening divide in the sector. While some firms are valued as high-tech AI companies, others—like Iambic—are being priced as clinical-stage biotechs.
The Problem of Hyperbole
A significant challenge facing the industry is the tendency toward over-promising. When industry leaders, such as the CEO of Anthropic, suggest that AI could potentially "cure all diseases" within a decade, it sets expectations that the current pharmaceutical infrastructure cannot meet.
Miller remains grounded in the face of such rhetoric. "If we keep our eye on the patient, if we keep our eye on the development of better medicines that have a genuine and urgent unmet need, then I think we are going to keep our eye on what really matters," he states.
Building a "Generational" Company
For Iambic, the goal is to create an entity that possesses the "innovation urgency of a tech company" but the "execution maturity of a biotech." This hybrid model is intended to capture the best of both worlds: the iterative, data-driven speed of machine learning and the rigorous, trial-tested safety protocols of traditional pharmaceutical development.
As the company moves forward as a public entity, the pressure will only increase. Investors will look for:
- Clinical Data: Continued evidence that the AI-generated candidates perform as expected in human trials.
- Capital Efficiency: Whether the $150 million raised, combined with existing partnership revenue, is sufficient to reach the next major clinical inflection point without further dilution.
- Pipeline Diversification: Whether the company can successfully expand its pipeline into metabolic disease and endocrinology while maintaining the high standards set by its lead oncology assets.
Conclusion: The Verdict Still Pending
The road ahead for Iambic Therapeutics will serve as a bellwether for the "AI-in-Pharma" thesis. If Iambic can maintain its clinical momentum and deliver consistent data, it may succeed in changing the investor narrative that has plagued its predecessors. However, if it falls into the trap of prioritizing technical complexity over therapeutic output, it risks the same fate as those who came before.
For now, the company has successfully navigated the first hurdle of the public markets. Whether it can maintain that momentum will depend on its ability to prove that its algorithms are not just capable of designing molecules, but of reliably and repeatedly delivering life-saving treatments to patients. In the high-stakes world of biotech, that is the only metric that will ultimately decide whether Iambic is a momentary success or a generational leader.
About the Author