The intersection of artificial intelligence and pharmaceutical development has long been framed as the next frontier of human medicine. Yet, for all the venture capital fervor and transformative promises of "silicon-driven discovery," the public markets have delivered a sobering verdict. While the broader stock market remains enamored with the generative AI boom, investors have proven increasingly skeptical of the drug discovery startups that claim to be its vanguard.
As Iambic Therapeutics makes its foray into the public markets, it faces a market environment scarred by the struggles of its predecessors. Can Iambic prove that it is a generational company, or will it succumb to the same volatility that has plagued firms like Recursion Pharmaceuticals and the now-acquired Exscientia?
A Landscape of Disillusionment and Caution
To understand the stakes for Iambic, one must look at the recent history of the "tech-bio" sector. High-profile companies that once commanded massive valuations have seen their market capitalizations evaporate. Exscientia, a pioneer in the field, saw its shares plummet roughly 80% from their debut price before eventually agreeing to a sale to Recursion Pharmaceuticals in 2024. Recursion itself, once the poster child for AI drug discovery, has struggled mightily; after listing at $18 per share, its stock currently languishes well below $4.
These failures have created a "show-me" environment. Investors are no longer satisfied with white papers detailing sophisticated machine learning algorithms; they are demanding tangible clinical outcomes. Iambic Therapeutics, founded in 2019, has attempted to differentiate itself by positioning its platform not as a research curiosity, but as an engine for clinical execution.
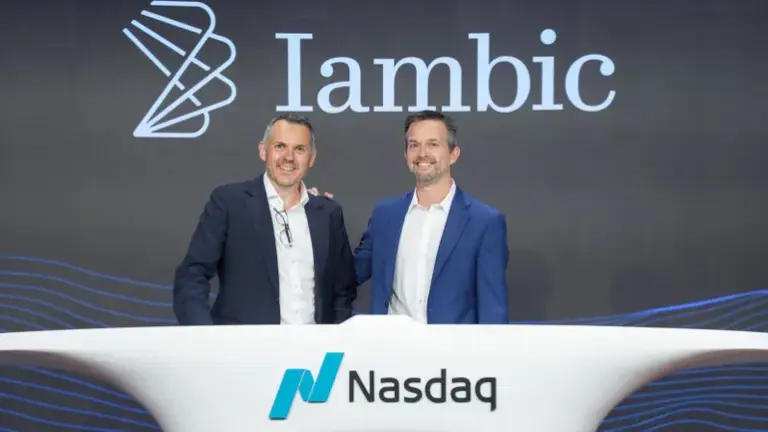
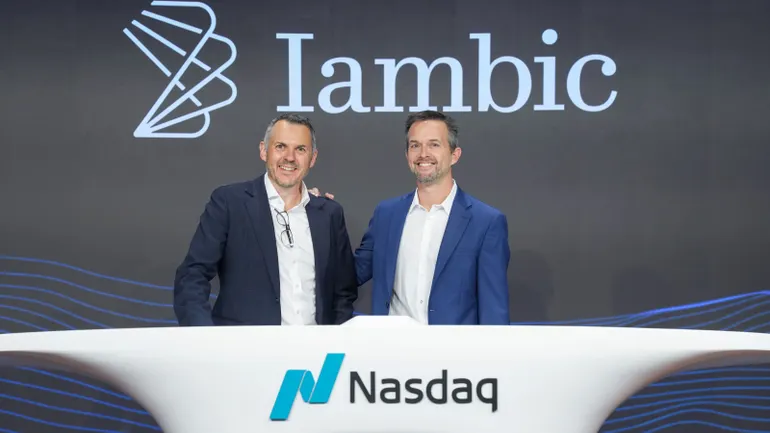
Following a successful $150 million IPO earlier this week, Iambic’s share price saw a healthy bounce, hovering around $24.50 by Friday—an increase of more than 50% from its initial pricing. However, industry analysts remain cautious. The IPO haul was modest compared to the megarounds seen in the private sector, and the long-term sustainability of this momentum remains the primary question for shareholders.
Chronology of a Platform: From Inception to IPO
Iambic’s trajectory reflects a deliberate effort to balance technical prowess with pharmaceutical rigor.
- 2019: Iambic Therapeutics is founded, centered on an AI-driven platform designed to accelerate the identification and optimization of small-molecule medicines.
- 2021–2023: The company secures nearly half a billion dollars in funding from high-profile life sciences investors, including Nexus, Abingworth, and Catalio Capital Management.
- 2024: The company demonstrates its operational speed by moving its lead asset, IAM1363—a highly selective HER2 inhibitor—into Phase 1 clinical trials in less than two years.
- 2025–2026: Iambic establishes a "drumbeat" of high-profile partnerships with industry giants, including Takeda, Bayer, and AbbVie, validating its platform through collaborative drug discovery.
- October 2026: Iambic completes its $150 million IPO, positioning itself as a company that prioritizes clinical execution over platform-only rhetoric.
Supporting Data: The Case for "Clinical-First" AI
Iambic’s leadership, led by co-founder and CEO Tom Miller, argues that the disconnect between AI’s potential and stock performance stems from a failure to prioritize the "medicine" part of "tech-bio."
"Technology is great," Miller noted in an interview with BioPharma Dive. "We should be asking: Are you converting it to medicines?"
The data supports Iambic’s claim to efficiency. By moving IAM1363 to the clinic in under 24 months, the company has provided investors with a clear metric of success. Furthermore, the company reported over $270 million in cash on hand prior to its recent IPO—a significant war chest bolstered by its strategic partnerships. Unlike many peers who burned through cash while struggling to produce viable clinical leads, Iambic has used collaborations to subsidize its R&D while simultaneously validating its AI models.
The Strategy: "Molecule-to-Molecule" Validation
In a competitive market where companies like Isomorphic Labs are reportedly discussing valuations in the tens of billions, Iambic is choosing a more pragmatic path. When asked about the disparity in valuation and investor sentiment, Miller remains steadfast in his commitment to a dual-thesis approach.
"Iambic has been building a company that connects the thesis of better technologies making better medicines," Miller explained. "We don’t take a backseat on technology to anybody. We’re happy to go AI model to AI model with any company, but we’re also happy to go molecule to molecule in terms of real-world clinical development."
This dual-track strategy—maintaining a proprietary, wholly owned pipeline while engaging in high-value pharma collaborations—is the core of Iambic’s defense against market skepticism. By working in areas like neurology, inflammation, and immunology alongside its core oncology focus, the company is demonstrating the versatility of its platform.
Official Responses and Industry Implications
The broader industry is watching Iambic closely to see if it can reset the narrative. The prevailing concern in the sector is that AI has become a victim of its own hype. When tech executives make sweeping, hyperbolic statements—such as the suggestion that all diseases could be cured within a decade—it sets expectations that are impossible for clinical science to meet on such a truncated timeline.
Miller, however, is quick to distance Iambic from this brand of rhetoric. "If we keep our eye on the patient, if we keep our eye on the development of better medicines that have a genuine and urgent unmet need, then I think we are going to keep our eye on what really matters," he said.
The Role of Big Pharma Partnerships
There has been debate as to whether "big pharma validation" is still a necessary hurdle for AI startups. While some believe the field has moved past the point where a partnership is required to prove legitimacy, Miller views it differently. He argues that partnerships are not merely "logos on a slide," but essential tools for cross-pollination. Bringing in experienced staff from partners like AbbVie or Bayer strengthens Iambic’s own internal capabilities, allowing them to iterate faster on their wholly owned assets.
The Road Ahead: Can Execution Overcome Hype?
The implications of Iambic’s public journey are significant for the entire biotechnology sector. If Iambic succeeds, it will likely create a new blueprint for "Generation 2" AI drug companies: firms that treat AI as an industrial tool for execution rather than an end in itself.
However, the path forward is fraught with challenges. The company is now subject to the quarterly scrutiny of public markets, where long-term clinical development timelines often clash with short-term investor demands. The transition from a privately funded, high-growth startup to a publicly traded clinical-stage company requires a level of transparency and operational discipline that few have mastered.
As Iambic looks toward its 2027 goal of initiating registrational trials, its ability to maintain its "execution maturity" will be the true test. The company has successfully raised capital, secured high-level partnerships, and demonstrated clinical velocity. Whether these ingredients are enough to convince a weary public market remains to be seen.
Ultimately, Iambic’s fate will be decided not in the boardrooms of Wall Street, but in the clinics. If their platform can reliably churn out medicines that address unmet medical needs, the market will eventually have no choice but to follow. For now, Iambic stands as a compelling, albeit cautious, attempt to reconcile the promise of the AI revolution with the harsh realities of drug discovery.
About the Author