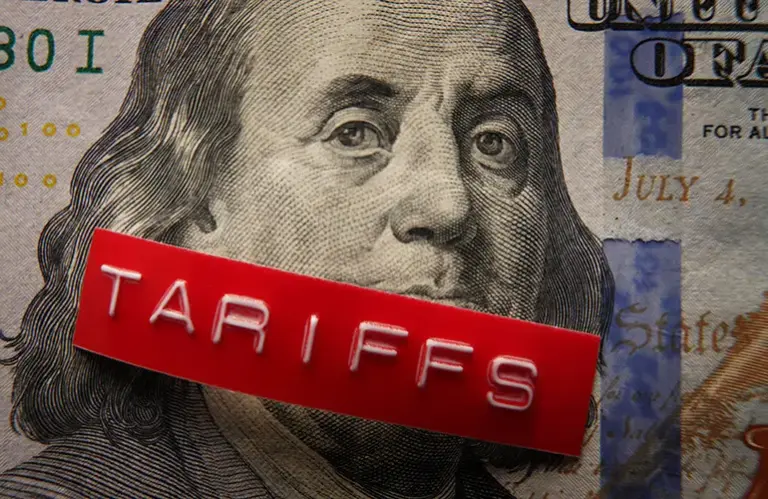
The landscape of American pharmaceutical manufacturing is undergoing a seismic, government-mandated transformation. Following a year of heightened rhetoric and the formal execution of a national-security proclamation by President Donald Trump, the U.S. government has expanded its Section 232 tariff regime to encompass the entire spectrum of the pharmaceutical industry. As of September 29, 2026, the sweeping import duties—which can climb as high as 100%—are no longer the exclusive burden of the largest industry players; they now apply to mid-sized and smaller drugmakers, placing immense pressure on the biotech sector’s R&D capabilities and global supply chains.
The policy, grounded in the Trade Expansion Act of 1962, seeks to aggressively reduce U.S. reliance on foreign-sourced active pharmaceutical ingredients (APIs) and finished products. However, as the net widens, the industry is grappling with a stark reality: the cost of compliance, the complexity of onshoring, and the potential for a long-term chilling effect on medical innovation.
Chronology of a Regulatory Shift
The journey toward these broad-based tariffs was marked by strategic, incremental implementation designed to pressure the industry into rapid alignment with domestic manufacturing goals.
- April 2026: President Trump signs a national-security proclamation under Section 232 of the Trade Expansion Act of 1962. The proclamation identifies the reliance on foreign pharmaceutical supply chains as a threat to national security, laying the groundwork for the current tariff structure.
- July 31, 2026: The first phase of the policy takes effect. Seventeen major pharmaceutical manufacturers are targeted, marking the beginning of the enforcement period.
- September 23, 2026: The Department of Commerce issues critical guidance and procedures, carving out specific exemptions for R&D and clinical trials, providing a much-needed lifeline to researchers.
- September 29, 2026: The scope of the tariffs is officially expanded to include mid-sized and smaller drug manufacturers, effectively bringing the entire patented medicine sector under the regulatory umbrella.
- July 2028 (Anticipated): The start of a separate, phased tariff schedule for generic medicines, beginning with a period of no duties followed by a steep escalation.
The Financial Mechanics of Compliance
For the average pharmaceutical firm, the new tariff environment is a labyrinthine challenge. The duty applied to any given product is not a flat rate; it is a variable calculation based on a company’s strategic choices.
"What a company pays will depend on its onshoring and pricing commitments, product mix, and sourcing," says Chris Young, principal of trade and customs at KPMG. "Near-term cost and compliance work must now sit alongside long-term manufacturing and supply chain decisions."
The Tiered Tariff Structure
The government has established a hierarchy of compliance that dictates how much a company pays:
- The "Onshoring" Pathway: Companies that commit to domestic manufacturing can receive a reduced rate of 20%. However, this is a temporary grace period, as that rate is scheduled to scale up to 100% by April 2, 2030.
- The "Most-Favored-Nation" (MFN) Agreement: Firms that pair an onshoring plan with a specific MFN drug-pricing agreement can qualify for a 0% tariff rate through January 20, 2029.
- Country-Specific Arrangements: Trade diplomacy has created "safe harbors." Products originating from the EU, Japan, South Korea, Switzerland, and Liechtenstein are subject to a 15% rate. The United Kingdom, having reached a separate pricing arrangement with the U.S., currently enjoys a 0% rate through January 19, 2029.
For companies that cannot secure an exemption, the choices are grim: absorb the massive import costs, which will erode profit margins; invest billions of dollars to build domestic manufacturing facilities; or pass the costs to consumers—a move that carries significant political and public relations risk in an environment where 82% of U.S. adults already view drug prices as unreasonable.
Supporting Data and Economic Realities
The economic burden of these tariffs is compounded by the high barrier to entry for domestic pharmaceutical production. Building a state-of-the-art manufacturing facility is a monumental undertaking, often requiring capital expenditure of up to $2 billion and a development timeline spanning five to ten years.
Small and mid-sized biotech firms, which are responsible for a significant portion of medical innovation, are particularly vulnerable. As the Biotechnology Innovation Organization (BIO) noted in its May 2025 comments to the Department of Commerce, these smaller entities do not have the balance sheets to build internal manufacturing capabilities. Instead, they rely heavily on contract manufacturing organizations (CMOs), many of which are based overseas.
Furthermore, the data suggests that the pharmaceutical industry is already operating on thin margins for many patented drugs due to existing pricing pressures. The introduction of 100% tariffs on imported components could effectively price some life-saving treatments out of the market entirely, or force companies to abandon therapeutic programs that are no longer financially viable under the new cost structure.
Official Responses and Industry Pushback
The reaction from the biotech sector has been one of alarm, with industry leaders arguing that the policy conflates national security with industrial protectionism at the expense of patient health.
John F. Crowley, president and CEO of BIO, has been the most vocal critic of the administration’s approach. In his April statement, Crowley emphasized that the tariffs represent a direct diversion of capital away from the laboratory. "Tariffs divert scarce resources away from research and development," Crowley argued, warning that the move would delay the discovery of new treatments and, ironically, weaken the American biotech sector’s competitive edge against the rapidly expanding pharmaceutical industry in China.
Conversely, the U.S. government maintains that the long-term benefit of a resilient, domestic-led supply chain outweighs the short-term disruption. By using Section 232, the administration is betting that the threat of high tariffs will compel the industry to "de-risk" its supply chains from geopolitical adversaries.
Strategic Exemptions: A Necessary Safety Valve
Recognizing the potential for the tariffs to stifle clinical progress, the Department of Commerce has introduced significant exemptions. Under the guidance published on September 23, 2026, products and ingredients imported solely for use in clinical trials, R&D, or other non-commercial applications are eligible for a 0% tariff rate.
Additionally, there is a carve-out for specialty medicines—such as cutting-edge cell and gene therapies and antibody-drug conjugates. These treatments may qualify for zero tariffs if they are sourced from a jurisdiction with an existing trade and security framework agreement or if they are deemed to satisfy an urgent U.S. health need. These exemptions serve as a vital, if narrow, release valve, ensuring that the most innovative and time-sensitive research is not immediately derailed by trade policy.
Implications for the Future
As the industry moves toward the 2028-2030 deadlines, several long-term implications are beginning to crystallize:
The Generic Drug Question
While the current focus is on patented medicines, the shadow of the policy looms over the generic drug market. The April proclamation mandates an assessment of whether to extend these tariffs to generics within a year. Given that generics account for the vast majority of prescriptions filled in the U.S., any move to impose tariffs on them would have a far more direct impact on consumer out-of-pocket costs than the current focus on patented drugs. With the administration’s announced plan for a phased approach—moving from 0% to 100% and then to 200%—the generic sector is facing an existential threat to its current business model.
Shifts in Global Supply Chains
The pharmaceutical industry is inherently global. The shift toward "onshoring" is not merely a logistical challenge; it is a fundamental restructuring of international trade. We are likely to see a significant move toward "near-shoring" (moving production to countries within the U.S. trade sphere, such as Mexico or Canada) as companies scramble to avoid the 100% duties while avoiding the prohibitive costs of full domestic production.
Innovation vs. Protectionism
The central tension of this policy remains the conflict between national security and the speed of innovation. If the United States succeeds in fostering a robust domestic manufacturing sector, it may achieve its goal of a more secure supply chain. However, if the cost of that security is a diminished capacity for small-firm R&D, the global lead of the American biotech sector may be at risk.
In conclusion, the pharmaceutical industry is currently navigating a high-stakes transition. The "tariff-first" approach to trade policy is forcing a re-evaluation of every link in the pharmaceutical supply chain. As companies adjust their strategies, the coming months will reveal whether this policy serves as the catalyst for a new era of American manufacturing independence or as a drag on the very innovation that the industry seeks to provide to the world.
About the Author