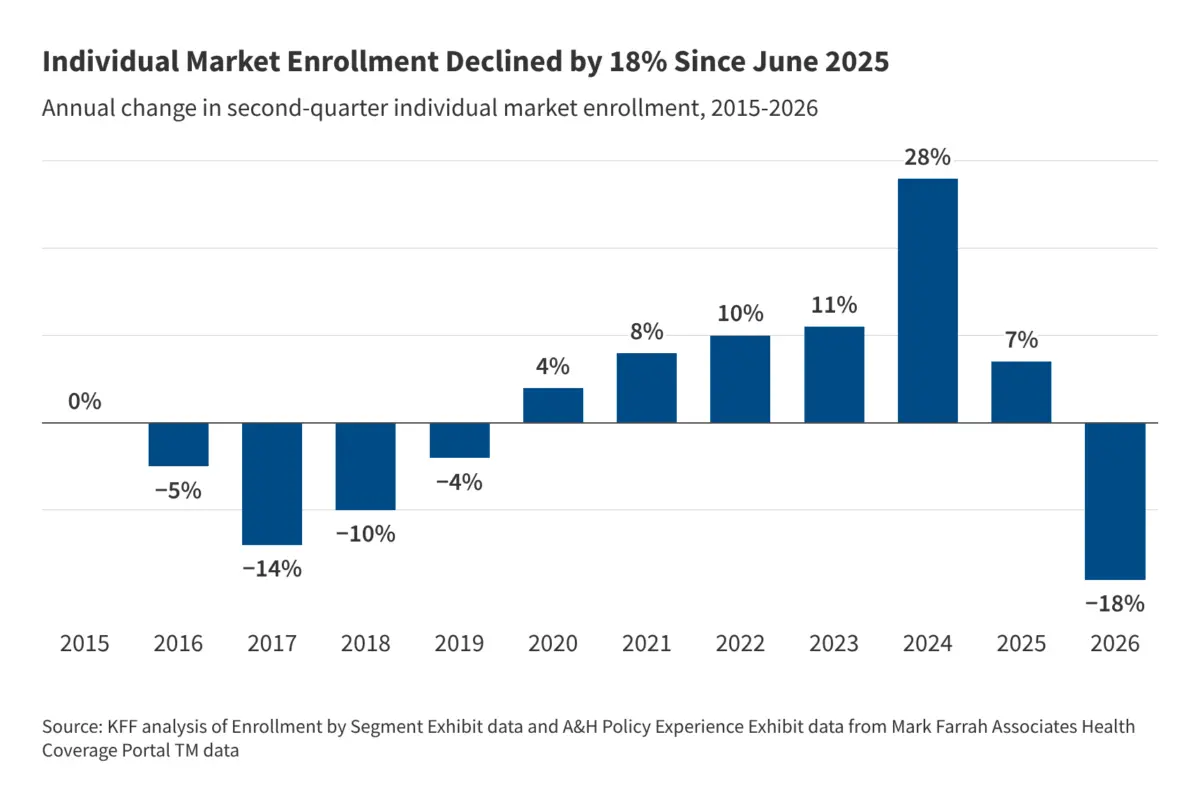
As of June 2026, the landscape of the American individual health insurance market—a vital safety net for millions of families and self-employed individuals—has undergone a seismic shift. New data reveals an 18% decline in enrollment compared to the same period in 2025, a contraction that represents the loss of over 4.6 million insured individuals. This decline, which spans both on-exchange Affordable Care Act (ACA) Marketplace plans and off-exchange policies, marks a sobering pivot in the trajectory of U.S. health coverage.
The Core Facts: A Market in Contraction
The primary driver of the individual market is the ACA Marketplace, which accounts for roughly nine out of every ten enrollees. According to the latest analysis, total enrollment in the individual market plummeted from 25.2 million in June 2025 to 20.5 million by June 2026.
This drop is not merely a statistical anomaly; it is a profound realignment following the expiration of enhanced premium tax credits. For years, these federal subsidies artificially suppressed the cost of premiums, allowing millions to afford comprehensive coverage. With those supports phased out or significantly reduced, the "sticker shock" of market-rate premiums has begun to force consumers out of the system. While 20.5 million people remain covered, the loss of 4.6 million enrollees in a single year underscores the fragility of the current insurance model.
Chronology of a Market Decline
The erosion of the individual market did not happen overnight; it followed a predictable, albeit painful, trajectory throughout the first half of 2026.
The Open Enrollment Turbulence (Winter 2026)
The decline began during the 2026 Open Enrollment Period. Initial sign-up data indicated a shortfall of 1.2 million people compared to the previous year. However, raw sign-up numbers can be misleading. In the complex world of health insurance, a "plan selection" does not always translate to "effectuated enrollment"—the industry term for a policy that is active and paid for.
The Grace Period and Retrospective Cancellations (Spring 2026)
Many enrollees who selected plans in early 2026 struggled to maintain their premium payments. Under federal regulations, subsidized enrollees benefit from a three-month grace period for nonpayment. This regulatory safeguard masked the severity of the problem for several months.
By the time the grace period for January enrollees elapsed on May 15, 2026, thousands of policies had been terminated retroactively. Consequently, February effectuated enrollment fell by 12%—from 21.8 million to 19.2 million. This retrospective data revealed that a significant portion of the "insured" population during the first quarter were actually at high risk of losing their coverage.
Sustained Erosion (Summer 2026)
The trend continued with relentless momentum. By March, enrollment had dipped by 16% year-over-year. By the close of the second quarter in June, the decline had widened to 18%. This consistent downward slope suggests that the initial shocks were not temporary blips but a sustained response to the shifting financial landscape of health insurance.
Supporting Data: The Anatomy of the Drop
The data, sourced from the Mark Farrah Associates Health Coverage Portal and cross-referenced with National Association of Insurance Commissioners (NAIC) filings, paints a grim picture.
- Geographic Variation: The decline is near-universal. Enrollment has fallen in every state across the nation, with the sole exception of New Mexico. The magnitude of these declines varies widely, suggesting that state-level policy interventions and local market competition have acted as buffers, though they have been unable to stop the bleeding entirely.
- The Off-Exchange Factor: While the bulk of the market resides within the ACA exchanges, off-exchange enrollment—plans purchased directly from insurers or brokers—has also shrunk. These plans, which do not offer federal subsidies, have faced the full brunt of rising premiums, making them increasingly inaccessible to the middle-class families who once relied on them.
- Comparison to Projections: These figures are disturbingly close to the projections released by the Congressional Budget Office (CBO), which forecasted a 25% drop in enrollment following the expiration of enhanced tax credits.
The Human Element: KFF Survey Insights
Statistical analysis often obscures the reality of those losing coverage. KFF’s Follow-Up Survey of ACA Marketplace Enrollees provides a human face to the data.
According to the survey, 17% of returning enrollees—roughly one in six—expressed low confidence in their ability to afford premiums for the duration of 2026. This lack of financial security is the leading indicator of future drop-offs. Perhaps most alarming is that 9% of those who were enrolled in 2025 reported being completely uninsured in 2026, while 22% scrambled to find alternative coverage, likely moving to lower-quality, less comprehensive plans.
Implications for 2027 and Beyond
The crisis in the individual market is likely to exacerbate in the coming year. Insurers have proposed a median premium increase of 15% for 2027, marking the second consecutive year of double-digit hikes.
The "Sicker Pool" Phenomenon
Insurance markets rely on a broad, healthy pool of enrollees to balance the costs of those with high medical needs. As healthy individuals, deterred by high premiums, drop their coverage, the "risk pool" becomes sicker. Insurers, anticipating this, raise premiums further to cover the increased medical spending, creating a "death spiral" effect where only the sickest—and most expensive—remain in the market. Insurers have already noted that they are building an additional four-percentage-point buffer into their 2027 pricing to account for this expected volatility.
Future Policy Risks
The June 2026 data is a mid-year snapshot. It does not account for plan cancellations that occurred after the second quarter or the potential for late-year nonpayment terminations. Moreover, as the fall Open Enrollment Period approaches, many Americans will face the reality of significantly higher premiums, which could accelerate the exodus from the market.
While proponents of the current system point out that enrollment remains roughly 7 million higher than it was in 2019—a 53% increase—the trend line is undeniably negative. The legislative "safety net" created by the enhanced subsidies is unraveling, and without new policy interventions, the U.S. may see a significant increase in the total number of uninsured residents.
Methodological Context
This analysis relies on rigorous data filtering to ensure accuracy. By focusing exclusively on plans with a "medical" focus and excluding specialty or ancillary benefits, the data provides a clear view of core health insurance trends. Adjustments were made to exclude the Children’s Health Insurance Program (CHIP) and to account for plans that file annually, ensuring that the 18% decline represents a true reflection of the individual market for adults and families.
As the 2026 midterm election season approaches, these figures serve as a critical backdrop for the national debate on healthcare. The data indicates that the progress made in expanding access to care is under significant pressure, and the coming months will be a defining period for the future of individual health coverage in the United States.
The question remains: Will policymakers intervene to stabilize the market, or will they allow the current trends to continue, further distancing the promise of affordable, accessible healthcare from millions of Americans? The data suggests the clock is ticking.
About the Author