In the fractured landscape of American healthcare, few entities occupy as contentious a position as the private health insurance industry. As patients grapple with skyrocketing premiums and doctors battle the bureaucratic hurdles of coverage denials, political leaders on both sides of the aisle have increasingly converged on a singular target: the health insurance company. From the halls of Congress to the kitchen tables of families across the country, the finger-pointing is relentless.
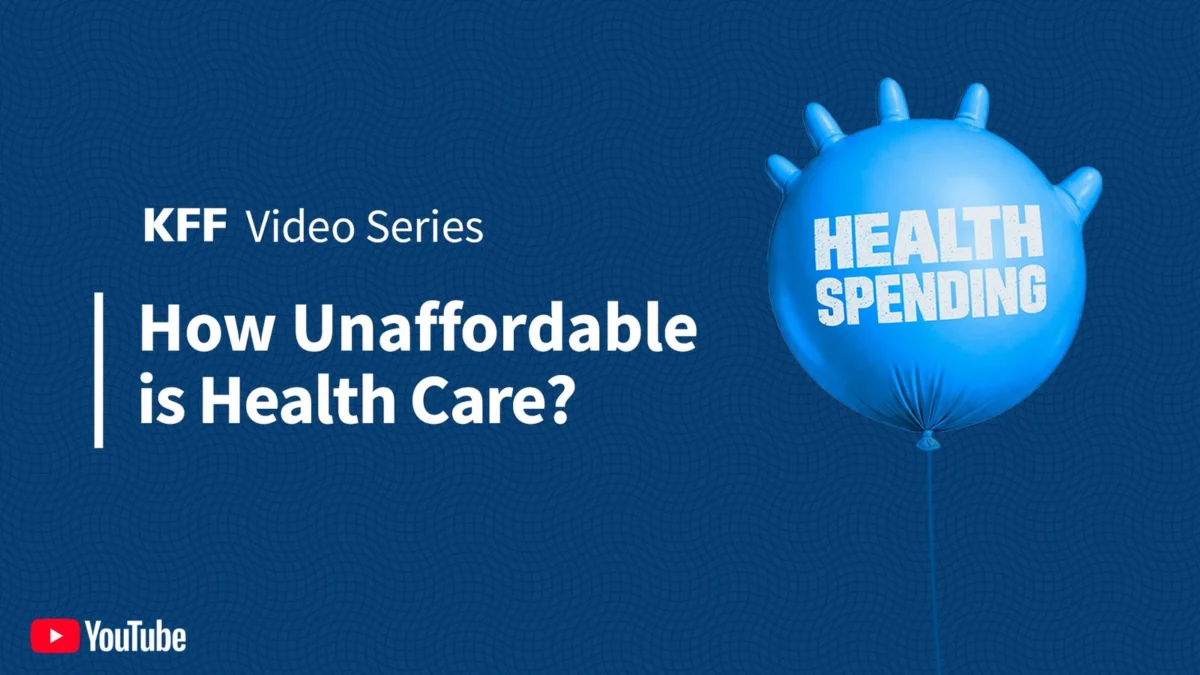
But does the data support the narrative? Is the insurance industry the primary architect of the American health system’s failures, or is it merely a lightning rod for deeper, more systemic dysfunction? To demystify these complexities, KFF (formerly the Kaiser Family Foundation) has released a comprehensive three-part video series, offering a rigorous examination of the mechanics behind rising costs, the definition of "value" in coverage, and the ethics of prior authorization.
The Core Conflict: Why Costs Are Climbing
At the heart of the debate is a simple, painful reality: healthcare in the United States is becoming fundamentally unaffordable for a significant portion of the population. The KFF analysis, which serves as the backbone of their new multimedia investigation, highlights that the drivers of rising premiums are not singular, but a complex web of market forces.
The Myth of Simple Profiteering
While critics often point to the high profit margins of major insurance firms as the sole cause of premium hikes, the reality is more nuanced. Premiums are primarily a reflection of the underlying cost of medical care. When hospitals charge more for procedures, pharmaceutical companies hike the prices of life-saving drugs, and administrative overhead swells due to a fragmented payment system, insurers must adjust premiums to remain solvent.
However, the KFF series questions whether insurers are doing enough to negotiate these costs downward. As the "middlemen" of the American system, insurance companies are theoretically positioned to act as aggressive advocates for patient affordability. The series challenges viewers to consider: if they aren’t effectively curbing the rise of medical expenses, are they justifying their role in the supply chain?
A Chronology of the Coverage Crisis
To understand how we arrived at this impasse, one must look at the evolution of the health insurance model over the last three decades.

- The 1990s: The Rise of Managed Care: As costs began to surge in the 90s, the industry shifted toward "managed care," introducing gatekeeping mechanisms like HMOs. While this succeeded in slowing cost growth temporarily, it sparked a public backlash against the perceived rationing of care.
- The 2010s: The ACA Era: The Affordable Care Act (ACA) fundamentally reshaped the landscape, mandating coverage and preventing the denial of service based on pre-existing conditions. While this improved access, it also created new financial pressures as insurers were forced to cover high-risk populations, often leading to premium volatility.
- 2020–Present: The Post-Pandemic Inflation: The COVID-19 pandemic introduced unprecedented volatility. Deferred care, burnout-driven staffing shortages in hospitals, and a surge in the utilization of high-cost specialty drugs have created a "perfect storm" for insurers, who are now passing those costs on to employers and consumers.
Supporting Data: The Value Proposition
A central theme of the KFF inquiry is the question of "value." In a functioning market, a consumer pays a premium in exchange for protection against financial ruin and, ideally, the facilitation of high-quality care.
The Administrative Burden
Data analyzed by KFF suggests that a significant portion of the premium dollar is consumed by administrative overhead—billing, marketing, executive compensation, and the complex process of claims adjudication. When consumers look at their rising monthly bills, they are effectively paying for the infrastructure that manages their care. The central question posed by the series is: does this infrastructure add value, or does it serve as a friction point that slows down medical delivery?
Prior Authorization: Blessing or Curse?
Perhaps the most polarizing tool in the insurer’s arsenal is "prior authorization"—the requirement that a physician obtain approval from the insurance company before a procedure or medication is covered.
- The Insurer’s Defense: Proponents argue that it is a necessary check against waste, preventing unnecessary surgeries or the prescription of exorbitantly expensive brand-name drugs when generics are available.
- The Patient/Provider Critique: From the perspective of the medical community, it is a "curse" that causes significant delays in treatment, contributes to physician burnout, and can, in extreme cases, result in negative health outcomes for patients who must wait for administrative approval to receive life-saving interventions.
Official Responses and Industry Stance
The insurance industry, represented by trade groups like America’s Health Insurance Plans (AHIP), maintains that they are an essential part of the solution, not the problem. Their argument rests on three pillars:
- Risk Management: Insurers claim that by pooling risk, they protect individuals from the catastrophic costs of chronic illness and emergency care.
- Negotiation Power: Insurers argue that they use their scale to negotiate lower rates with hospital systems and pharmacy benefit managers (PBMs), though critics suggest these savings are rarely passed on to the consumer.
- Regulatory Compliance: Insurers emphasize that they operate within a highly regulated environment, where the government dictates much of their coverage requirements and financial reporting, limiting their ability to drastically alter market prices.
Conversely, policy analysts like Larry Levitt, Executive Vice President for Health Policy at KFF, argue that the system is fundamentally misaligned. In his article, Are Health Insurance Companies the Reason for Our Health System’s Ills?, Levitt suggests that because the system is fragmented, no single entity is truly incentivized to prioritize patient outcomes over profit margins or cost-shifting.
Implications for the Future of Healthcare
The KFF video series is more than just an academic exercise; it is a call for transparency. The implications of the current trajectory are severe:

- For the Employer: As premiums rise, employers—who provide the bulk of private insurance in the U.S.—are increasingly shifting costs to employees through higher deductibles and coinsurance. This creates a "hidden" crisis where even those with insurance are effectively underinsured.
- For the Patient: The erosion of trust in the healthcare system is reaching an all-time high. When patients feel that their insurer is an adversary standing between them and their doctor, the entire patient-provider relationship is compromised.
- For the Policy Maker: The bipartisan frustration mentioned by KFF suggests that legislative reform is likely on the horizon. Whether this takes the form of stricter regulation on prior authorization, transparency requirements for PBMs, or more radical shifts toward universal coverage models remains the central question of the next decade.
Conclusion
As KFF’s investigative series illustrates, the health insurance industry is a mirror of the American healthcare system itself: complex, expensive, and deeply flawed. While insurers play a role in driving up costs, they are also operating within a system designed to prioritize volume over value.
Ultimately, the goal of these educational resources is to empower the public to look past the finger-pointing. By understanding the levers of the industry—the mechanics of premiums, the realities of administrative costs, and the ethics of coverage decisions—citizens can better participate in the democratic process of reforming a system that dictates the health and financial security of millions.
For those interested in exploring the data further or utilizing these resources for public discourse, KFF has made all materials, including the video series, available for educational use. The path to a more efficient, equitable health system begins with the uncomfortable, yet necessary, work of asking the right questions about who holds the power—and the purse strings—in American medicine.
For more information on the KFF video series or to request materials, contact Ann DeFabio, Senior Vice President and Chief Communications Officer at KFF.
About the Author