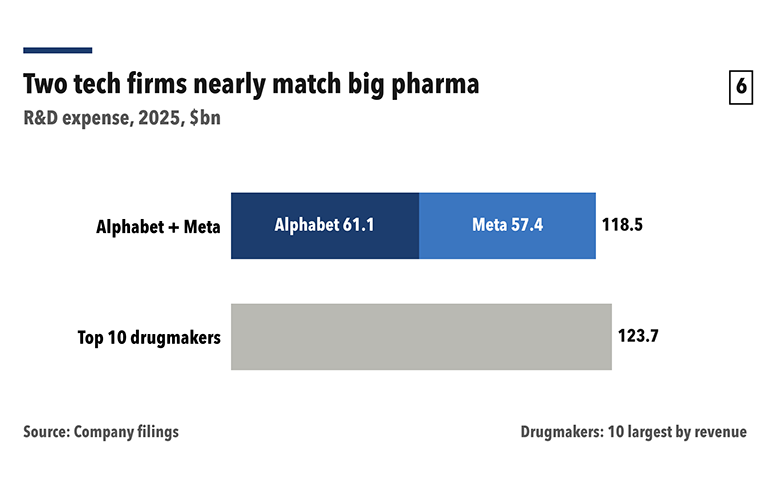
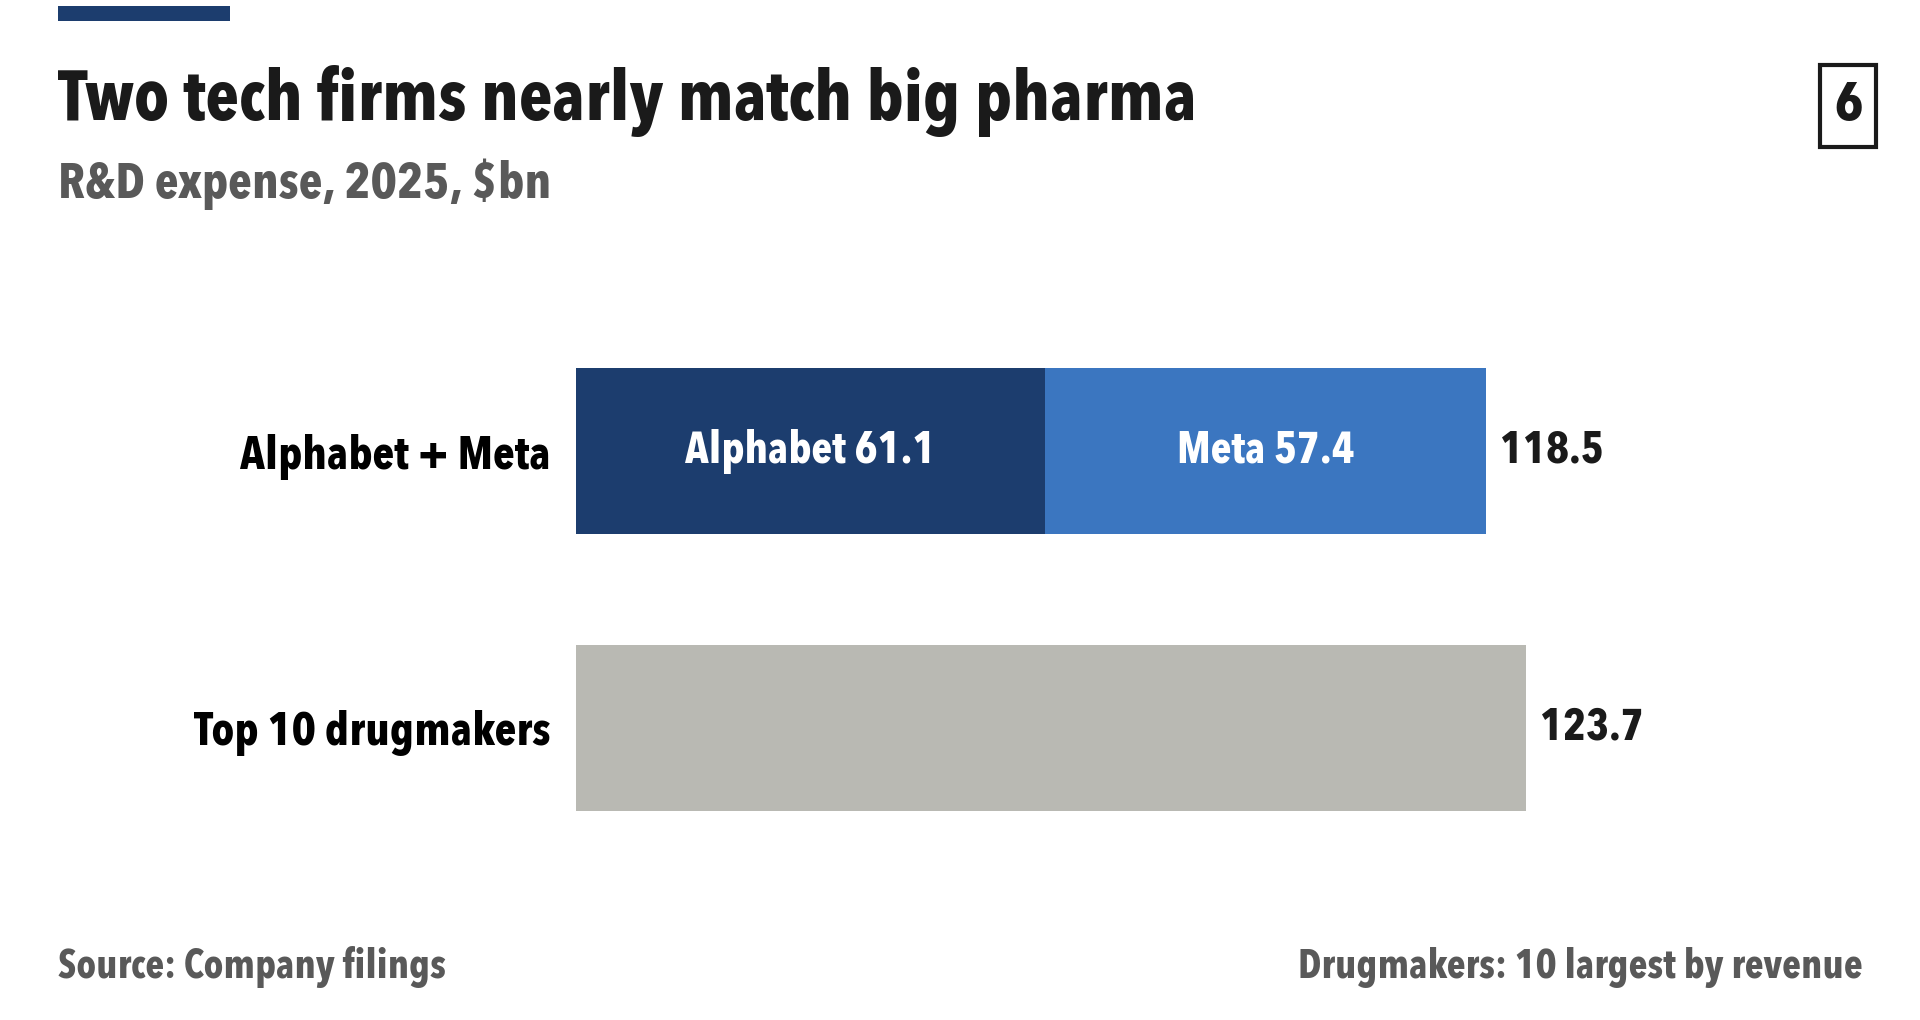
In a historic shift that signals the dawn of a new industrial era, the lines between Silicon Valley and the global pharmaceutical sector are not just blurring—they are dissolving. For 2025, Alphabet and Meta reported a combined $118.5 billion in research and development (R&D) expenditure. This staggering figure sits within striking distance of the $123.7 billion collective budget of the world’s 10 largest drugmakers, a group that includes pharmaceutical titans like Johnson & Johnson and Roche.
This massive capital infusion from Big Tech is fundamentally altering the trajectory of drug discovery. What was once a domain defined by clinical trials and chemical benchwork is rapidly evolving into a high-stakes arena of supercomputing, generative AI, and massive data-processing capabilities. As the cost of innovation in pharma continues to climb, the industry has turned to the only entities capable of matching their scale: the tech giants.
A Chronology of Collaboration and Capability
The rapid integration of AI into life sciences is a relatively recent phenomenon, but the trajectory has been exponential.
2013: The Inflection Point
A retrospective glance at 2013 reveals a world where the two industries were still operating in parallel universes. Merck & Co. spent $7.5 billion on R&D, narrowly edging out Google’s $7.1 billion. In that era, tech companies were primarily focused on software and search, while pharma focused on traditional molecular research.
2025: The Widening Gap
By 2025, the landscape had transformed beyond recognition. Alphabet’s R&D spend ballooned to $61.1 billion—nearly four times the $15.8 billion spent by Merck. This divergence in spending power reflects a broader strategic pivot: Big Tech is no longer just providing tools; they are building the infrastructure upon which modern biology is being rewritten.
2026: The Year of Implementation
The current year has served as a catalyst for large-scale adoption:
- January: Eli Lilly and NVIDIA announced a $1 billion co-innovation lab, and Genmab partnered with Anthropic to integrate agentic AI into clinical workflows.
- February: The “LillyPod” supercomputer went live in Indianapolis, allowing the company to run NVIDIA’s 550-billion-parameter Nemotron 3 Ultra model on-premises.
- March: Roche solidified its commitment to high-performance computing by bringing its total capacity to over 3,500 Blackwell GPUs.
- April: OpenAI launched GPT-Rosalind, a specialized life sciences model, while Merck signed a $1 billion alliance with Google Cloud.
- May: Isomorphic Labs secured $2.1 billion in funding, signaling investor confidence in the tech-led approach to drug discovery.
The Architecture of Innovation: Supporting Data
The shift toward "in-silico" drug discovery is supported by unprecedented hardware and software investments. Bristol Myers Squibb (BMS), for instance, is currently constructing its second NVIDIA-based supercomputer, aiming to refine the "AI factory" model for life sciences.
The economic justification for this spending is clear: efficiency. By utilizing models like those provided by Anthropic—which is currently deploying its Claude Enterprise platform to over 30,000 BMS employees—companies are attempting to collapse the timeline for drug development.
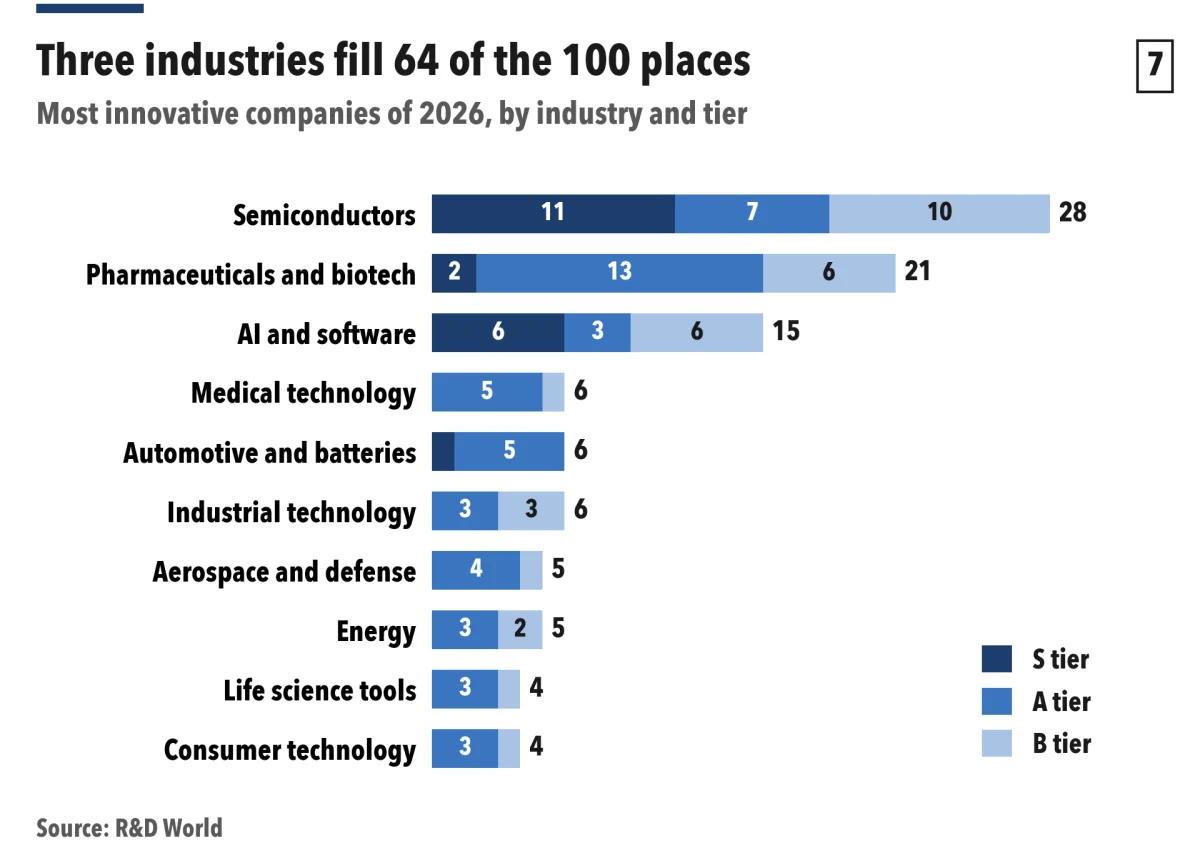
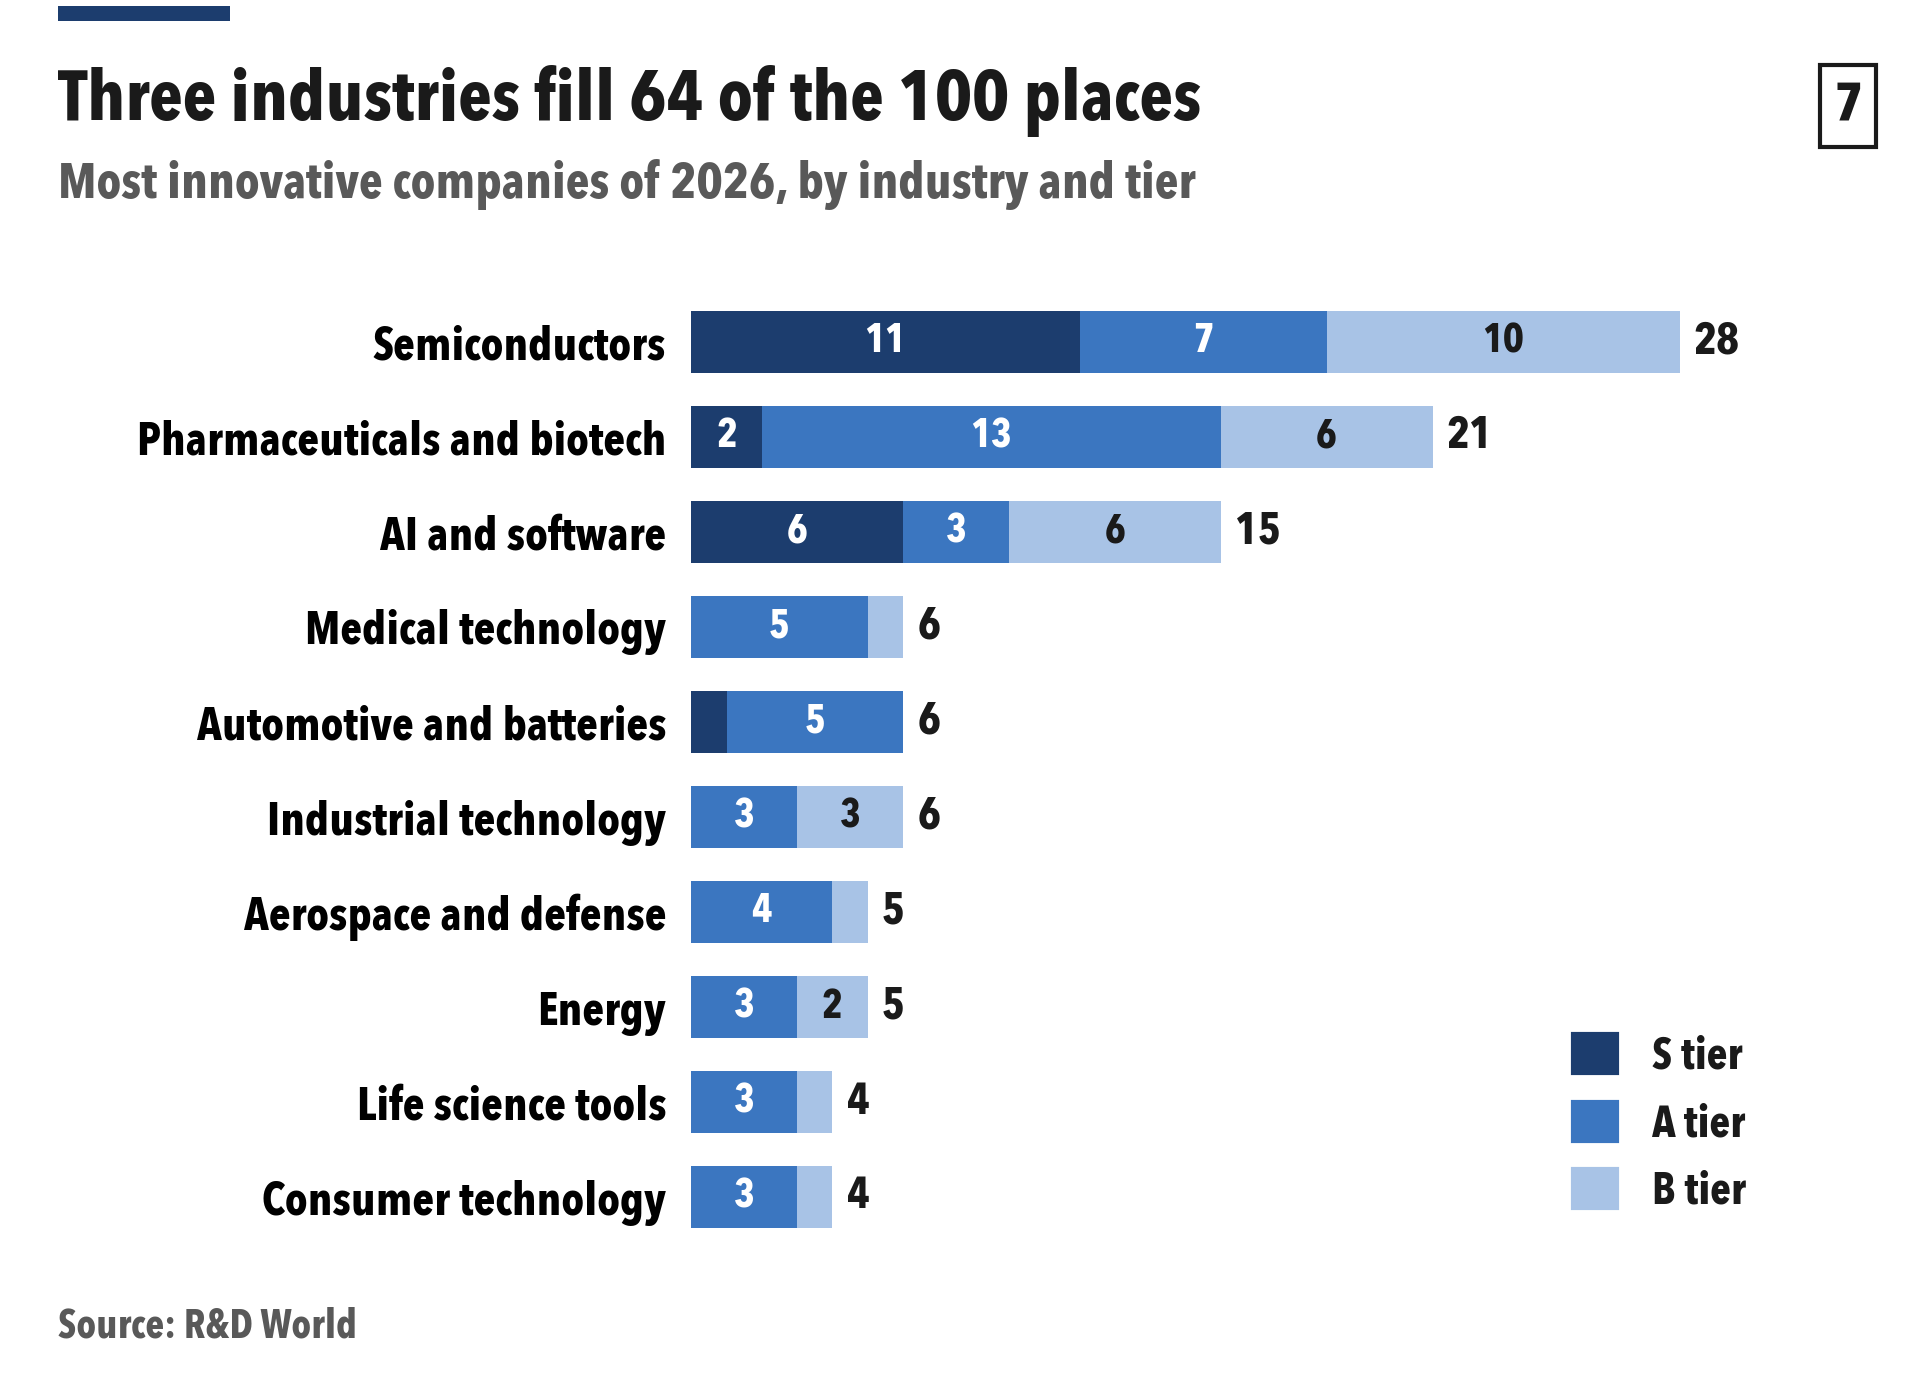
Data from the forthcoming Global R&D Funding Forecast indicates that the top 100 innovative companies globally are increasingly prioritizing AI-native infrastructure over legacy research models. This transition is not limited to software; firms like Anthropic have moved into physical biology, setting up wet labs in the Bay Area to bridge the gap between AI prediction and physical verification. While Anthropic has clarified that these labs are not solely for drug discovery, their acquisition of Coefficient Bio—a startup founded by former Genentech computational biologists—for over $400 million underscores a deeper strategic interest in the pharmaceutical value chain.
Official Responses and Strategic Alliances
The pharmaceutical industry has largely welcomed the "tech-first" approach, recognizing that the sheer complexity of biological systems requires computational power that traditional pharma firms cannot build in-house.
"We are moving from a world of trial and error to a world of design and simulation," noted a lead researcher at a major firm. The sentiment is echoed by the leadership at companies like Novo Nordisk, which has pursued an aggressive partnership strategy in 2026. After signing deals with OpenAI and AWS, the company pivoted toward Anthropic to test "Claude Science," a research workbench designed to accelerate R&D workflows.
The tech giants, meanwhile, are careful to position themselves as partners rather than competitors. Alphabet’s Isomorphic Labs, which acts as the tech giant’s dedicated drug-discovery arm, has entered into strategic collaborations with Johnson & Johnson, Lilly, and Novartis. By sharing the risks and rewards of these research ventures, both parties are insulating themselves against the volatility of the drug development lifecycle.
Implications for the Future of Medicine
The implications of this convergence are profound and multifaceted.
1. The Death of the "Trial and Error" Model
Traditional drug discovery is notoriously slow and expensive. By utilizing supercomputers and generative AI, researchers can now simulate how thousands of potential molecules will interact with a specific protein target before ever entering a physical laboratory. The case of the Lilly supercomputer co-designing a small-molecule candidate with a novel chemical fragment is a harbinger of a future where drugs are engineered rather than discovered.
2. A New Regulatory Frontier
As AI takes a more prominent role in the design and testing of therapeutics, the regulatory landscape will necessarily evolve. Regulators are currently grappling with how to validate models that are constantly learning. If an AI "designs" a drug, who is responsible for the latent biases within the training data? This question is expected to become the primary focus of the FDA and EMA in the coming decade.
3. The Democratization of Discovery
While the upfront costs of supercomputing are massive, the eventual outcome could be a lowering of the barrier to entry for smaller, AI-native biotech startups. If a startup can rent "intelligence" through a cloud provider (like Google Cloud or AWS) rather than building a physical facility, we may see a surge in innovation for rare diseases that were previously considered "financially unattractive." Anthropic’s move to run preclinical programs in neglected disease areas is a direct response to this market gap.
4. Human Capital Shifts
The pharmaceutical industry is currently witnessing a "talent drain" or, more accurately, a "talent migration." Computational biologists, data scientists, and AI engineers are now among the most sought-after employees in the life sciences. The board of directors for modern pharma companies is beginning to reflect this; the appointment of Novartis CEO Vas Narasimhan to the board of Anthropic is a clear signal that the two industries are now permanently intertwined.
Conclusion: A Collaborative Future
The figures are undeniable: $118.5 billion in tech R&D versus $123.7 billion in pharma R&D is not a coincidence—it is a convergence. As we look toward the remainder of the decade, the distinction between a "tech company" and a "drug company" will continue to fade.
The future of healthcare will be written in code. With the combined power of generative AI, massive datasets, and the deep, empirical knowledge of pharmaceutical chemistry, the speed at which we can treat, manage, and cure disease is poised for its most significant acceleration in human history. Whether this leads to a new golden age of medicine depends on the success of these massive, billion-dollar alliances, but one thing is certain: the era of the solo pharmaceutical developer is officially over.
About the Author