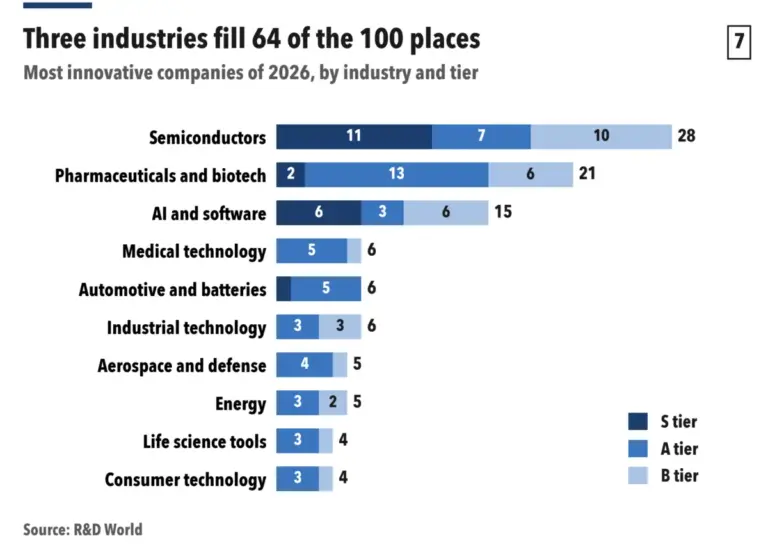
The boundary between Silicon Valley and the global pharmaceutical industry is evaporating. In a historic shift that reflects the increasing reliance on high-performance computing, artificial intelligence, and massive data architectures, the lines of demarcation between software giants and life sciences titans have become increasingly blurred.
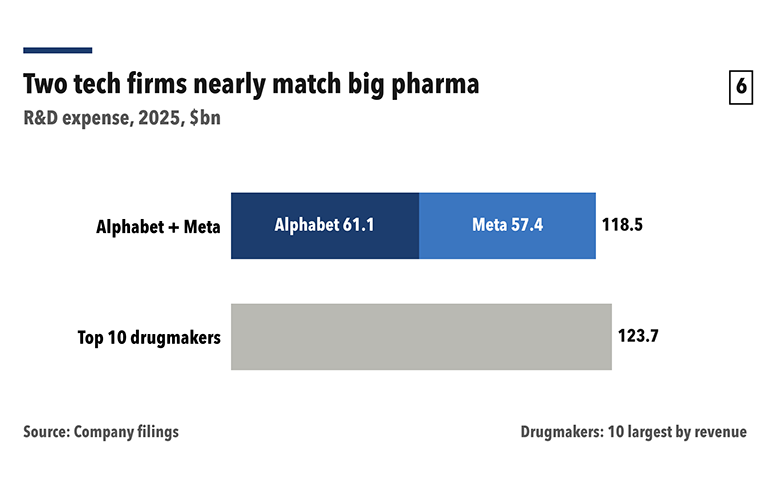
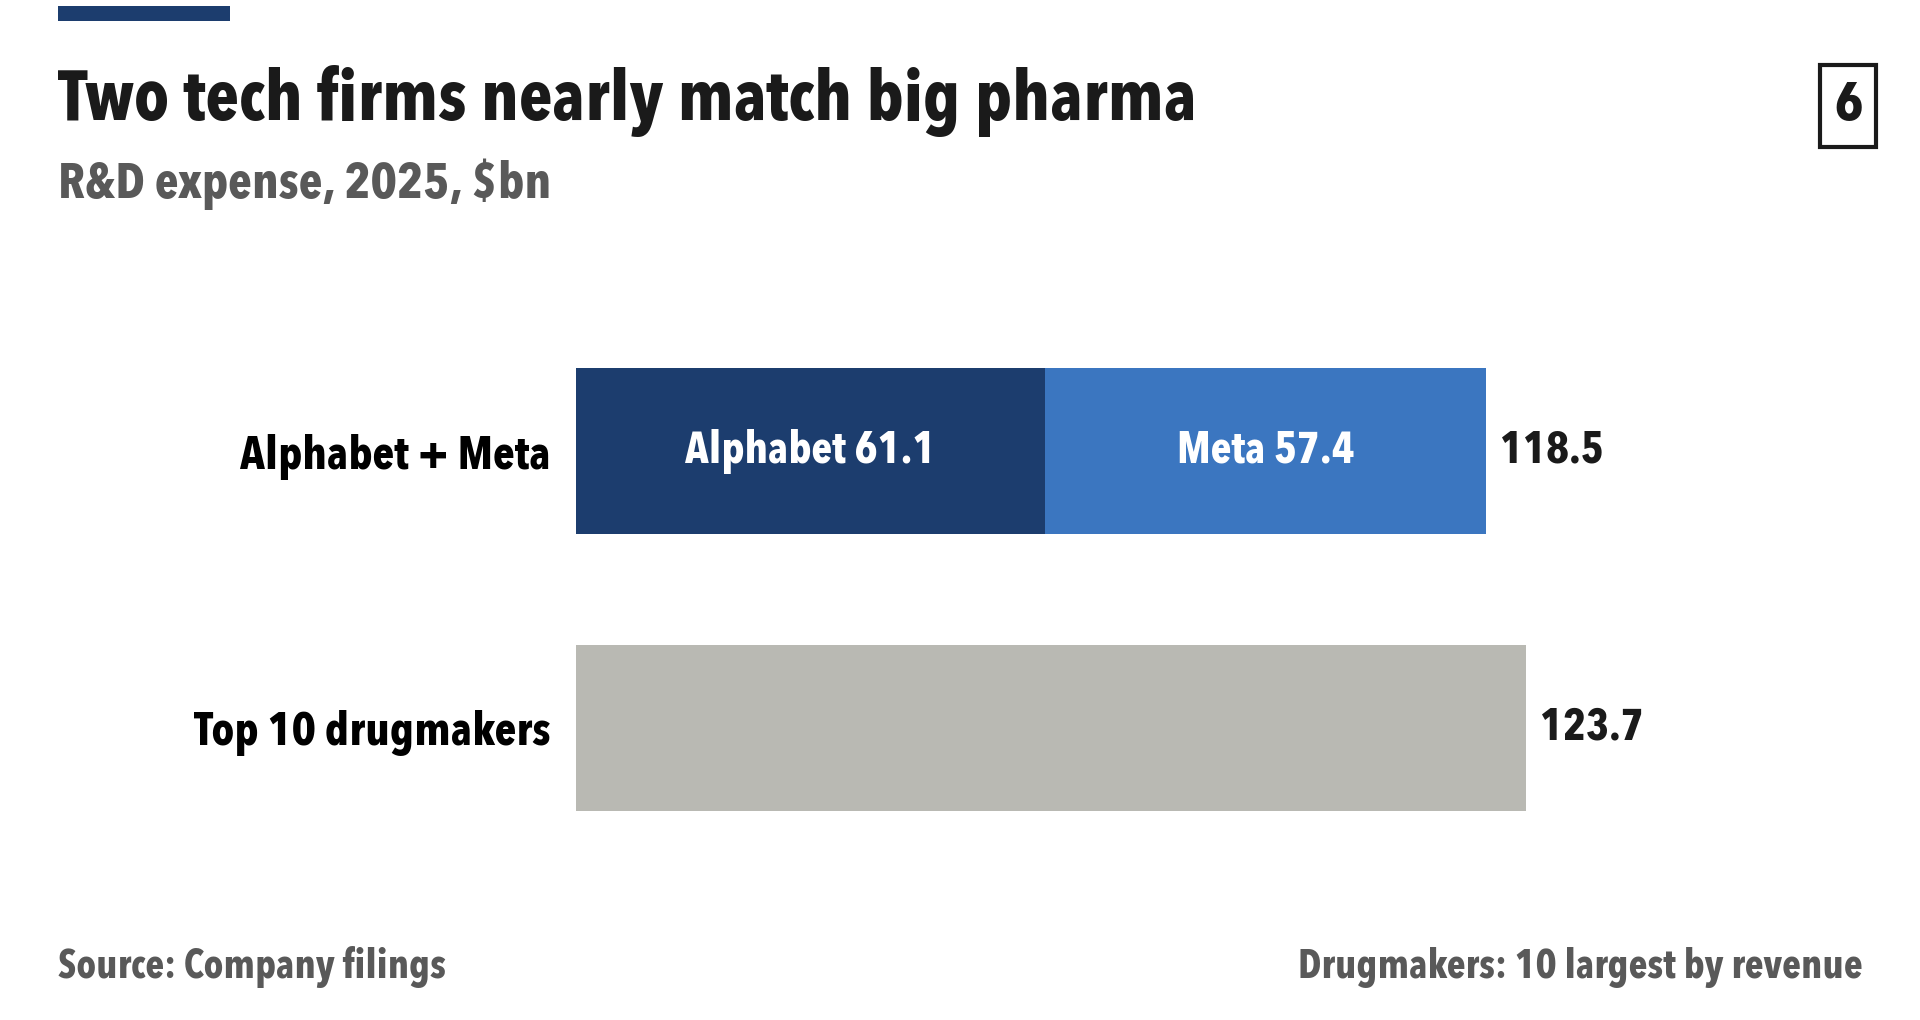
New data from 2025 reveals a striking parity in financial commitment: Alphabet and Meta reported a combined $118.5 billion in research and development (R&D) expenditure. This figure sits perilously close to the $123.7 billion collective budget of the 10 largest drugmakers by revenue—a group that includes heavyweights like Johnson & Johnson and Roche. This convergence is not merely financial; it represents a fundamental pivot in how the world’s most complex medical challenges are solved.
The Financial Paradigm Shift: A New Era of Spending
To understand the magnitude of this shift, one must look at the historical trajectory. Just over a decade ago, in 2013, Merck & Co. outpaced Google in R&D spending, with the pharmaceutical giant’s $7.5 billion budget edging out Google’s $7.1 billion. Fast forward to 2025, and the landscape has transformed beyond recognition. Alphabet alone spent $61.1 billion on R&D—nearly four times the $15.8 billion spent by Merck.
This explosive growth in Big Tech R&D budgets is fueling an "intelligence arms race" that the pharmaceutical industry is now desperate to harness. Rather than competing as adversaries, the two sectors are entering into a symbiotic relationship. Big Pharma provides the high-stakes, domain-specific data and clinical validation, while Big Tech provides the computational infrastructure, generative AI capabilities, and scalable supercomputing environments necessary to navigate the "needle in a haystack" problem of drug discovery.
Chronology: From Digital Outsiders to Core Partners
The integration of technology into the core of pharmaceutical R&D has accelerated through a series of strategic milestones over the past two years:
- January 2026: Eli Lilly and NVIDIA announce a landmark co-innovation lab in the Bay Area, backed by a $1 billion investment over five years, signaling a commitment to long-term digital infrastructure.
- February 2026: Lilly’s "LillyPod" supercomputer goes live in Indianapolis, allowing the company to run NVIDIA’s 550-billion-parameter Nemotron 3 Ultra model on-premises with no token or budget limits.
- March 2026: Roche bolsters its internal computing power, announcing the integration of 2,176 Blackwell GPUs on-premises, pushing its total capacity above 3,500 GPUs.
- April 2026: Merck & Co. solidifies its future with a multi-year, $1 billion alliance with Google Cloud, focused on "agentic" AI transformation. Simultaneously, OpenAI launches GPT-Rosalind, a life-sciences-specific model.
- May 2026: Bristol Myers Squibb (BMS) announces a major deal to integrate Claude Enterprise across its 30,000-strong global workforce. Meanwhile, Isomorphic Labs secures $2.1 billion in funding to further its drug-discovery platform.
- September 2026: Novo Nordisk enters a major drug-discovery partnership with Anthropic, marking its third significant AI collaboration of the year. Anthropic also expands its physical presence, opening a "wet lab" in the Bay Area.
The Infrastructure of Discovery: Supercomputers and AI
The modern laboratory is no longer defined solely by test tubes and centrifuges; it is defined by the FLOPS (floating-point operations per second) a company can command.
Eli Lilly’s investment in the LillyPod supercomputer serves as a bellwether for the industry. By running massive foundation models on-site, the company has bypassed the latency and cost-restraints of traditional cloud computing. This has already yielded tangible results: a foundation model on the system successfully co-designed a small-molecule candidate featuring a novel chemical fragment—a task that would have traditionally taken human chemists months or years of iterative trial and error.
Similarly, Bristol Myers Squibb is currently constructing its second NVIDIA-based supercomputer, utilizing the advanced Vera Rubin systems. This follows three years of high-intensity performance from its initial DGX SuperPOD. These investments demonstrate that leading pharma firms are no longer just "users" of tech; they are becoming "tech operators" in their own right, managing massive, on-premises server farms that mimic the architecture of a Silicon Valley data center.
Official Responses and Strategic Alliances
The "Frontier AI" labs—entities like Anthropic, OpenAI, and Google’s Isomorphic Labs—are acting as the catalysts for this transition. Their influence is increasingly visible at the C-suite level.
Anthropic’s recent acquisition of Coefficient Bio for over $400 million underscores the trend of AI companies "acquiring" biological expertise to bolster their computational models. Furthermore, the appointment of Novartis CEO Vas Narasimhan to the board of Anthropic signals a high-level convergence of leadership. This cross-pollination ensures that AI development remains tethered to the harsh, empirical realities of human biology and regulatory compliance.
The strategic agreements are also moving beyond simple software licensing. For example, the BMS agreement with Anthropic is not just for a chatbot; it is designed to position Claude Enterprise as a "shared intelligence platform" across research, manufacturing, and commercial operations. This suggests that the pharmaceutical industry is looking for a "central nervous system" powered by generative AI to manage the entire lifecycle of a drug, from molecular identification to patient distribution.
Implications: The Future of Drug Development
The implications of this $118 billion-plus investment wave are profound.
1. Compression of Timelines
The most immediate promise of this technology is the radical compression of discovery timelines. By using agentic AI to automate the screening of billions of molecular combinations, companies can move candidates into clinical trials faster than ever before. However, as noted by industry observers, there is a cautious approach regarding clinical trial acceleration due to regulatory and safety concerns.
2. Democratization of Rare Disease Research
Anthropic’s recent decision to run preclinical programs in disease areas previously deemed "financially unattractive" suggests that AI could solve the market-failure problem in drug development. If AI can lower the cost of failure in early-stage discovery, it may become viable to research rare or neglected diseases that were previously ignored by the high-cost, low-margin traditional R&D model.
3. The Risk of Over-Reliance
While the infusion of Big Tech capital and expertise is transformative, it carries systemic risks. The industry’s reliance on a handful of AI providers—NVIDIA for hardware, and Alphabet, OpenAI, or Anthropic for models—creates a new form of "vendor lock-in." Should these platforms experience downtime or algorithmic bias, the potential to stall global drug development pipelines is a significant concern for regulators and shareholders alike.
4. Talent and Cultural Integration
The influx of computational biologists, machine learning engineers, and data scientists into pharma firms creates a new corporate culture. Bridging the gap between "move fast and break things" tech culture and the "safety first" rigor of the life sciences is the primary challenge for the next decade of leadership.
Conclusion: A New Hybrid Identity
We are witnessing the emergence of a new industry vertical: the "Tech-Pharma Hybrid." As Alphabet and Meta continue to pour capital into the biological sciences, and as traditional firms like Merck and Lilly evolve into high-tech engineering powerhouses, the term "pharmaceutical company" may soon feel as outdated as the term "computer company" feels for today’s cloud providers.
The $118.5 billion spent by the tech titans in 2025 is not just a line item in an annual report; it is a down payment on the future of human health. Whether this leads to a new golden age of medicine or simply creates a more complex, tech-dependent industrial monolith remains to be seen. What is clear is that the future of drug discovery is no longer written solely in biology—it is being coded in silicon.
About the Author