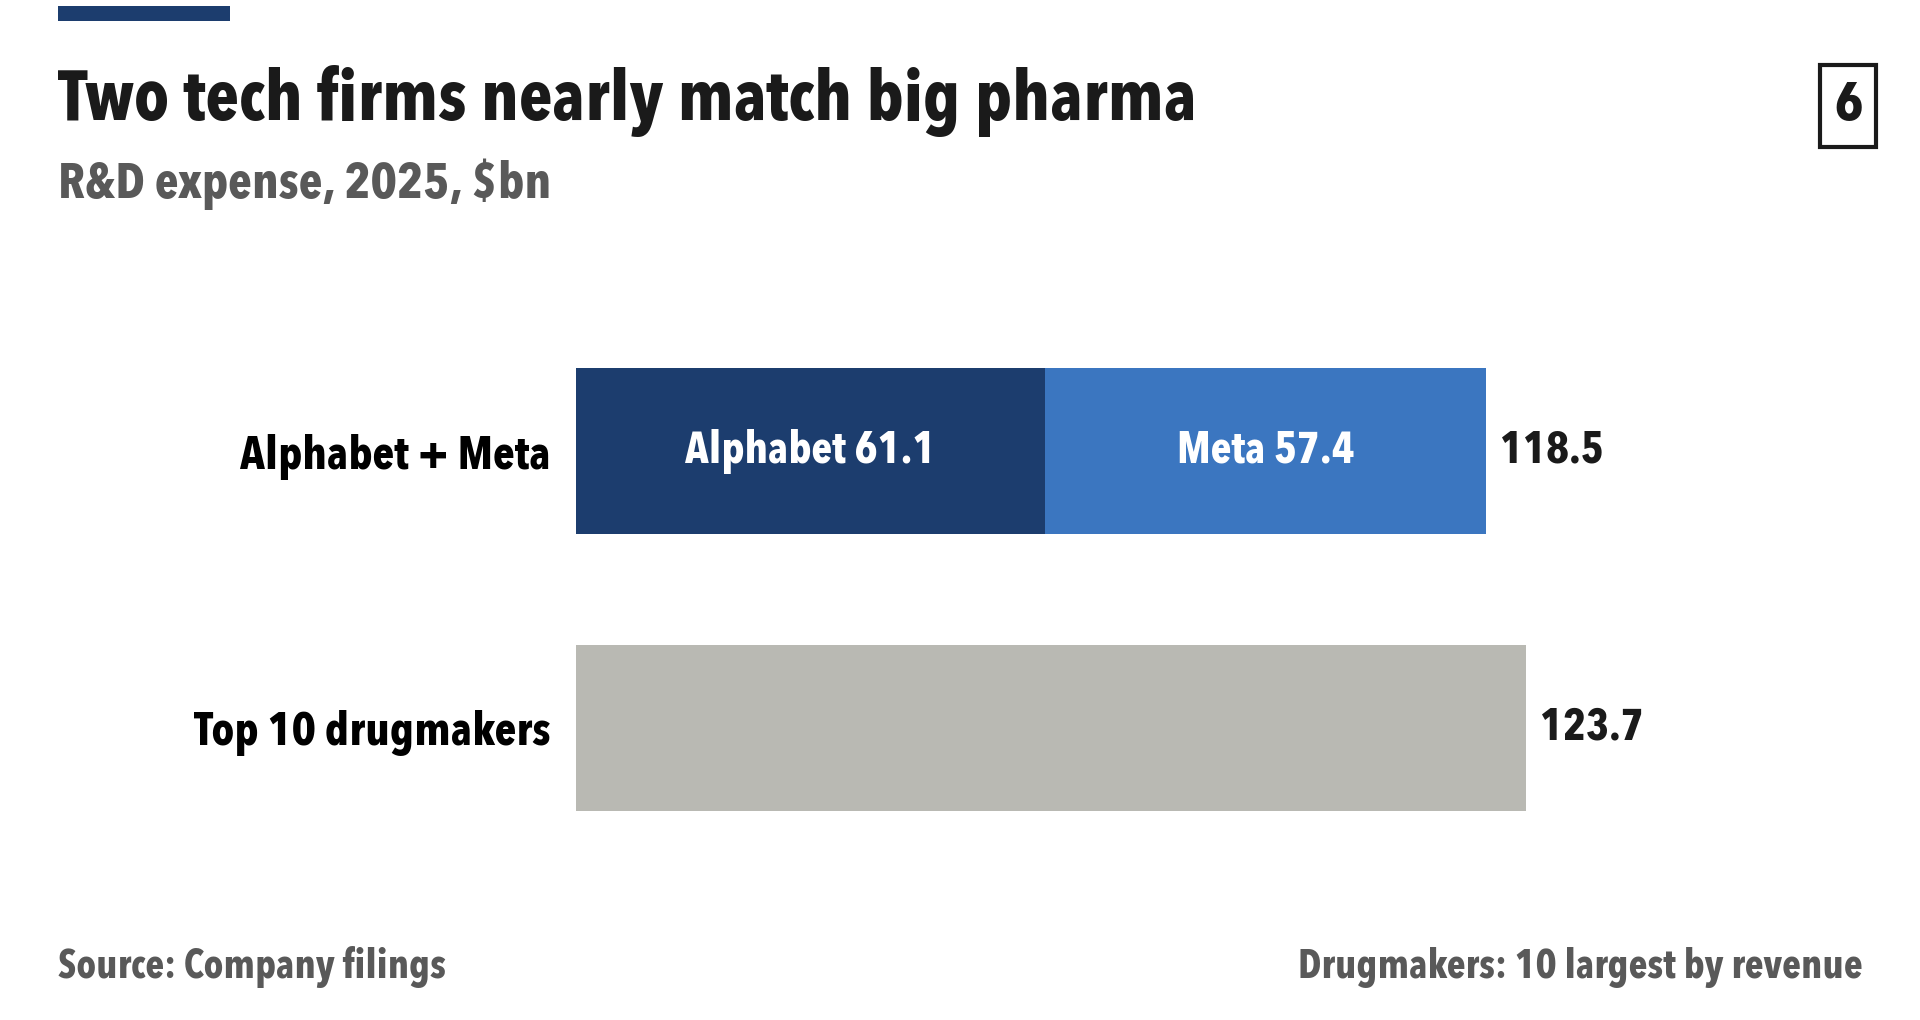
The boundary between the world’s most powerful technology firms and the titans of the pharmaceutical industry is dissolving at an unprecedented pace. In 2025, a fiscal milestone underscored this seismic shift: Alphabet and Meta reported a combined $118.5 billion in research and development (R&D) expenditure. This figure sits perilously close to the $123.7 billion collective budget of the world’s 10 largest drugmakers.
This financial parity is not merely a quirk of corporate accounting; it is a manifestation of a new era where biological discovery is increasingly treated as an information technology problem. As Big Tech’s R&D budgets continue to balloon, Big Pharma is no longer attempting to compete in isolation. Instead, the industry is aligning itself with the computational giants to survive and thrive in an age where the next breakthrough molecule may be discovered by a Large Language Model (LLM) rather than a test tube.
The Great Convergence: A Shift in Financial Power
The disparity between historical R&D spend and modern technological investment is striking. To understand the current landscape, one must look at the trajectory of the last decade. In 2013, the R&D budgets of Merck & Co. ($7.5 billion) and Google ($7.1 billion) were nearly identical. By 2025, the gap had widened into a chasm: Alphabet’s R&D expenditure surged to $61.1 billion, nearly four times the $15.8 billion spent by Merck.
This shift signifies that the primary bottleneck in drug development is no longer just the synthesis of chemicals, but the processing of vast, complex datasets. Pharmaceutical companies, historically defined by their wet labs and clinical trial networks, are now reallocating billions toward “AI factories,” supercomputing clusters, and strategic partnerships with cloud providers and frontier AI labs.
Chronology of the Tech-Pharma Integration
The integration of these two disparate industries has moved from experimental pilot programs to core operational strategy. The following timeline tracks the rapid acceleration of this relationship:
- 2013: A moment of parity; Merck and Google maintain nearly identical R&D spends.
- 2022–2024: The "Generative AI" boom. Big Pharma begins to recognize that foundational AI models could drastically shorten the drug discovery cycle.
- January 2026: Eli Lilly and NVIDIA announce a $1 billion co-innovation lab. Simultaneously, Genmab partners with Anthropic to develop agentic AI for clinical trials.
- February 2026: Lilly’s "LillyPod" supercomputer goes live in Indianapolis, allowing the firm to run 550-billion-parameter models on-premises with no token limits.
- March 2026: Roche integrates 2,176 NVIDIA Blackwell GPUs into its infrastructure, bringing its total to over 3,500 GPUs.
- April 2026: Merck & Co. solidifies its transformation with a $1 billion, multi-year alliance with Google Cloud. OpenAI launches GPT-Rosalind for the life sciences sector.
- May 2026: Bristol Myers Squibb announces the deployment of Claude Enterprise to 30,000 employees. Isomorphic Labs raises $2.1 billion.
- September 2026: Novo Nordisk enters a research collaboration with Anthropic, marking its third major AI partnership in a single year. Anthropic confirms the establishment of a physical wet lab in the Bay Area.
The Infrastructure of Discovery: From Wet Labs to Supercomputers
The physical manifestation of this partnership is the "AI Factory." Companies like Bristol Myers Squibb are currently building their second NVIDIA supercomputer based on Vera Rubin systems, while Roche has scaled its GPU capacity to unprecedented levels.
For industry leaders like Eli Lilly, the investment is yielding tangible results. Chief AI Officer Thomas Fuchs has reported that their foundation models have already co-designed a small-molecule candidate featuring a novel chemical fragment. This is not just theoretical research; it is the active engineering of new medicine. By moving these models on-premises, companies are bypassing the latency and security constraints of public clouds, ensuring that their proprietary biological data remains protected while benefiting from near-infinite compute power.
Frontier AI Labs: The New "Big Pharma"
Perhaps the most disruptive trend of 2026 is the entry of frontier AI labs—such as Anthropic and OpenAI—directly into the life sciences ecosystem.
Anthropic, in particular, has pursued a multi-pronged strategy. Beyond selling "Claude" to enterprises like BMS and Novo Nordisk, the company has begun its own internal biological research. The acquisition of Coefficient Bio for over $400 million, coupled with the hiring of former Genentech computational biologists and the appointment of Novartis CEO Vas Narasimhan to its board, signals that Anthropic is not just a tool provider—it is becoming a research entity in its own right.
While Anthropic maintains that its new wet lab is not exclusively for drug discovery, its public commitment to running preclinical programs for "financially unattractive" disease areas suggests a strategic pivot. By targeting neglected diseases, these tech giants can refine their biological models without immediately challenging the entrenched clinical portfolios of established pharma companies, all while building a massive, proprietary dataset that could eventually disrupt the market entirely.
Supporting Data: The R&D Landscape
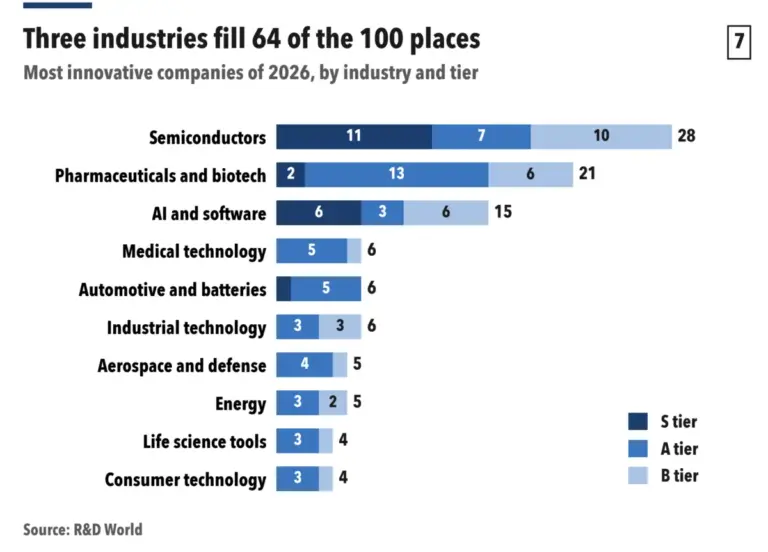
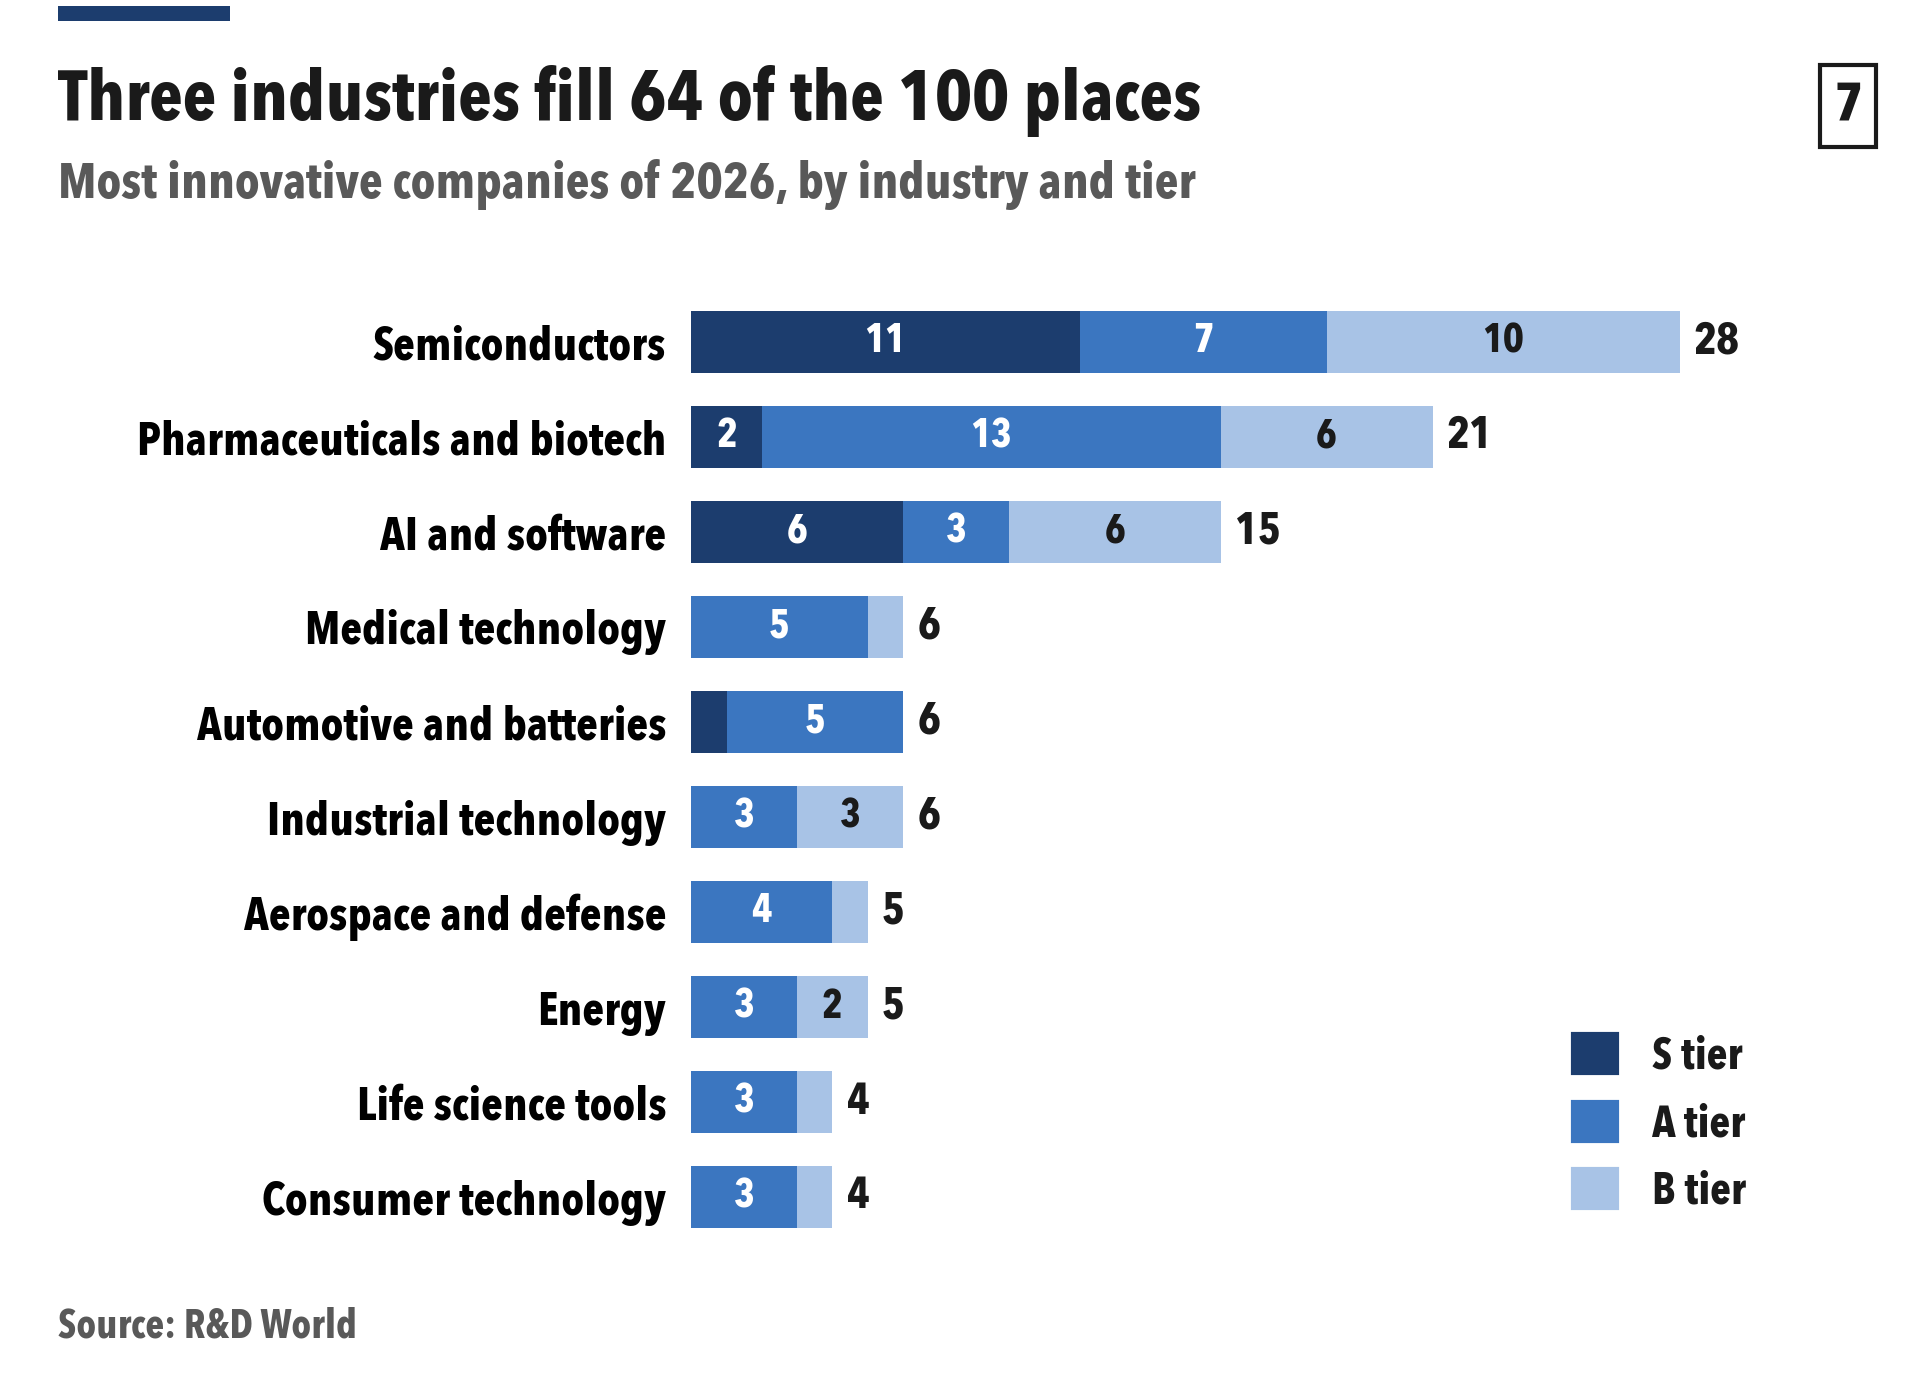
The forthcoming Global R&D Funding Forecast provides a stark look at the 100 most innovative companies across industries. The data reveals that the "Tech-Pharma" divide is no longer a matter of different goals, but different scales.
- Alphabet & Meta Combined R&D (2025): $118.5 Billion
- Top 10 Pharma Companies Combined R&D (2025): $123.7 Billion
These figures include legacy pharma R&D as well as medtech and diagnostics units. The fact that two tech companies are spending nearly the same amount as ten of the largest drug manufacturers demonstrates that the "Intelligence Economy" is now the primary engine of pharmaceutical innovation.
Official Responses and Strategic Implications
Industry leaders remain optimistic but cautious. The consensus among executives at firms like Novartis, Amgen, and Moderna is that AI is not a replacement for the scientific method but an "accelerant" that makes the impossible, possible.
However, the implications are profound:
- The Talent War: The competition for computational biologists and AI engineers is now fiercer than ever. Pharma companies are finding themselves in direct competition with the likes of Google, NVIDIA, and Anthropic for the same specialized talent.
- Regulatory Hurdles: As AI-designed drugs approach the clinic, regulators like the FDA are tasked with evaluating the efficacy and safety of molecules where the design process is largely a "black box."
- Intellectual Property Shifts: The line between a software patent and a chemical patent is blurring. As Isomorphic Labs and similar entities continue to forge collaborations, the industry must redefine who owns the "intelligence" behind a drug.
- The "Agentic" Shift: The move toward "agentic" AI—systems that can autonomously perform research, summarize clinical data, and optimize manufacturing—is set to automate the middle-management and research-assistant roles that have historically occupied thousands of man-hours in drug development.
Conclusion: The Path Forward
The marriage of Big Tech and Big Pharma is a necessity born of complexity. The sheer volume of biological data—from genomics to proteomics—has reached a point where human intuition alone is insufficient. By integrating the computational power of Silicon Valley with the clinical expertise of the pharmaceutical sector, the industry is entering a "Golden Age" of discovery.
As we look toward 2027, the focus will likely shift from building infrastructure to optimizing outcomes. The companies that succeed will not necessarily be those with the largest budgets, but those that can best integrate "Claude," "Rosalind," and custom supercomputing agents into the daily workflow of the scientist. The laboratory of the future is no longer a room filled with glass beakers; it is a sprawling, global network of GPUs and intelligent models, constantly iterating on the building blocks of life itself.
While concerns about competition and industry disruption remain, one thing is clear: the era of the solo pharmaceutical researcher is over. In its place, a collaborative, high-compute future has arrived, and it is moving at the speed of light.
About the Author