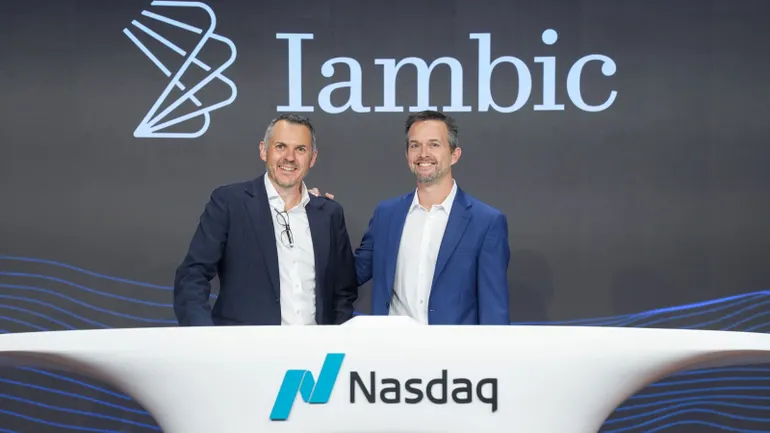
The marriage of artificial intelligence and drug discovery has long been touted as the "next frontier" of medicine, promising to collapse the decade-long, multi-billion-dollar timeline of bringing a new treatment to market. Yet, Wall Street has remained notoriously fickle. While investors have showered tech-focused AI giants with astronomical valuations, the public market’s reception of "AI-first" biotech companies has been lukewarm at best, and at times, disastrous.
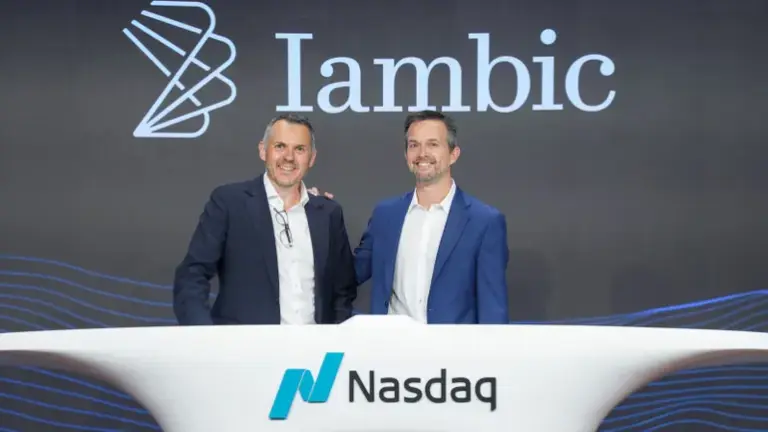
As Iambic Therapeutics makes its debut on the public markets, it enters a landscape littered with the wreckage of its predecessors. With a $150 million IPO haul and a strategy that prioritizes clinical execution over algorithmic hype, the company is attempting to prove that the problem with AI-driven drug discovery wasn’t the technology itself, but the maturity of the companies wielding it.
The Ghost of IPOs Past: A Cooling Market for AI Biotech
The skepticism surrounding Iambic is not born of a vacuum. It is a direct reaction to the performance of first-generation AI drug developers. Consider the case of Exscientia, a pioneer in the field that saw its market value evaporate as its shares plummeted roughly 80% from their debut price. The eventual capitulation—a merger with rival Recursion Pharmaceuticals in 2024—served as a stark warning to the sector.
Recursion itself has struggled significantly. Having initially listed its shares at $18, the company has faced a grueling climb, with its stock price recently hovering in the single digits. This trend has created a "show me" environment for investors. They are no longer buying the promise of a "platform"; they are demanding the tangible results of a pharmaceutical company.
Iambic Therapeutics, founded in 2019, has spent the last five years building a war chest of nearly half a billion dollars through private funding rounds backed by heavyweights like Nexus, Abingworth, and Catalio Capital Management. Its recent $150 million IPO, while modest by some standards, represents a deliberate strategy to balance technological ambition with financial pragmatism. As of late Friday, the stock was trading around $24.50—a gain of more than 50% from its offering price—but the true test of investor confidence lies in the long-term runway.
Chronology of a Tech-Bio Evolution
To understand Iambic’s positioning, one must look at its rapid ascent within the competitive landscape of machine learning-enabled discovery:
- 2019: Iambic Therapeutics is founded with a focus on integrating AI directly into the iterative loop of molecular design and clinical testing.
- 2022-2023: The company hits a key milestone by advancing its lead candidate, IAM1363, into Phase 1 clinical trials in under two years—a speed that traditionally takes traditional biotech firms much longer to achieve.
- 2024: Iambic signs high-profile collaborations with industry titans including Takeda, AbbVie, and Bayer. These deals serve as both non-dilutive funding and third-party validation of their proprietary AI models.
- October 2026: The company successfully prices its IPO, raising $150 million, and emphasizes a strategy focused on "clinical inflection points" rather than pure-play tech speculation.
Bridging the Gap: Tech vs. Medicine
The central tension in the AI-drug sector is the disconnect between "tech-forward" investors, who prioritize software scalability, and "life-science" investors, who prioritize clinical data. Tom Miller, co-founder and CEO of Iambic, believes the key to the company’s success lies in refusing to pick a side.
"If you have a pure life science thesis, this is a company that excites you because of the medicines," Miller told BioPharma Dive. "If you have a pure tech thesis, this is a company that excites you because of the underlying technologies. Making sure that we build a company that can connect those dots and bring in that broader set of investors is an important part of our journey."
Miller’s approach is a direct response to the "hype cycle" that has characterized the AI sector. While some executives in the broader AI space—such as the leadership at Anthropic—have made bold claims about curing all diseases within a decade, Iambic has maintained a more disciplined stance. By focusing on the molecule as the primary unit of success, Iambic aims to de-risk its platform.
The Strategy of Partnerships as Validation
One of the most defining characteristics of Iambic’s business model is its aggressive partnership strategy. With roughly eight major collaborations signed over the past two years, the company has effectively crowdsourced its validation process.
"Iambic has never done it just for the logos on the slide," Miller asserts. Instead, the company views these partnerships as a way to "stress-test" their platform across diverse therapeutic areas, including neurology, immunology, and metabolic disease. By embedding Iambic’s platform into the pipelines of pharmaceutical giants like AbbVie and Bayer, the company gains access to deep domain expertise that it then feeds back into its own wholly-owned pipeline.
This symbiotic relationship serves two purposes:
- Revenue Efficiency: It provides the company with a strong cash position, allowing them to remain disciplined with their IPO sizing and avoid the "megaround" trap that has left other firms overvalued and under-performing.
- Platform Versatility: It proves that their AI models are not limited to one specific protein target or oncology subset, but can adapt to the complex challenges of various therapeutic modalities.
The Path Forward: Clinical Inflection Points
Looking ahead to 2027, Iambic is positioning itself to initiate registrational trials for its lead candidates. With over 100 patients’ worth of data already in hand for its HER2-inhibitor, the company believes it has the "clinical conviction" necessary to satisfy a skeptical market.
The broader market, however, remains volatile. As reports circulate of firms like Isomorphic Labs (a subsidiary of Alphabet) discussing valuations in the tens of billions, the pressure on smaller, public-facing AI drug companies to justify their worth is intensifying.
Miller remains unfazed by the valuation gap between private "AI giants" and public biotech firms. "We’re happy to go AI model to AI model, we’re happy to go partner to partner, with any company that you’ve mentioned," he says. "But we’re also happy to go molecule to molecule in terms of real-world clinical development."
Implications for the Industry
The success or failure of Iambic Therapeutics will likely serve as a bellwether for the "AI 2.0" era of drug discovery. If the company can successfully translate its algorithmic insights into approved, marketable drugs, it will validate a business model that combines the agility of a software company with the regulatory and clinical rigor of a legacy pharmaceutical firm.
However, if Iambic fails to clear the high bar set by the public markets, it may signal a fundamental shift in how Wall Street values AI in biotech. The industry is moving away from the era of "platform-as-a-product" and into an era of "data-driven execution."
Ultimately, the lesson of Iambic is simple: in the high-stakes world of human health, the algorithm is only as good as the clinical outcome it produces. Whether Iambic can maintain its "execution maturity" while operating under the scrutiny of the public markets remains the most compelling story in the biotech sector today. For now, the company has the cash, the partnerships, and the data to prove its thesis. The only thing left for Iambic is to deliver on the one thing that matters most: the medicine.
About the Author