The biotechnology sector in 2026 has entered a period of extraordinary capital concentration, defined by a "flight to quality" and an unyielding obsession with high-impact technological platforms. As the industry navigates a complex macroeconomic environment, the data from the first eight months of the year reveals a clear trend: investors are placing massive, concentrated bets on companies that can combine biological innovation with cutting-edge computational power.
The Vanguard of Private Capital
By one conventional measure of financing, Alphabet-controlled Isomorphic Labs would stand alone at the pinnacle of the industry. Having secured a staggering $2.7 billion in external financing—bolstered significantly by a $2.1 billion Series B round announced in May—the company represents the gold standard of AI-driven drug discovery. However, the true story of the 2026 private biotech market lies in the companies that remain independent.
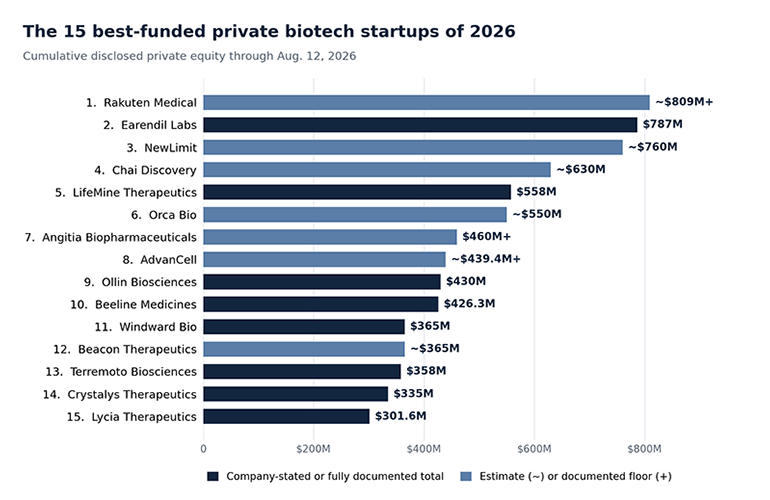
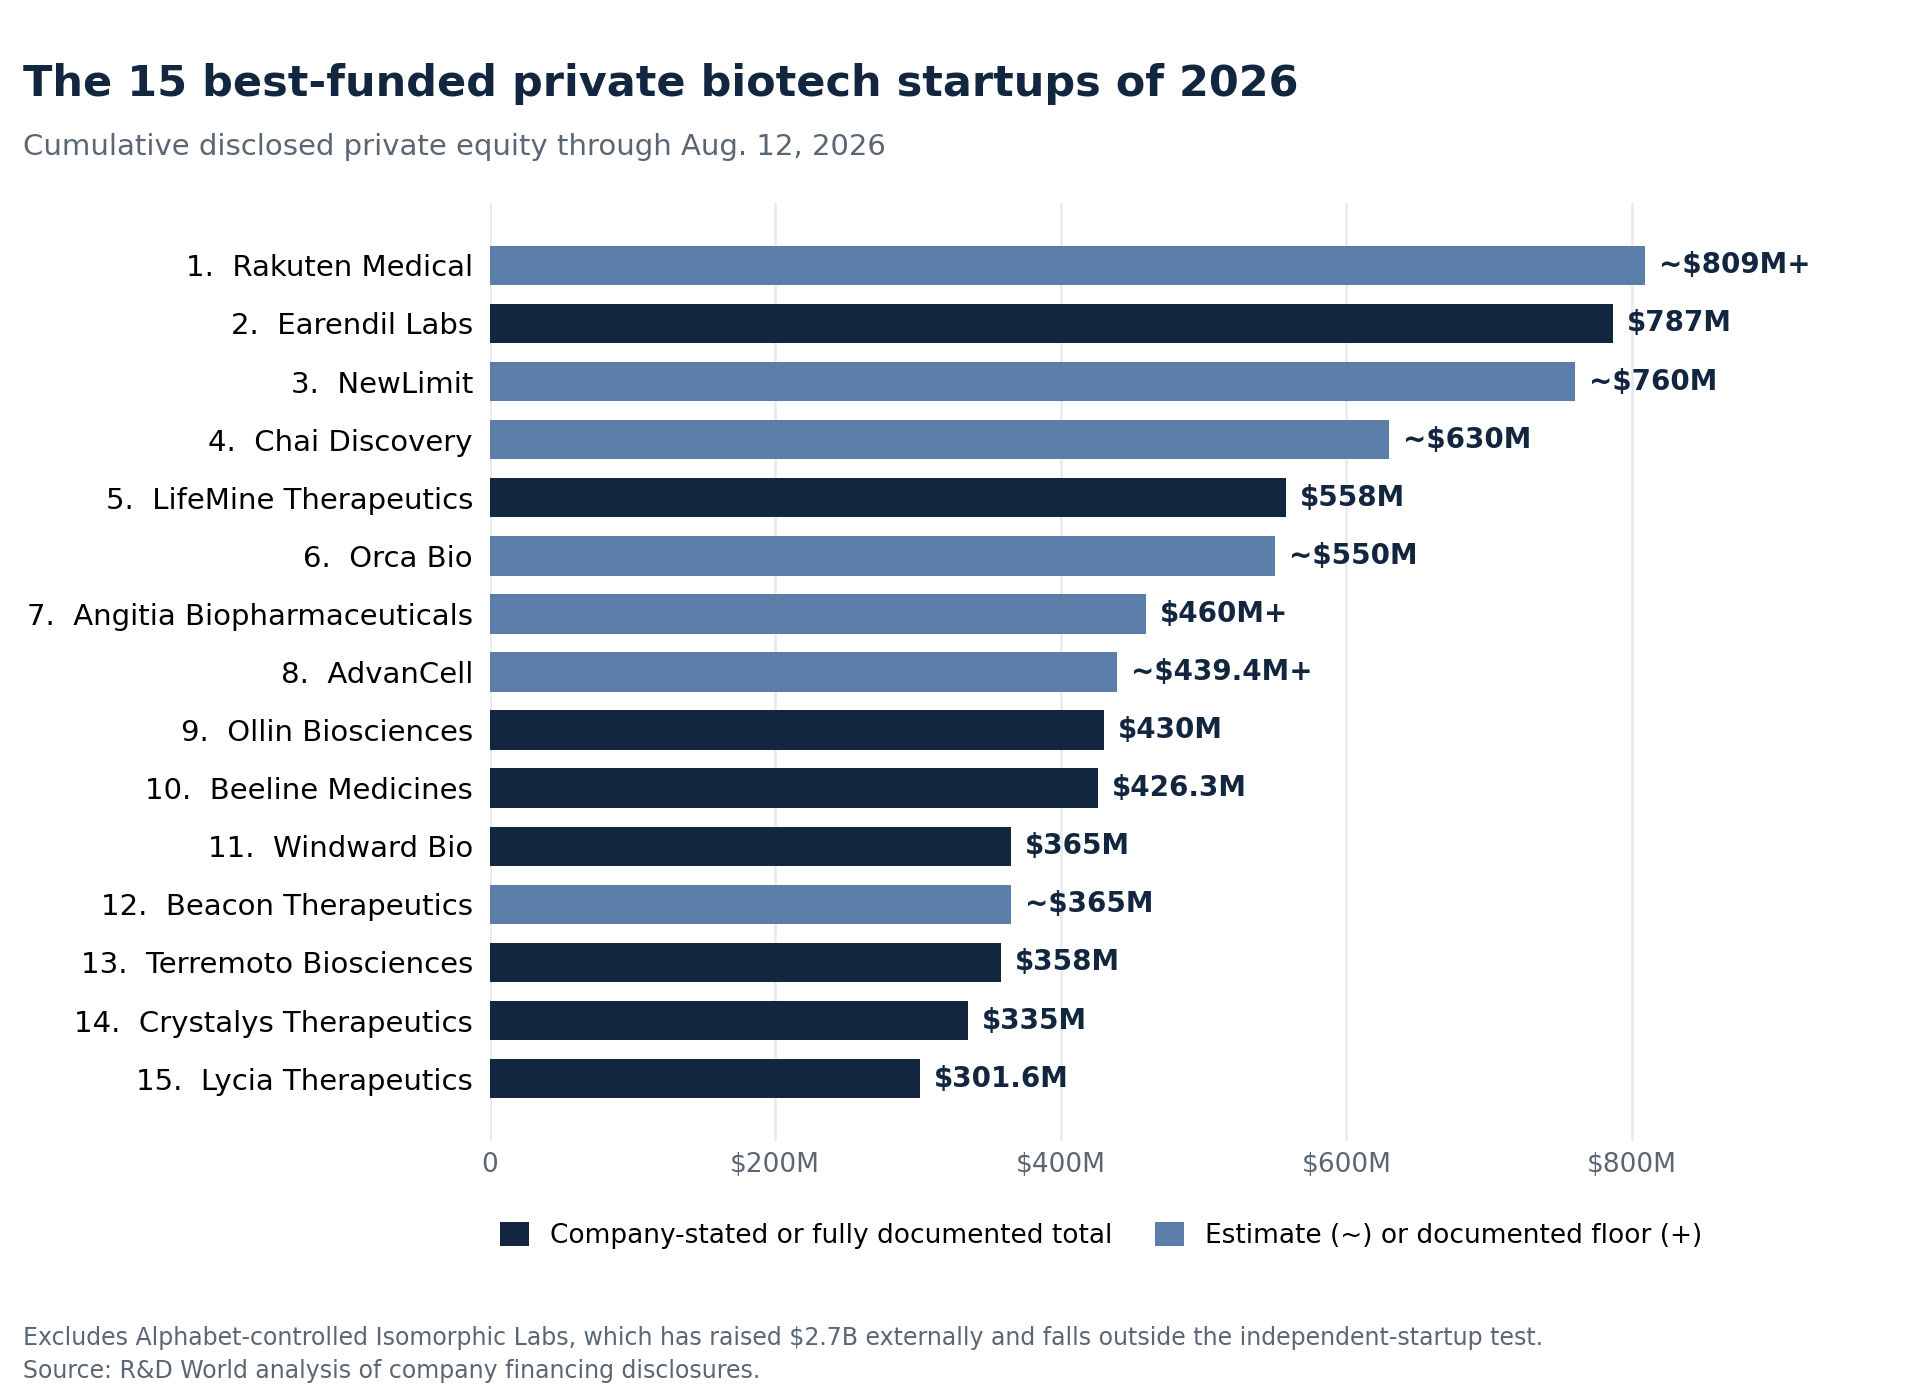
Excluding corporate subsidiaries like Isomorphic Labs, which remains under the 75% control of its parent company, the title of the best-funded independent biotech goes to Rakuten Medical. Having successfully closed an oversubscribed $100 million Series F in January, the company has now amassed over $809 million in disclosed private funding. Rakuten’s continued independence and its leadership in the field of photoimmunotherapy signal that traditional, high-growth clinical-stage companies still command significant market confidence.
Following closely in the top three are Earendil Labs and NewLimit. Earendil’s $787 million total, solidified by a massive March financing round, underscores the aggressive pursuit of AI-driven biologics. Their strategic partnership with Sanofi, potentially valued at $2.56 billion, serves as a blueprint for how private startups can leverage capital to secure long-term validation from Big Pharma. Simultaneously, NewLimit continues to capture the imagination of the venture capital community; its $435 million Series C in June—backed by heavyweights like Founders Fund and Khosla Ventures—highlights the growing interest in longevity medicine and epigenetic reprogramming.
Chronology of a High-Stakes Year
The first half of 2026 was marked by a series of rapid-fire, high-dollar financing rounds that reshaped the leaderboard.
- January: The year opened with a flurry of activity. Rakuten Medical set the pace with its $100 million Series F, followed closely by Orca Bio’s $250 million Series F. By January 9th, AirNexis Therapeutics had already made a massive entry with a $200 million Series A.
- February–April: As the market warmed, companies like Angitia Biopharmaceuticals ($130M Series D) and Terremoto Biosciences ($108M Series C) reinforced the trend of mid-to-late stage companies securing capital to push assets through the clinical pipeline.
- May–June: This period saw the "mega-rounds." NewLimit’s $435 million haul in June and the emergence of Bionyra Pharma with a $165 million Series A signaled that investors were willing to back both established platforms and ambitious new ventures.
- July–August: The summer brought further consolidation. Chai Discovery’s $400 million Series C, its third round in under a year, proved that investors are willing to double and triple down on firms with proven molecular design technology. LifeMine Therapeutics rounded out the summer with a $188 million Series E, aimed at accelerating the clinical development of its lead organ-transplant asset, LIFE-001.
Supporting Data: Modality Trends
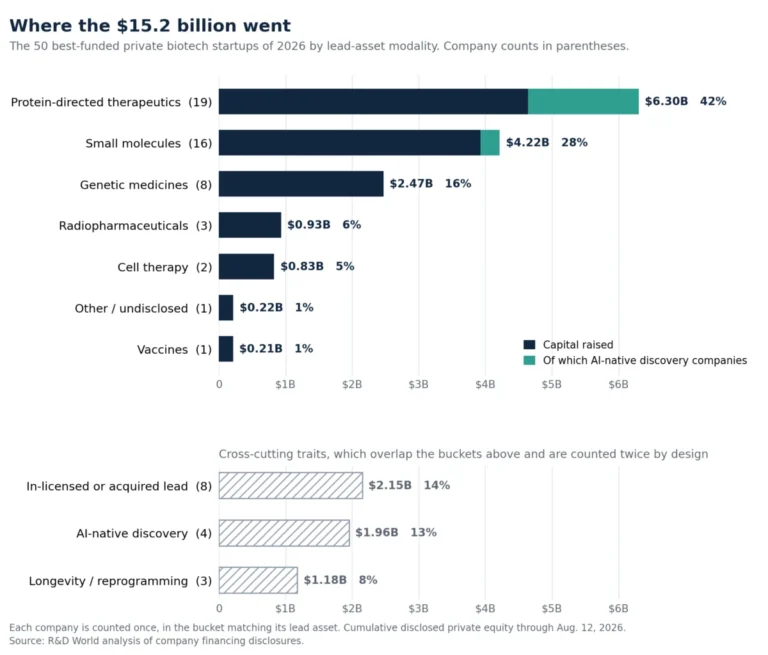
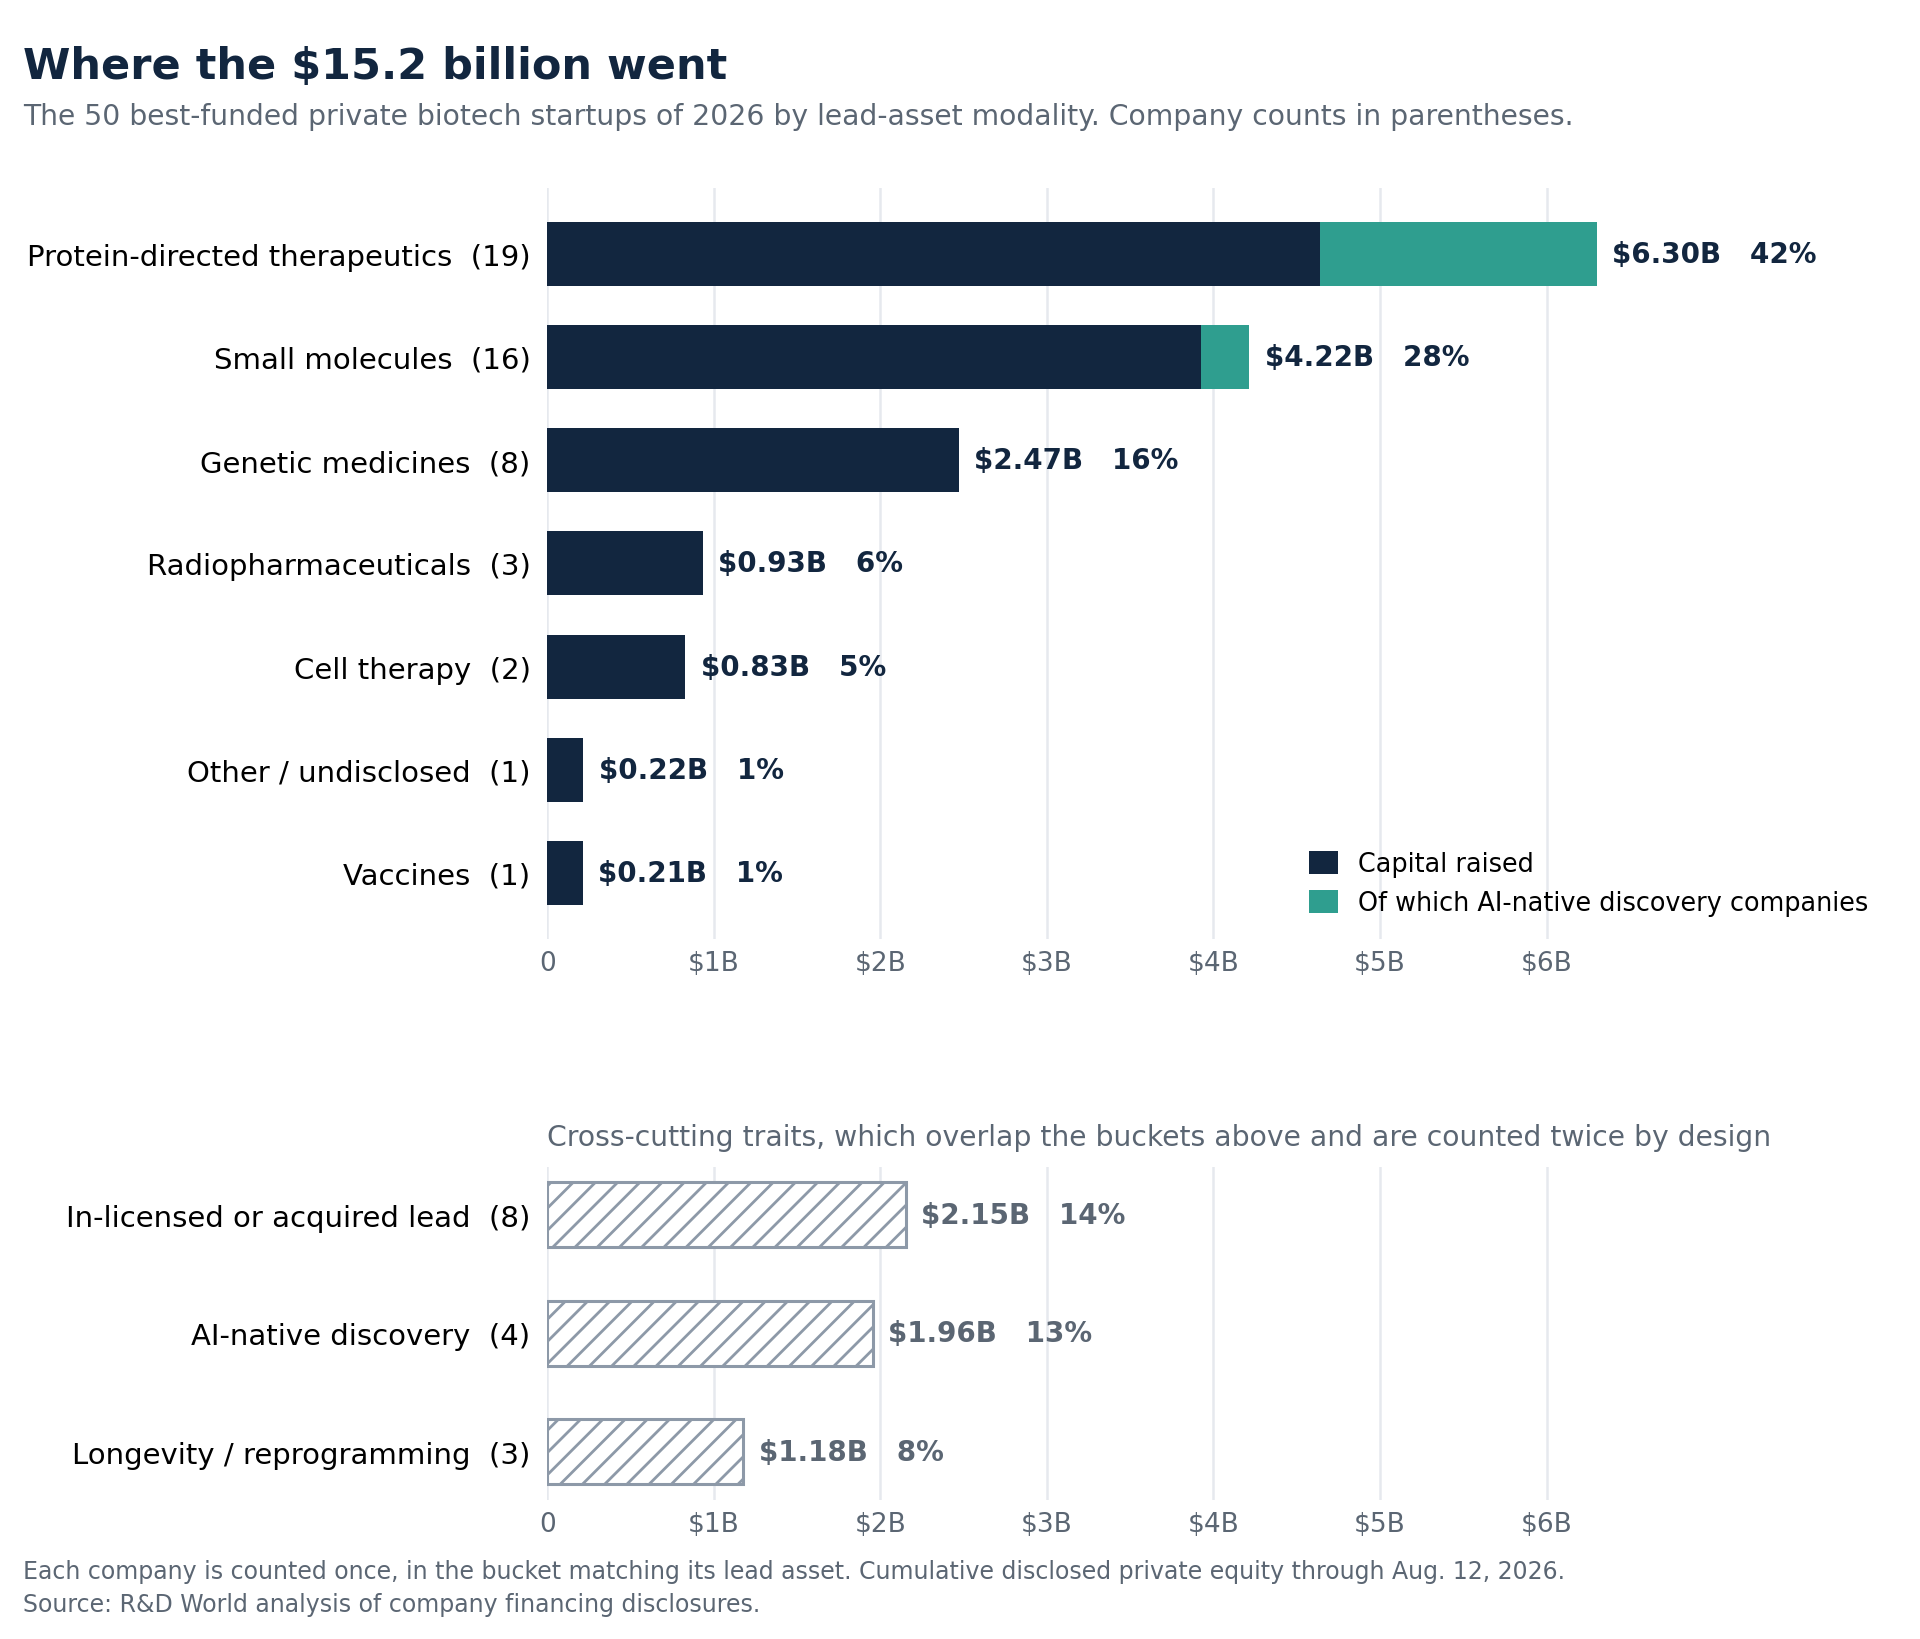
When we analyze the $15 billion in aggregate capital distributed among the top 50, clear thematic "buckets" emerge.
The Protein Dominance
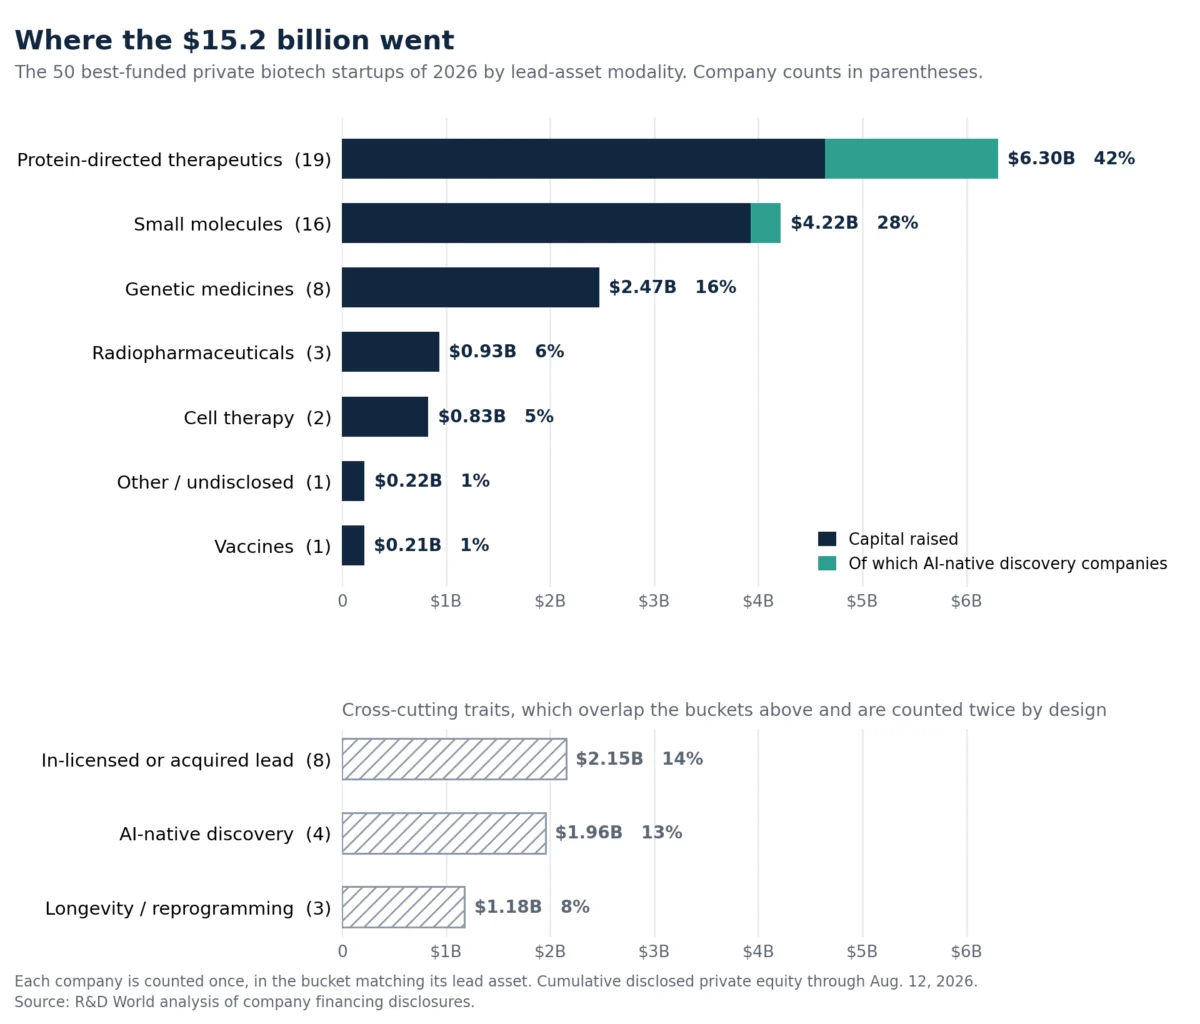
Protein-directed medicine stands as the undisputed king of the 2026 landscape. Nineteen of the top 50 companies are focused on antibodies, multispecifics, ADCs (antibody-drug conjugates), peptides, or protein degraders. Together, these firms account for $6.3 billion—or 42% of the total capital on the list. This dominance reflects a maturation of the field; investors are no longer just looking for "novel" modalities but are funding the refinement of established ones to achieve greater specificity and lower toxicity.
The Genetic Medicines Gap
Genetic medicines, while still a major pillar of the biotech ecosystem, currently trail protein-focused firms. With 11 companies accounting for $3.5 billion, the sector is experiencing a period of clinical rigor. The focus has shifted from the initial hype of gene editing to the complex challenges of delivery and durability.
The Rise of Radiopharmaceuticals
Radiopharmaceuticals have emerged as a dark horse in the race for capital. With $934 million flowing into just three key players—AdvanCell, Full-Life Technologies, and Ratio Therapeutics—the sector is proving that targeted alpha and beta therapies are highly attractive to both investors and potential acquirers.
The AI-Native Slice
Perhaps most surprising is the composition of "AI-native" companies. While AI is used by nearly every firm on the list to some degree, only four companies identify AI as the absolute center of their pitch. These firms account for $1.96 billion (13%) of the capital. This suggests that the "AI-in-a-box" era is ending; the market is now favoring companies that use AI as a tool for a specific biological goal, rather than companies selling the AI itself.
Perspectives from the Frontlines
The industry’s leadership remains cautiously optimistic. When speaking with investors and executives, the sentiment is consistent: "Capital is available, but it is not free."
Companies that have successfully navigated this year’s funding environment share a common trait: a clear path to commercialization or a high-value clinical inflection point. The success of firms like Chai Discovery, which has successfully struck partnerships with industry giants like Pfizer, Lilly, and Novartis, demonstrates that the "independent" label does not mean "isolated."
"We are seeing a trend where the best-funded companies are those that act like mid-sized pharmaceutical firms before they even enter the clinic," notes one veteran analyst. "They are building manufacturing infrastructure, securing supply chains, and entering into multi-billion dollar co-development pacts with the giants of the industry before they have even reached Phase 2."
Implications for the Future of Drug Discovery
The 2026 data points toward a profound transformation in how medicines are built.
- The Death of the "Stealth Mode" Startup: The scale of the top 50 financings suggests that the era of quiet, long-term stealth research is waning. Investors want to see capital put to work immediately, which requires massive initial cash injections to scale operations and talent acquisition.
- Platform Convergence: The lines between "platform companies" and "pipeline companies" are blurring. The top-funded firms are now hybrids: they use a proprietary technology platform to generate a pipeline, but they also use the platform to generate non-dilutive revenue through pharma partnerships.
- The Geographic and Structural Shift: While not explicitly detailed in the top-line funding numbers, the geographic distribution of these firms suggests that the hub-and-spoke model of drug development is evolving. With firms like LifeMine and Rakuten Medical drawing from a global pool of both capital and scientific expertise, the next generation of breakthroughs will likely be as much a feat of international logistics as they are of molecular biology.
As we look toward the remainder of 2026 and into 2027, the focus will undoubtedly shift from who has raised the most to who can deliver the most. The $15 billion deployed into these 50 companies carries the weight of patient expectations and the scrutiny of a capital-constrained market. If these firms can convert their record-breaking financing into clinical success, we are likely on the cusp of a golden age of drug discovery. If they falter, we may see a significant contraction in private biotech funding in the years to come.
For now, the message from the market is clear: if you have the data, the platform, and the partnerships, the capital is there to build the future of medicine.
Note: Figures reflect cumulative disclosed private equity through Aug. 12, 2026. Debt, grants, licensing, and collaboration payments are excluded from the cumulative equity totals. Data is derived from primary press releases and secondary, fully documented round chains.
About the Author