The biotechnology sector in 2026 has entered a period of profound transformation, marked by a recalibration of capital allocation and a renewed focus on modalities that promise to deliver "best-in-class" clinical outcomes. As of August 12, 2026, the private biotech market has demonstrated remarkable resilience, with record-breaking rounds continuing to support companies that bridge the gap between advanced computational biology and clinical-stage execution.
The Titans of Private Capital: Isomorphic Labs and the Independent Vanguard
In any objective analysis of funding, Alphabet-controlled Isomorphic Labs stands as a colossus. With $2.7 billion in external financing—bolstered by a staggering $2.1 billion Series B round announced in May—the company is effectively the best-funded entity in the drug discovery space. However, due to the structural reality that Alphabet retains at least 75% of its shares and voting rights, Isomorphic is classified as a corporate subsidiary rather than an independent startup.
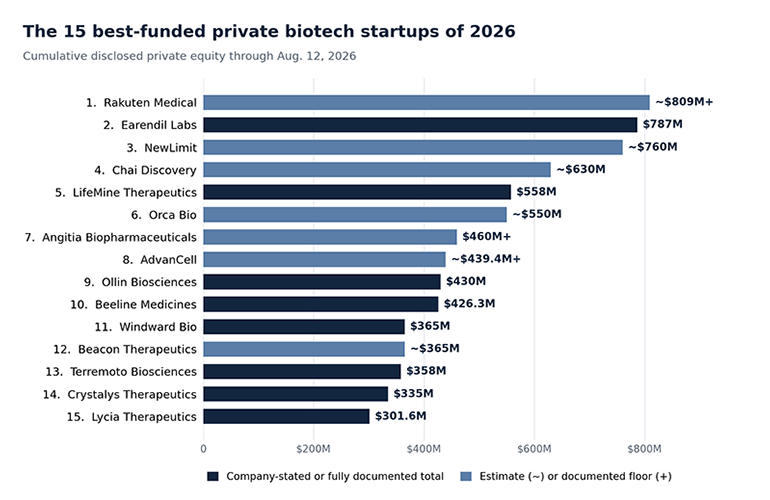
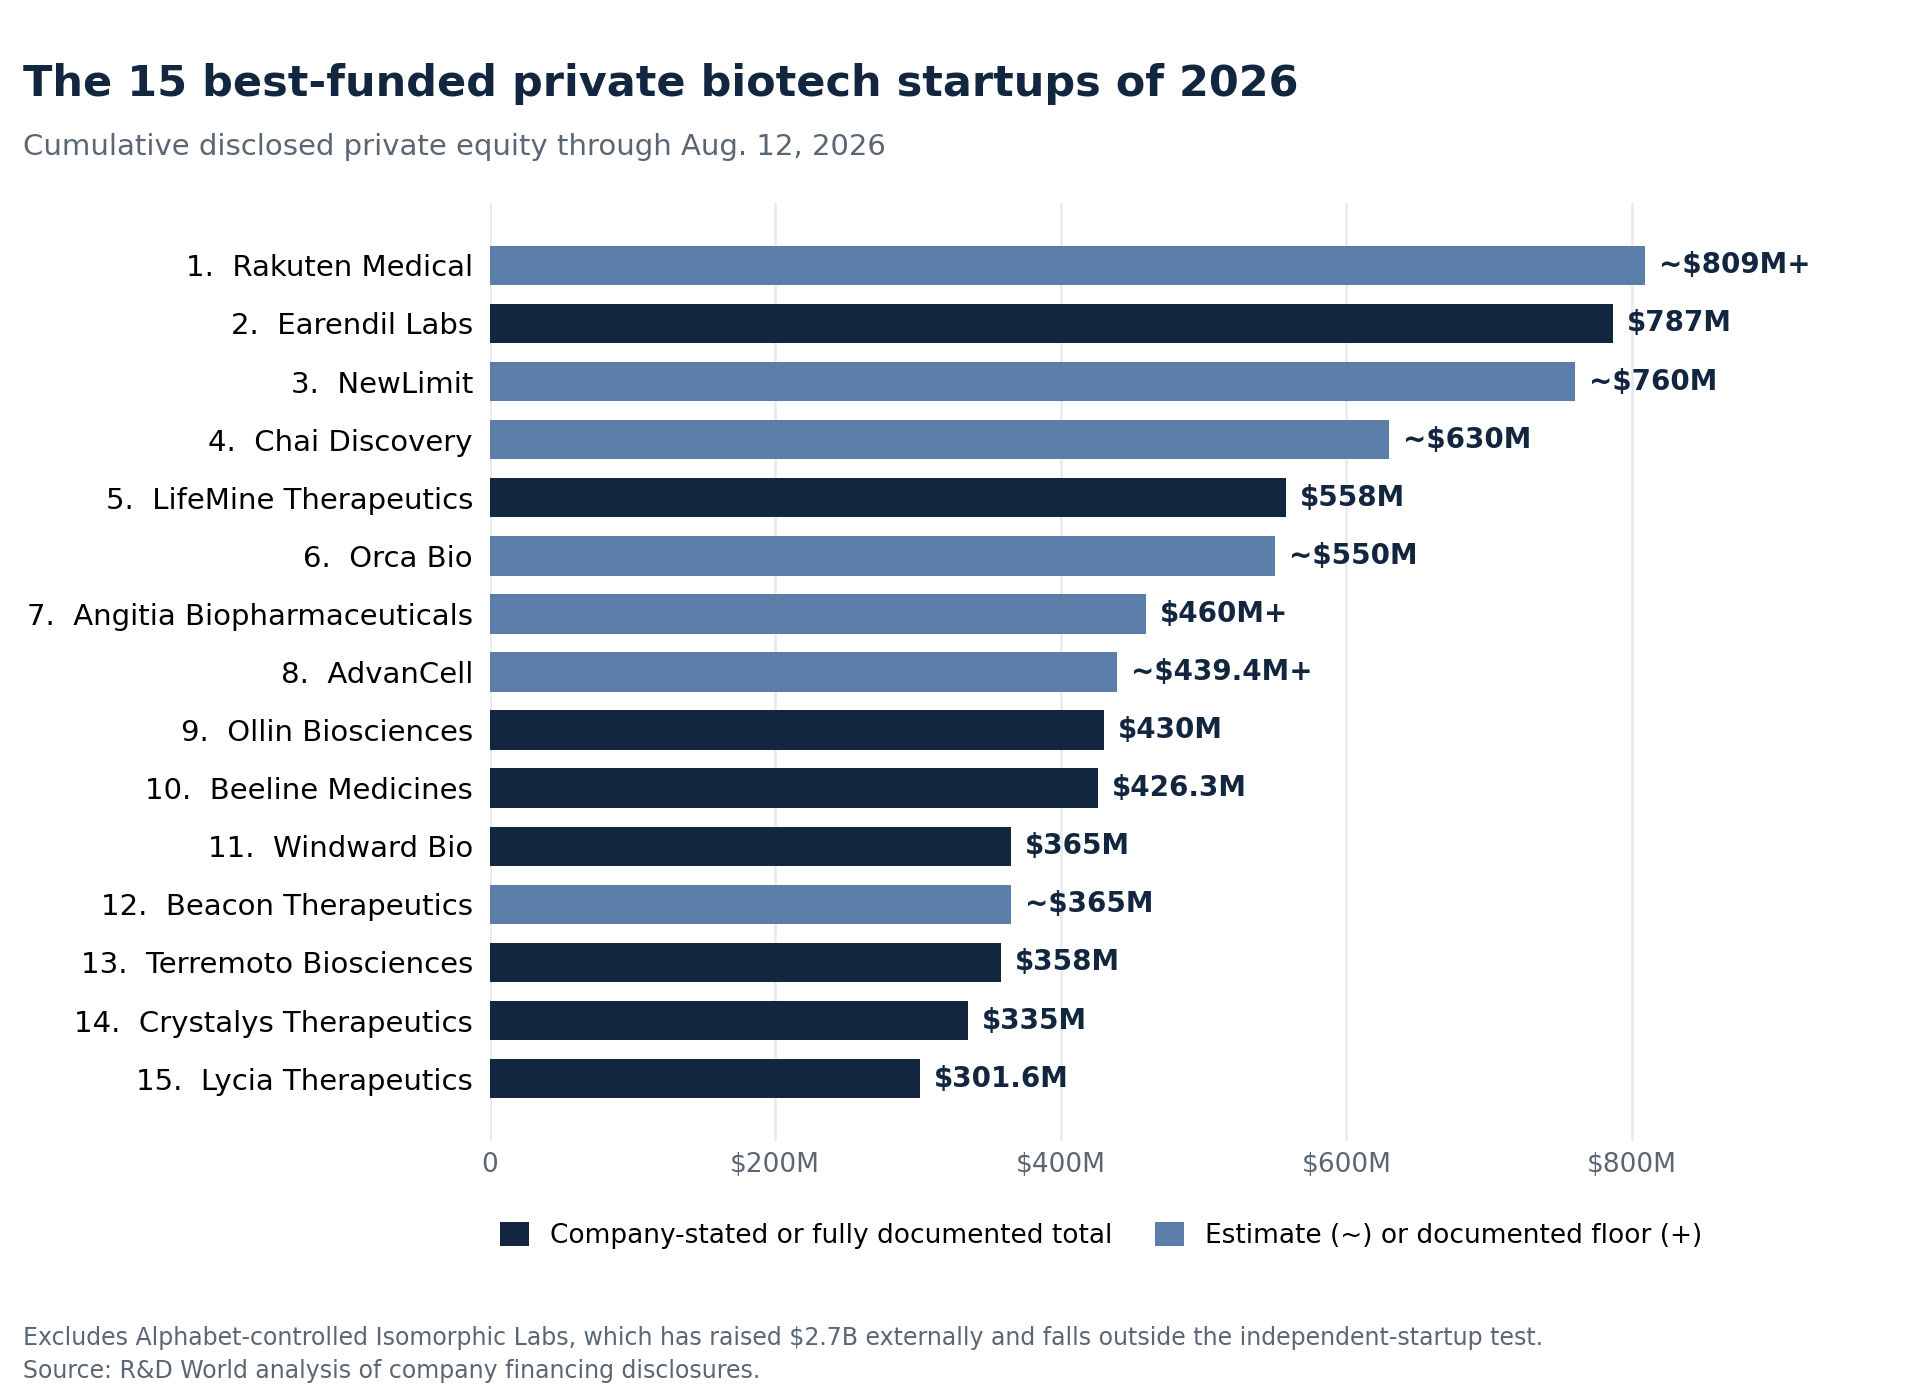
Excluding such corporate-backed giants, the title for the best-funded independent biotech of 2026 goes to Rakuten Medical. Having secured an oversubscribed $100 million Series F in January, the company has now amassed over $809 million in disclosed private funding. Rakuten’s focus on photoimmunotherapy represents a shift toward highly targeted, precision-based oncology, signaling that investors remain eager to back companies with late-stage clinical or near-commercial assets.
Following closely are Earendil Labs and NewLimit. Earendil, which reported $787 million in total financing as of March, is a prime example of the "AI-plus-biology" trend, having leveraged its R&D platform to secure a potential $2.56 billion partnership with Sanofi. Meanwhile, NewLimit, a venture targeting the biological mechanisms of aging through epigenetic reprogramming, secured a $435 million Series C in June, bringing its total to approximately $760 million. Backed by heavyweights like Founders Fund, Khosla Ventures, and Kleiner Perkins, NewLimit underscores the enduring VC appetite for high-risk, high-reward longevity science.
Chronology of Capital: Key Milestones from January to August 2026
The funding cadence throughout the first eight months of 2026 reveals a distinct pattern: large, late-stage infusions are being prioritized to accelerate clinical trial timelines.
- January: The year began with a flurry of activity. Rakuten Medical’s $100 million Series F set the tone, followed by Orca Bio’s $250 million Series F, which provided the company with the runway needed to prepare for commercialization of its allogeneic cell therapy platform.
- March: Earendil Labs’ $787 million financing announcement marked a major consolidation of capital into AI-driven biologics, proving that major pharma-biotech partnerships are increasingly being used as validation points to unlock massive private funding.
- June: This month proved to be one of the most active in the industry’s history. Beyond NewLimit’s $435 million haul, firms like Ollin Biosciences secured $330 million in a Series B to push forward Phase 3 development in ophthalmology, and Beeline Medicines closed a massive $426.3 million Series A extension, highlighting the immense value placed on immunology and autoimmune disease portfolios.
- July: AI-enabled molecular design firm Chai Discovery closed a $400 million Series C, its third financing round in under 12 months. This rapid accumulation of capital—totaling $630 million—speaks to the high-velocity environment for AI-native discovery platforms that have already demonstrated the ability to strike deals with pharmaceutical giants like Pfizer and Novartis.
- August: The period concluded with LifeMine Therapeutics securing a $188 million Series E. This round, supported by elite investors such as Bezos Expeditions and Gates Frontier, is specifically earmarked for advancing the clinical development of LIFE-001, an immunosuppressant designed for organ transplantation.
Supporting Data: Modalities and Market Trends
The internal composition of the top 50 list provides a diagnostic of where scientific innovation is concentrating.
Protein-Directed Medicine: The Dominant Modality
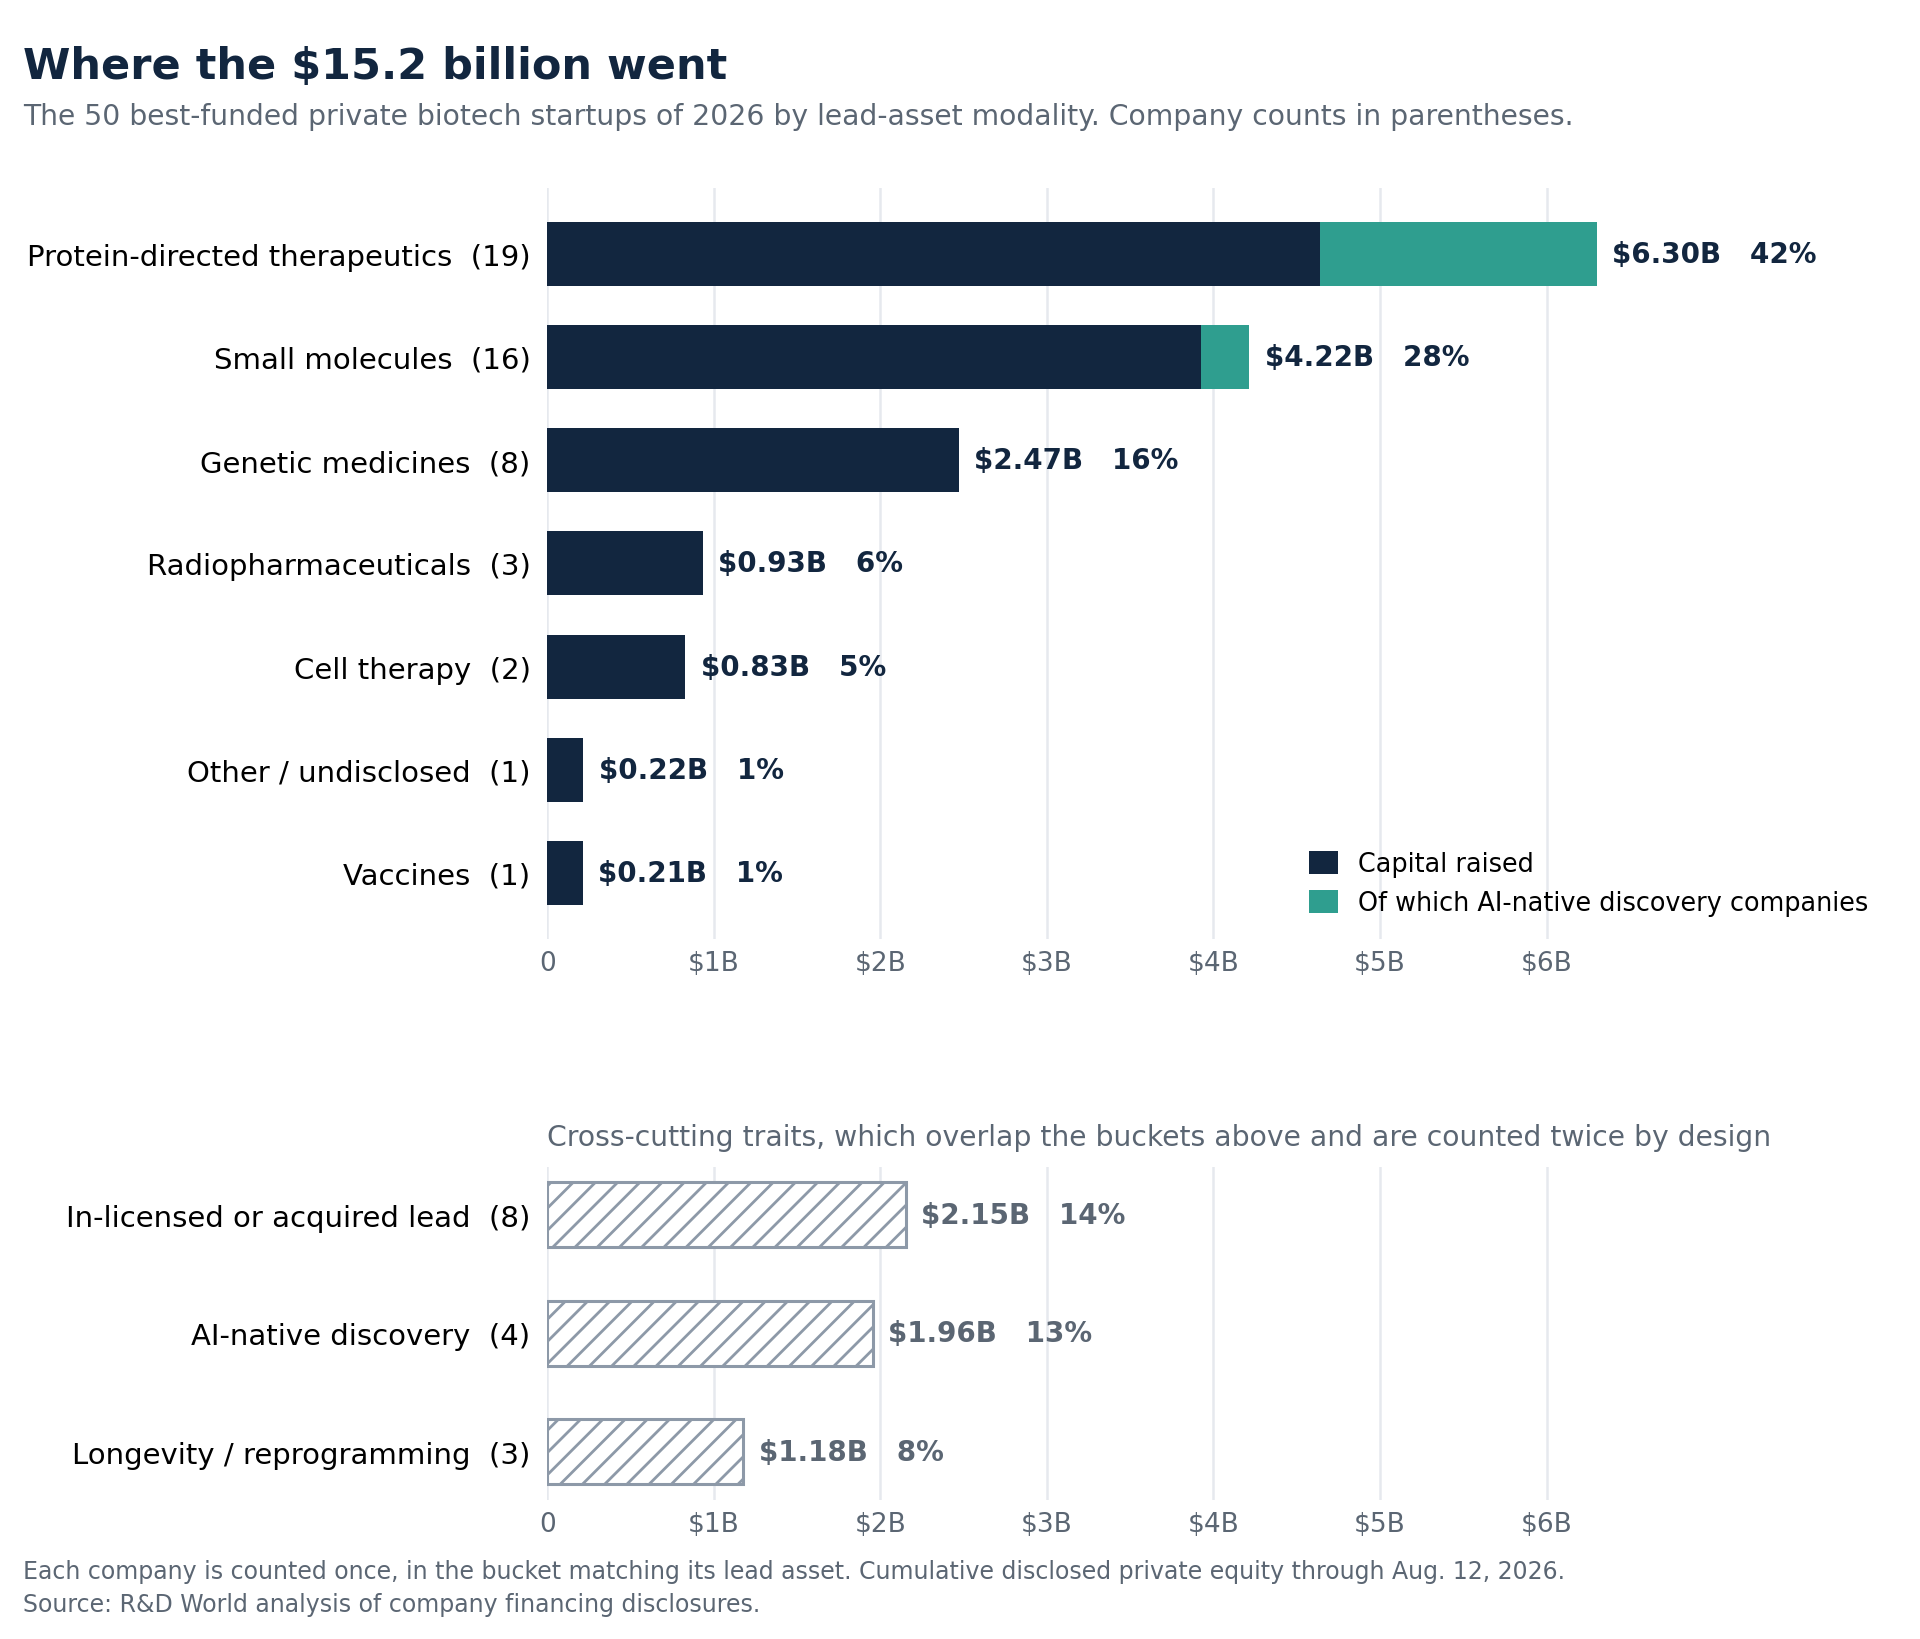
Protein work remains the bedrock of modern biotechnology. Nineteen of the top 50 companies—nearly 40% of the list—are dedicated to antibodies, multispecifics, antibody-drug conjugates (ADCs), peptides, or protein degraders. These companies represent a combined $6.3 billion in capital. This massive investment confirms that while "modality-of-the-month" trends fluctuate, the industry’s ability to manipulate protein structures remains the most reliable path to clinical success.
Genetic Medicine and Radiopharmaceuticals
Genetic medicines hold the second-largest share, with 11 companies accounting for $3.5 billion in funding. However, the most explosive growth in terms of interest relative to the number of players is seen in radiopharmaceuticals. Three firms—AdvanCell, Full-Life Technologies, and Ratio Therapeutics—have collectively raised $934 million, indicating a rapid market maturation for targeted alpha and beta-particle therapies.
The AI-Native Slice
Despite the pervasive hype surrounding AI, truly "AI-native" companies remain a lean group within the top 50. Only four companies on the list place AI at the core of their value proposition, accounting for $1.96 billion (roughly 13% of the total capital). This suggests that while AI is becoming a standard tool across the entire biotech sector, the companies that successfully monetize it as a standalone platform are few, typically those that have successfully translated algorithmic predictions into tangible, high-value pipeline assets.
Official Perspectives and Strategic Rationales
The motivations behind these financing rounds are clear: companies are moving away from purely "platform-based" narratives toward "product-led" growth.
Executives at companies like Chai Discovery and LifeMine have consistently emphasized that their funding is not merely for R&D overhead, but for the expansion of manufacturing infrastructure and the acceleration of Phase 2 and 3 clinical trials. For instance, the involvement of major strategic players like GSK and GV in LifeMine’s latest round signals a shift where venture capital and corporate venture capital (CVC) are increasingly acting in tandem to derisk assets before they reach the public markets.
Furthermore, the surge in capital for autoimmune and inflammatory diseases—as seen with Beeline Medicines and Triveni Bio—reflects a market pivot. With oncology becoming increasingly crowded, immunology has emerged as the "second front" where investors see the highest probability of creating next-generation, best-in-class therapies that offer clear differentiation from existing standards of care.
Implications for the Future of Biotech
The 2026 data suggests a "flight to quality" among venture capitalists. The era of easy money for early-stage, unproven platforms is largely over. Instead, the current cohort of top-funded companies shares three defining characteristics:
- Clinical Maturity: Most firms in the top 15 are either in late-stage clinical trials or have already established commercialization paths.
- Strategic Validation: The majority of these companies have successfully entered into multi-billion dollar partnership deals, providing independent verification of their technology’s efficacy.
- Capital Efficiency: Even with massive funding totals, these firms are utilizing capital to scale manufacturing and infrastructure, effectively behaving like "mini-pharma" companies rather than traditional venture-backed startups.
As we look toward the remainder of 2026 and into 2027, the primary question for these 50 companies is whether this massive infusion of capital will translate into successful IPOs or further M&A activity. The current trend suggests that the largest biotech players are effectively building the "new big pharma" from the inside out. By staying private longer and securing enough capital to reach definitive clinical milestones, these companies are positioning themselves to negotiate from a position of strength, whether they choose to remain independent or be acquired by established pharmaceutical giants.
For the broader industry, the lesson is clear: the integration of AI, the precision of protein-directed medicine, and the scalability of genetic and radiopharmaceutical platforms are no longer speculative concepts. They are the engine rooms of the modern bio-economy, and the capital flows of 2026 serve as the ultimate vote of confidence in their future.
About the Author