For over thirty years, the generic pharmaceutical industry operated on a singular, relentless mandate: achieve the lowest possible price through sheer manufacturing scale. This "cost-advantage" model defined the era, helping the U.S. healthcare system accrue $496 billion in savings in 2025 alone, according to the Association for Accessible Medicines (AAM). However, the machinery of this model is showing signs of structural failure. In an environment defined by supply chain fragility, consolidated purchasing power, and a shift toward complex specialty medicines, the old playbook—enter fast, manufacture cheap—is no longer a guarantee of sustainability.
Industry leaders, including Rahul Mittal, Head of Strategy and Innovation at Dr. Reddy’s Laboratories, are now arguing that the next frontier for generic manufacturers is not the race to the bottom, but the transition to "value advantage." This transformation hinges on four critical pillars: complex product mastery, radical supply reliability, the integration of "Pharma 4.0" digital manufacturing, and payer-aligned commercial strategies.
The Collapse of the Cost-Only Playbook
The traditional model of generic competition relied on the assumption that commoditization would drive efficiency. While this held true for simple oral solids, it has created a dangerous dependency on offshore active pharmaceutical ingredient (API) sources and thin-margin production.
Chronology of a Shift
- 1990s–2010s: The "Scale Era." Success was determined by the speed of entry upon patent expiry and the ability to squeeze pennies out of the production cost of small-molecule drugs.
- 2020–2024: The "Fragility Crisis." The COVID-19 pandemic and subsequent global supply chain disruptions exposed the dangers of over-reliance on concentrated, offshore manufacturing sites.
- 2025–2026: The "Value Pivot." As of September 2026, the American Society of Health-System Pharmacists (ASHP) reported 225 active drug shortages, forcing a reckoning. Hospitals are no longer just looking for the lowest price; they are looking for the drug that is actually available when needed.
The Cost of Shortages
The economic toll of the old model is becoming impossible to ignore. A Vizient analysis from June 2025 revealed that drug shortages cost U.S. hospitals nearly $900 million annually in labor expenses alone. When a drug is unavailable, healthcare staff spend valuable hours procuring substitutes, managing therapeutic changes, and navigating clinical delays. In this context, a "cheap" drug that is frequently out of stock is, in reality, an expensive burden on the healthcare system.
Supporting Data: The Changing Landscape of Competition
The market dynamics are shifting due to the consolidation of buying power. According to the AAM, three major buying groups now account for approximately 80% of U.S. generic retail purchases. This concentration limits the leverage of smaller manufacturers and makes price volatility a permanent fixture.
Furthermore, the "patent cliff" is being replaced by what some analysts call a "value cliff." IQVIA reports that 118 biologics are set to lose U.S. patent protection between 2025 and 2034, representing a $232 billion market opportunity. However, these are not simple pills; they are biologics, inhalation therapies, and long-acting injectables. These products require sophisticated formulation science and complex regulatory filings, creating a natural barrier to entry that favors manufacturers capable of high-level technical execution over those merely chasing volume.
Four Pillars of the Value Advantage
To survive the next decade, manufacturers are adopting a four-pronged strategy to differentiate themselves.
1. Mastering Complex Products
The era of the "simple generic" is receding. Modern growth is tied to products like depot injections, liposomal formulations, and drug-device combinations. The FDA’s Pre-ANDA program has become a vital resource here, offering guidance to manufacturers willing to tackle these complexities. Dr. Reddy’s entry into this space, highlighted by the February 2026 FDA acceptance of its abatacept biosimilar application, exemplifies the trend of moving toward high-barrier-to-entry products where competition is limited and price erosion is slower.
2. Reliability as a Competitive Product Feature
Reliability has moved from a back-office metric to a front-line commercial feature. Programs like Premier’s ProvideGx set a new standard by mandating transparency in API sourcing and supply chain resilience. Manufacturers that can provide "quality maturity indicators" and ironclad service-level commitments are successfully moving the conversation away from unit price toward "total system cost."
3. Pharma 4.0: The Margin Engine
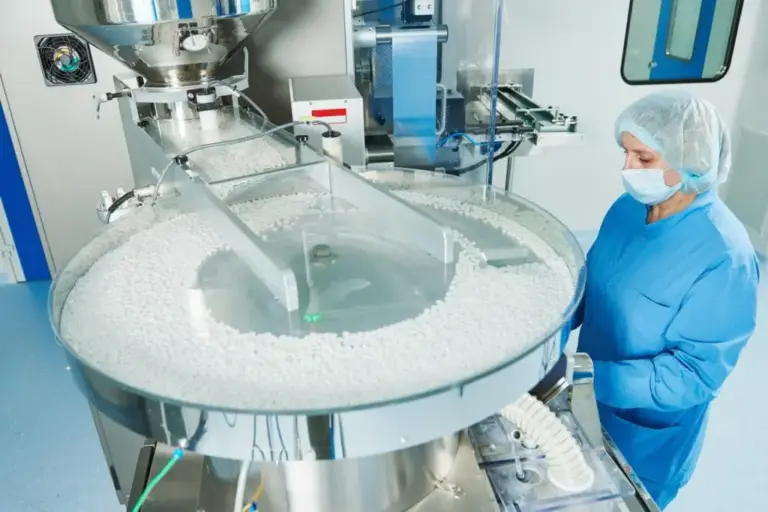
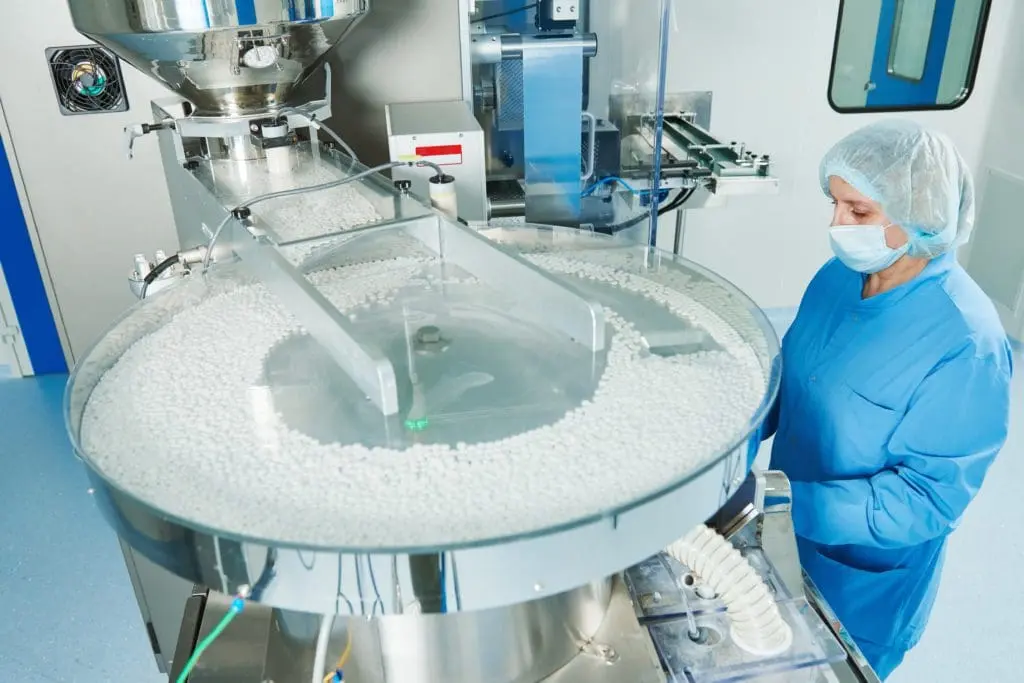
Advanced manufacturing is no longer a luxury; it is a necessity for margin protection. The implementation of "Pharma 4.0" technologies—such as digital twins, industrial IoT, and predictive analytics—allows for real-time release testing and significantly reduced cycle times. At Dr. Reddy’s Bachupally facility, these investments have led to a 30% reduction in production lead times, proving that digital transformation directly supports both profitability and supply consistency.
4. Payer-Aligned Contracting
Generic manufacturers must become experts in the complex reimbursement landscape. With only 24% of Medicare Part D plans covering first-generation generics launched in 2024, the "build it and they will come" approach is dead. Manufacturers now provide real-world savings models and evidence-based data on patient adherence to align their products with the goals of payers and pharmacy benefit managers (PBMs).
Official Responses and Regulatory Outlook
The FDA is actively facilitating this shift through programs like the Quality Management Maturity initiative and the Advanced Manufacturing Technologies Designation Program. These programs are designed to incentivize firms to move away from legacy manufacturing toward systems that prioritize consistency and availability.
"The FDA recognizes that the current market environment creates weak incentives for the production of lower-margin drugs," notes a recent regulatory brief. By providing clearer pathways for advanced manufacturing and complex generics, the agency is signaling that it prefers a stable, high-quality supply chain over the hyper-competitive, race-to-the-bottom dynamics that have plagued the industry for years.
Implications: The Road Ahead
The next 12 to 18 months will be a crucible for the pharmaceutical industry. Manufacturers that cling to the old model—prioritizing volume over technical excellence—will likely face increased margin pressure and regulatory scrutiny. Conversely, those that invest in the "value advantage" will find themselves in a unique position of influence.
Strategic Roadmap
- Portfolio Rebalancing: Shifting R&D investment from crowded, small-molecule markets toward biologics and complex formulations.
- Digital Integration: Scaling IoT and predictive analytics across the global manufacturing footprint to ensure "review-by-exception" becomes the standard.
- Outcome-Based Partnerships: Moving beyond volume-based sales to explore arrangements where reimbursement is tied to supply reliability and patient outcomes.
Conclusion: Price as a Tactic, Value as a Strategy
Rahul Mittal’s vision for Dr. Reddy’s—to reach 1.5 billion patients by 2030—encapsulates the industry’s new direction. Price remains a necessary lever, but it is no longer the primary engine of growth.
"We are moving toward a future where we compete on our ability to solve problems, not just on our ability to fill a bottle," Mittal notes. By combining the rigor of first-to-file biosimilar development with the precision of digital manufacturing, companies are attempting to redefine the role of the generic manufacturer. They are no longer just commodity providers; they are becoming essential partners in a healthcare system that is desperate for both affordability and, more importantly, stability.
As the industry traverses this transformation, the successful firms will be those that recognize that in the modern pharmaceutical landscape, value is not merely the absence of cost—it is the presence of reliability, innovation, and consistent patient access. The race to the bottom has reached its logical conclusion; the race for value has just begun.
About the Author