The intersection of artificial intelligence and pharmaceutical research has long promised a revolution in how humanity treats disease. Yet, for all the venture capital enthusiasm and the promise of "algorithmic breakthroughs," the stock market has offered a far colder reception to the first wave of AI-native drug developers. As the sector faces a reckoning, Iambic Therapeutics has emerged on the public markets with a distinct strategy, aiming to bridge the gap between high-tech computational promise and the hard-nosed realities of clinical execution.
The Market Context: A Sector in Transition
For several years, the narrative surrounding AI-driven biotechnology was dominated by soaring valuations and the allure of "big tech" speeds applied to biological discovery. However, the performance of early public entrants has been sobering.
Exscientia, once a darling of the AI-drug space, saw its share price crater—falling roughly 80% from its debut—before ultimately agreeing to a merger with rival Recursion Pharmaceuticals in 2024. Recursion itself, despite its prominence in the field, has struggled to maintain its initial public offering momentum, with its stock price hovering well below its $18 listing price, recently trading under $4.
These outcomes have fostered a climate of deep skepticism among institutional investors. The market is no longer satisfied with compelling slide decks or claims of "transformative algorithms." Instead, investors are demanding what they have always demanded of traditional biotech: tangible clinical progress, verifiable data, and clear pathways to regulatory approval.
Iambic’s IPO: A Measured Entry
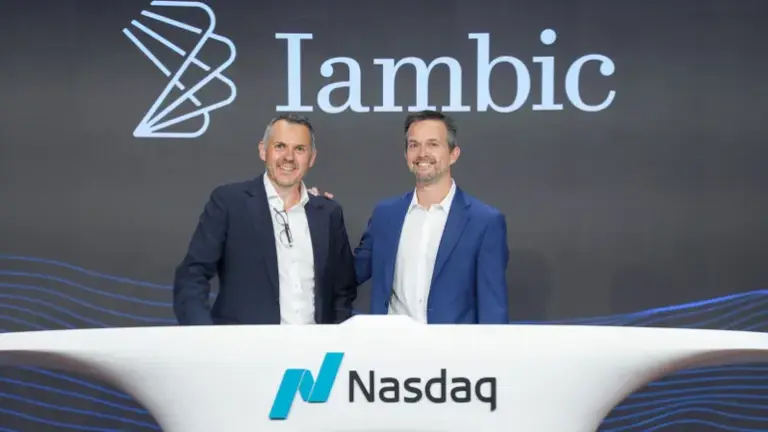
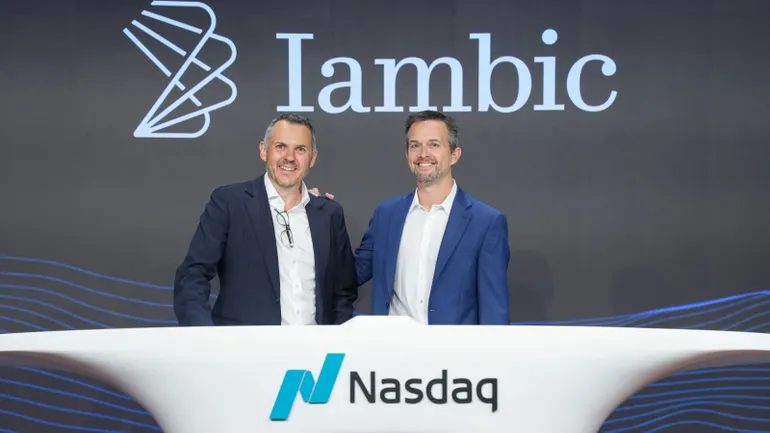
Against this backdrop, Iambic Therapeutics, founded in 2019, executed its own entry into the public markets earlier this week. The company successfully raised $150 million through an IPO, a respectable figure that nonetheless falls short of the massive "megarounds" seen in the private AI sector or the bumper crop of biotech IPOs from previous years.
Following its debut, Iambic’s shares saw a positive initial reaction, climbing more than 50% from its Wednesday pricing to reach approximately $24.50 by mid-Friday. Whether this rally signals a sustained shift in investor sentiment toward AI-biotech remains to be seen. Iambic’s leadership, however, frames the relatively modest IPO size not as a failure of ambition, but as a deliberate choice born of fiscal discipline. With over $270 million in cash on hand reported at the end of the last quarter—augmented by a robust series of strategic partnerships—the company argues that it is well-capitalized to reach its next major clinical milestones without needing to dilute shareholders excessively.
CEO Tom Miller on the "Execution Maturity" Mandate
In an exclusive interview with BioPharma Dive, Iambic co-founder and CEO Tom Miller articulated a philosophy that distances his company from the hyperbolic tendencies that have plagued the AI-drug sector. For Miller, the success of an AI biotech should be measured by the same metrics as a traditional pharmaceutical company: the ability to move molecules into human trials efficiently.
Success Measured in Molecules
"Technology is great," Miller noted. "We should be asking: Are you converting it to medicines?"
He points to the company’s lead candidate, IAM1363, a highly selective HER2 inhibitor for the treatment of solid tumors, which reached the clinic in less than two years. Iambic is already preparing for registrational trials in 2027, backed by data from more than 100 patients. By focusing on this "execution maturity," Miller believes Iambic provides a bridge for two types of investors: those who want to bet on the technology (the "tech thesis") and those who demand the clinical safety and efficacy of a traditional pharmaceutical firm (the "life science thesis").
The Role of Big Pharma Partnerships
Iambic has been notably aggressive in securing partnerships, including deals with industry heavyweights Takeda, AbbVie, and Bayer. While some critics argue that such deals are merely a way to add logos to a presentation, Miller rejects this notion.
"Iambic has never done it just for the logos on the slide," Miller emphasized. "We had already validated that we could deliver our own molecules to the clinic. We do these things because we think those partnerships make us stronger at our ability to develop our own wholly owned pipeline assets."
By embedding Iambic’s technology within the workflows of pharmaceutical giants, the company gains access to deep domain expertise and broadens its reach across therapeutic areas, including neurology, inflammation, and immunology—fields that extend well beyond the company’s internal oncology focus.
The "Disconnect" and the Future of AI Valuation
The current investment landscape is characterized by a stark disconnect. While public companies like Iambic face intense scrutiny, private-market AI players continue to command astronomical valuations. For instance, Alphabet’s Isomorphic Labs is reportedly in talks to raise funds at a valuation exceeding $40 billion, and Chai Discovery recently secured a $400 million Series C round.
This disparity raises a critical question: Are investors viewing Iambic through a different, perhaps more jaded, lens?
Miller argues that Iambic’s focus on the "molecule-to-molecule" reality of clinical development is the ultimate differentiator. He welcomes the comparison, noting that Iambic is prepared to go "AI model to AI model" or "partner to partner" with any entity in the space. However, he maintains that the path to becoming a "generational company" requires the innovation urgency of a tech startup coupled with the regulatory and operational rigor of an established pharmaceutical leader.
Implications for the Industry
The journey of Iambic Therapeutics represents a pivotal test for the broader "tech-bio" movement. The industry is currently moving past the era of unbridled hype and into a phase of clinical validation.
1. From Platform to Product
The primary implication is that "platform-first" companies are losing their luster. Investors are signaling that the underlying AI software is a commodity; the true value lies in the proprietary assets that emerge from those platforms. Companies that cannot demonstrate a robust, progressing clinical pipeline are likely to see their valuations continue to compress.
2. The Shift in Funding Models
The fact that Iambic chose to size its IPO with a focus on existing cash efficiency suggests a shift in the biotech funding narrative. The era of "growth at any cost" is fading, replaced by a preference for companies that can achieve clinical inflection points with leaner capital structures.
3. Collaboration as a Strategic Tool
The reliance on major pharmaceutical partnerships—a strategy Iambic has mastered—will likely become the standard for the next generation of biotech firms. These partnerships serve as a dual validation: they provide external scientific verification of the AI platform’s utility while simultaneously funding the development of the company’s own, wholly-owned assets.
Conclusion: The Long Game
As the dust settles on Iambic’s public market debut, the company’s trajectory will be watched closely. If Iambic can successfully translate its algorithmic prowess into successful clinical outcomes, it could provide a blueprint for how AI companies can survive the transition to public markets.
However, the shadow of predecessors like Exscientia remains long. The market is hyper-fixated on capital deployment, and any stumble in the clinical trial process will likely be met with swift and unforgiving punishment. For Tom Miller and his team, the focus remains clear: ignore the hyperbolic noise, prioritize the clinical data, and prove that in the world of drug discovery, the best algorithm is the one that cures the patient.
About the Author