For over thirty years, the generic pharmaceutical industry operated on a singular, unwavering mandate: produce at scale, enter the market with speed, and undercut the competition on price. This "race to the bottom" strategy was highly successful in democratizing access to medicine, with the Association for Accessible Medicines (AAM) reporting that generics and biosimilars saved the U.S. healthcare system a staggering $496 billion in 2025 alone.
However, the industry is now facing a profound structural shift. The old playbook—characterized by aggressive pricing in commoditized markets—is increasingly untenable. With supply chain fragility, consolidated purchasing power, and the rising complexity of patent-protected biologics, the next frontier for generic manufacturers is not cost, but value. Companies are now pivoting toward a multidimensional strategy that prioritizes supply chain resilience, technical sophistication, digital manufacturing, and payer-aligned access.
The Cracks in the Cost-Only Foundation
The traditional generic business model is buckling under the weight of its own success. According to a 2019 FDA analysis, the entry of six or more generic competitors typically drives prices down by more than 95% compared to the brand-name precursor. While this is a win for public health, it creates a "price erosion trap" for manufacturers.
This pressure is compounded by the consolidation of purchasing power. A May 2024 report submitted to the FTC and HHS revealed that just three major buying groups now account for nearly 80% of U.S. generic retail purchases. When a handful of entities control the vast majority of volume, manufacturers lose the leverage required to sustain operations for low-margin, high-complexity products.
Furthermore, the industry is grappling with a supply chain crisis. The heavy reliance on offshore Active Pharmaceutical Ingredient (API) and finished-dose manufacturers has exposed systemic vulnerabilities. The ASHP reported 225 active drug shortages as of September 2026. These shortages are not merely inconveniences; they are costly burdens on the healthcare system. A June 2025 Vizient analysis found that U.S. hospitals spent nearly $900 million annually in additional labor costs simply to manage the logistics and clinical fallout of drug shortages.
Chronology of a Shifting Landscape
- 2015: Biosimilars arrive in the U.S. market, marking the beginning of a complex, high-stakes era for non-originator drugmakers.
- 2019: The FDA releases findings confirming that deep generic competition leads to 95%+ price drops, signaling the limits of the "scale-only" model.
- 2022: Dr. Reddy’s Laboratories integrates its Bachupally plant into the World Economic Forum’s Global Lighthouse Network, signaling the start of the digital manufacturing revolution.
- 2024 (May): AAM highlights the extreme consolidation of U.S. purchasing power, underscoring the risks to market stability.
- 2025 (June): Vizient reports nearly $900 million in hospital labor costs linked to drug shortages, turning supply chain reliability into a top-tier clinical priority.
- 2025 (December): Dr. Reddy’s submits a BLA for an abatacept biosimilar, showcasing the shift toward complex biologics.
- 2026 (February): The FDA accepts the abatacept filing, marking a milestone in the transition toward value-added, complex pharmaceutical products.
The "Value Cliff": A $232 Billion Opportunity
As the industry moves away from simple oral solids, it is entering a period defined by the expiration of patents on high-value biologics and specialty medicines. IQVIA projects that 118 biologics will lose patent protection between 2025 and 2034, representing a $232 billion market opportunity.
This is no longer about simple chemical synthesis; it is about mastering "value-added medicines"—or "super generics." These include abuse-deterrent formulations, complex drug-device combinations (such as inhalers or autoinjectors), and modified-release therapies. Unlike standard generics, these products possess high barriers to entry, meaning fewer competitors and slower, more predictable price erosion.
Four Pillars of the Value Advantage
To survive and thrive in this new era, manufacturers are building their operations around four strategic pillars:
1. Mastering Complex Products
The future of the sector lies in depot injections, liposomal formulations, and ophthalmic inserts. These products require sophisticated engineering and advanced analytical methods. The FDA’s Pre-ANDA program has been a vital catalyst here, offering manufacturers the opportunity to clarify requirements with regulators before filing, thereby reducing the risk of failure in the complex, high-stakes development of biosimilars like abatacept.
2. Reliability as a Product Feature
Reliability is no longer a "nice-to-have"—it is a core product feature. Programs like Premier’s ProvideGx emphasize the necessity of sourcing diversity and transparent manufacturing sites. By providing health systems with quality maturity indicators and service-level commitments, manufacturers can shift the procurement conversation from "lowest price per unit" to "lowest total cost of care," where stability and availability take center stage.
3. Pharma 4.0 and the Margin Engine
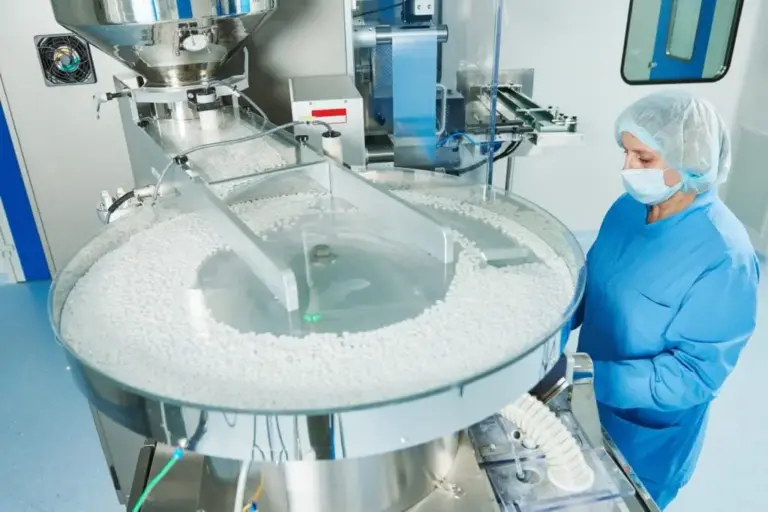
Digital transformation is the new engine for margin protection. By adopting continuous manufacturing, digital twins, and predictive analytics, manufacturers can significantly reduce variability. At Dr. Reddy’s Bachupally facility, the "Project OpsNext" initiative deployed industrial IoT and advanced analytics, resulting in a 30% reduction in production lead times and a 20% improvement in batch release turnaround. This is the definition of a value-based operation: using technology to ensure quality and speed simultaneously.
4. Payer-Aligned Contracting
The "build it and they will come" approach is ineffective in a market dominated by complex formulary design. Manufacturers must now engage in payer-aligned contracting. With Medicare Part D coverage for first-to-market generics averaging only 24% in recent years, manufacturers must provide real-world evidence, data on patient out-of-pocket costs, and support for adherence. The most successful firms are those creating channel-specific strategies that acknowledge the differing reimbursement landscapes of medical and pharmacy benefits.
Implications for the Future of Healthcare
The shift toward value-based manufacturing has profound implications for both the industry and the patient.
For the healthcare system, the move toward "Pharma 4.0" and improved supply chain transparency could mitigate the recurring crisis of drug shortages, saving hospitals hundreds of millions in labor costs and ensuring patients have consistent access to life-saving medication.
For the manufacturer, the implications are equally significant. The era of the "generic commodity" is being replaced by the era of the "technical partner." Success will no longer be measured by volume alone, but by the ability to navigate regulatory, supply, and commercial hurdles on "day one" of a product’s launch.
Official Perspective: Price as a Tactic, Value as a Strategy
Rahul Mittal, Head of Strategy and Innovation at Dr. Reddy’s Laboratories, emphasizes that price remains a necessary lever but is no longer the primary driver of sustainable success. "Price will remain a lever in generics," Mittal notes. "The manufacturers best placed to last are those that pair it with complex products, dependable supply, digital manufacturing, and payer-ready evidence."
Dr. Reddy’s stated goal of reaching 1.5 billion patients by 2030 hinges on this transition. By focusing on first-to-file biosimilars and integrating digital manufacturing across its global footprint, the company is effectively mapping out a roadmap for the rest of the industry.
The Road Ahead (12–18 Months)
As we look toward the next year and a half, the focus will intensify on three specific areas:
- Regulatory Readiness: Increased utilization of the FDA’s Advanced Manufacturing Technologies Designation to speed up the rollout of resilient, high-quality production lines.
- Biosimilar Education: A massive effort to educate providers and payers on the clinical equivalence of biosimilars to overcome the inertia of rebate-driven formulary designs that currently favor legacy brand-name drugs.
- Inventory Resilience: A fundamental restructuring of inventory management to ensure that "just-in-time" supply chains are bolstered by "just-in-case" buffer stocks, particularly for critical hospital-administered products.
The transition from a cost-based model to a value-based model is a maturation of the generic industry. As the line between "generic" and "specialty" continues to blur, the winners will be those who view their role not as simple suppliers, but as essential pillars of a reliable, patient-centered, and technologically advanced global health infrastructure.
About the Author