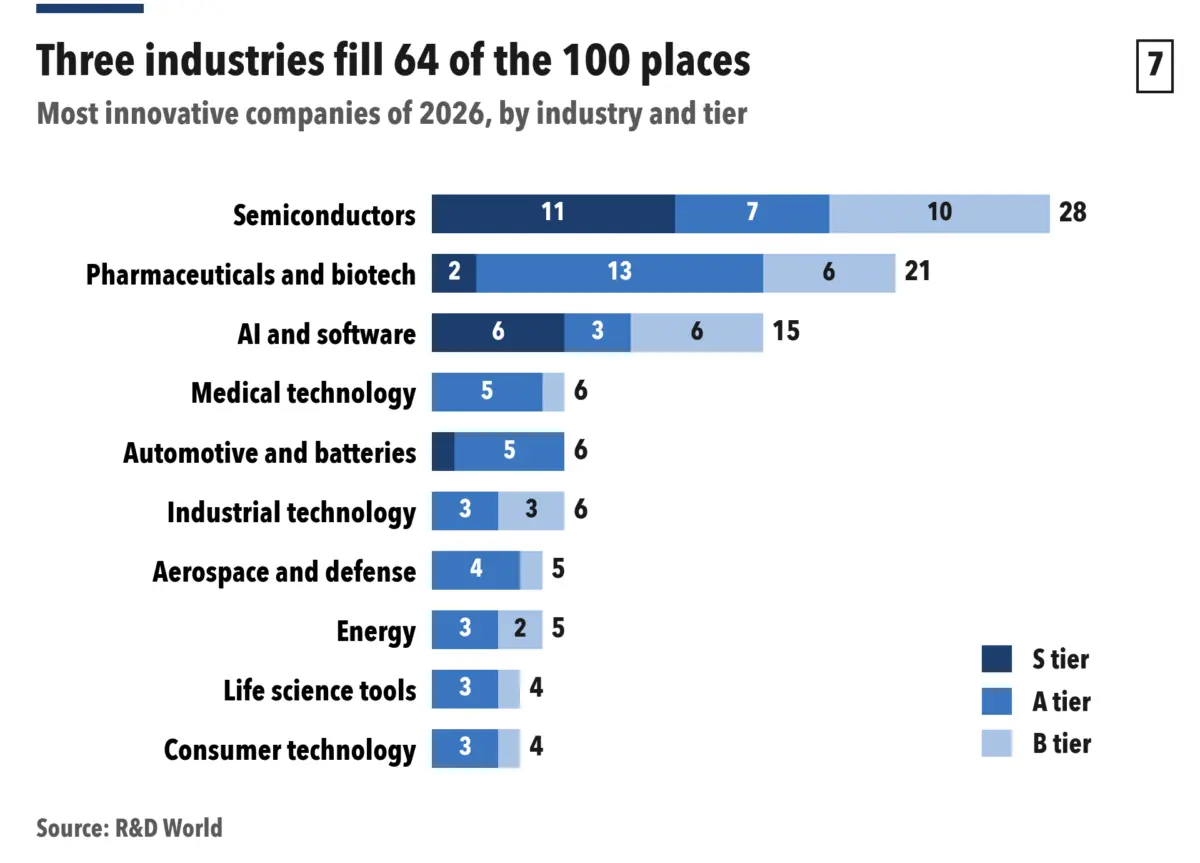
The boundary between Silicon Valley and the pharmaceutical sector is no longer a porous membrane; it is effectively dissolving. As Alphabet and Meta funnel unprecedented billions into research and development, their spending has reached a point of parity with the world’s most powerful drugmakers. This shift marks a tectonic transformation in global R&D, signaling that the future of medicine will be written not just in wet labs, but in data centers and through the lens of frontier artificial intelligence.
The Financial Pivot: A Shift in R&D Hegemony
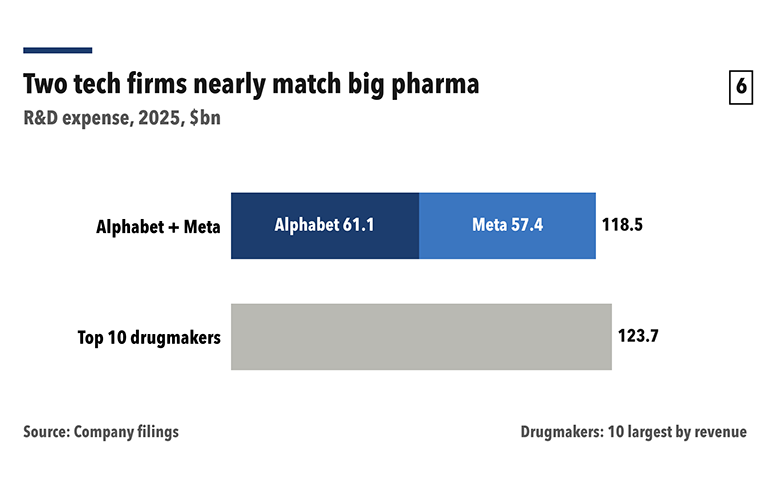
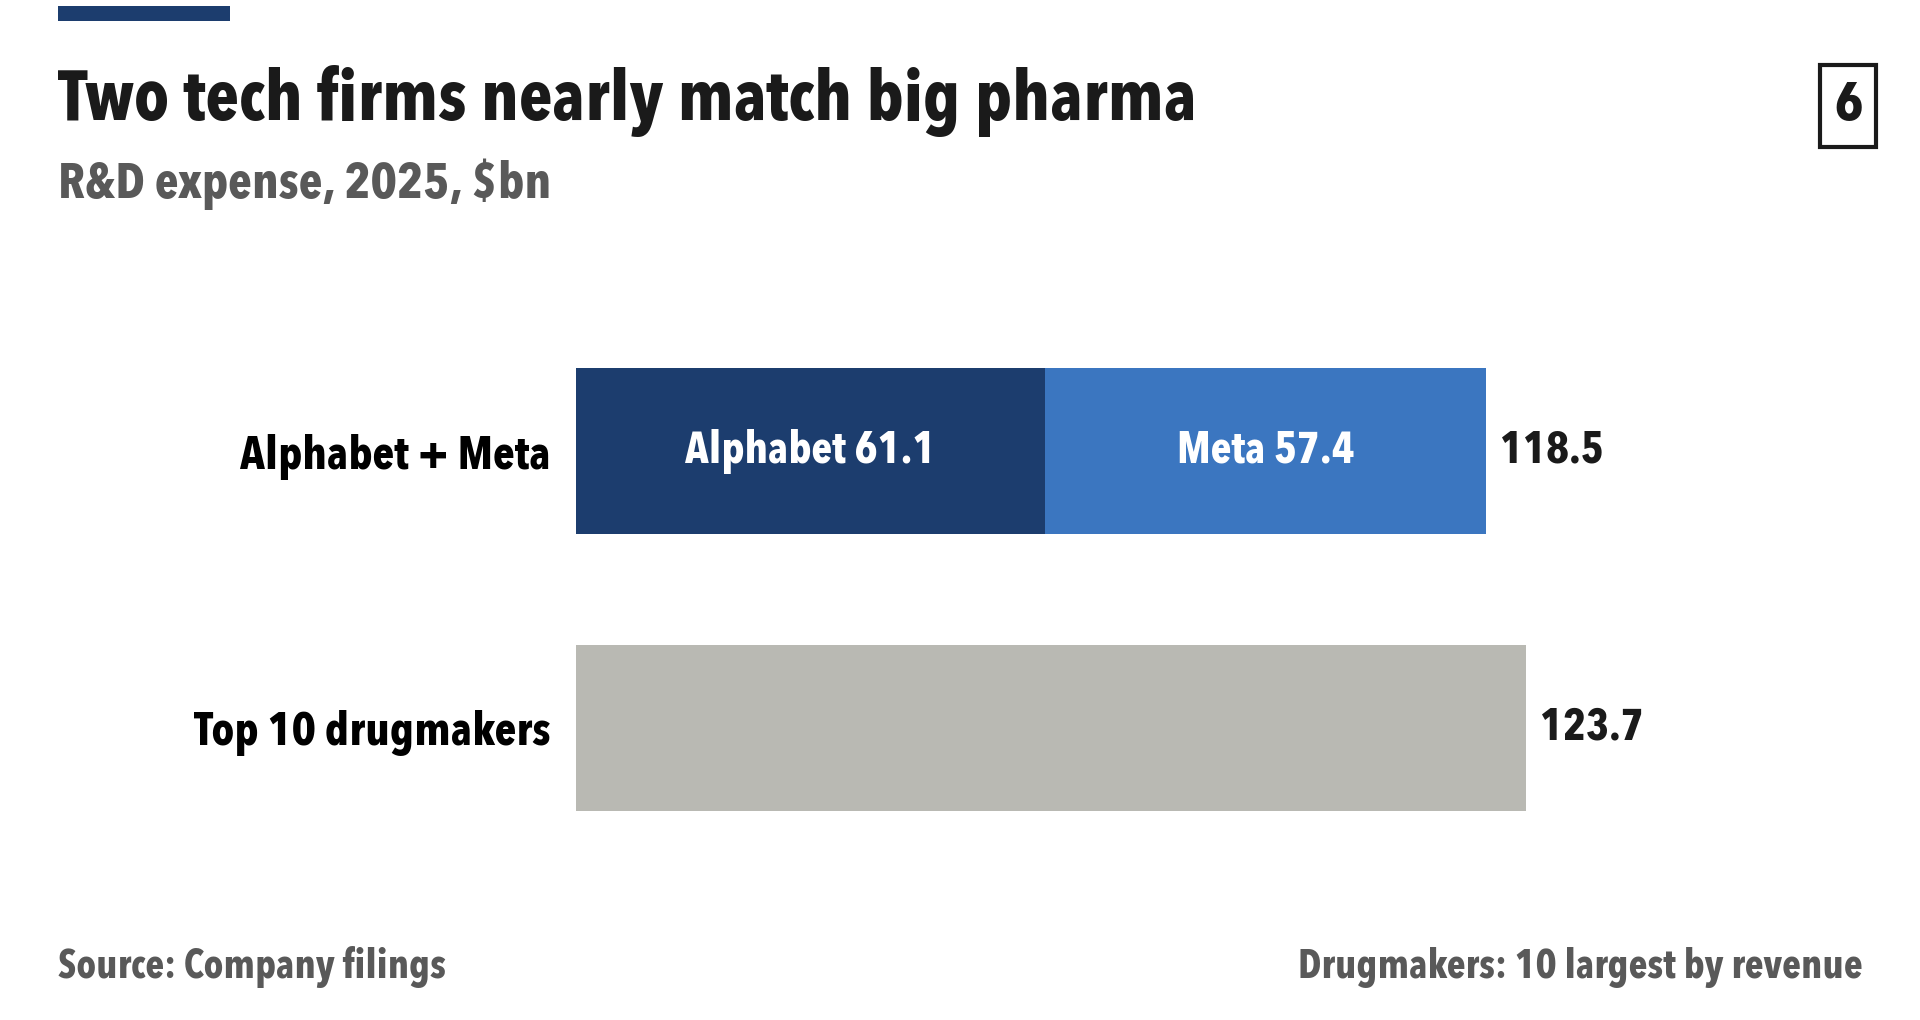
For decades, the pharmaceutical industry held the undisputed crown for R&D expenditure. However, 2025 data paints a startling picture of a new power dynamic. Alphabet and Meta reported a combined $118.5 billion in R&D investment for the year. When measured against the 10 largest global drugmakers—whose collective spend, including J&J’s medtech and Roche’s diagnostics, sat at $123.7 billion—the gap has narrowed to a mere sliver.
This is not merely a story of Big Tech’s expansion; it is a story of a structural evolution. In 2013, the landscape looked entirely different: Merck’s $7.5 billion R&D budget comfortably outpaced Google’s $7.1 billion. By 2025, that ratio had inverted violently. Alphabet alone spent $61.1 billion, nearly four times the $15.8 billion allocated by Merck.
This financial divergence suggests that the "heavy lifting" of scientific discovery—simulations, protein folding, and predictive molecular design—has become a computational challenge, effectively moving the center of gravity toward firms with the most robust cloud infrastructure and AI talent pools.
Chronology of the Tech-Pharma Integration
The convergence of these two industries has been marked by a series of strategic milestones:
- 2013: The last era of "parity," where Merck’s R&D spend marginally exceeded Google’s.
- January 2026: Eli Lilly and NVIDIA announce a landmark co-innovation lab in the Bay Area, backed by a $1 billion investment over five years.
- February 2026: Lilly’s "LillyPod" supercomputer goes live in Indianapolis, allowing the company to run NVIDIA’s 550-billion-parameter Nemotron 3 Ultra model on-premises.
- March 2026: Roche integrates 2,176 Blackwell GPUs into its infrastructure, boosting its total capacity to over 3,500 units.
- April 2026: OpenAI launches GPT-Rosalind, a specialized life-sciences model, while Merck inks a $1 billion multi-year alliance with Google Cloud.
- May 2026: Isomorphic Labs secures $2.1 billion in funding, signaling immense investor confidence in AI-native drug discovery.
- September 2026: Novo Nordisk formalizes a partnership with Anthropic, marking its third major AI-sector deal of the year. Simultaneously, Anthropic confirms the establishment of a physical biology lab in the Bay Area.
Supporting Data: The New Infrastructure of Discovery
The integration is not just about partnerships; it is about physical and digital infrastructure. Leading pharmaceutical companies are effectively becoming "AI factories."
Bristol Myers Squibb is currently commissioning its second NVIDIA-powered supercomputer, utilizing Vera Rubin systems to build upon the momentum of their first DGX SuperPOD. Meanwhile, Eli Lilly’s adoption of a "no token limit" model for their internal AI systems has already yielded tangible results. Chief AI Officer Thomas Fuchs reported that their foundation model has successfully co-designed a small-molecule candidate featuring a novel chemical fragment, proving that the digital infrastructure is directly influencing the discovery of physical assets.
Furthermore, the rise of "Frontier AI" labs as independent players in the biology space adds a new layer of complexity. Anthropic’s acquisition of Coefficient Bio for $400 million, coupled with the hiring of former Genentech computational biologists, signals that AI labs are no longer just service providers—they are competitors in the preclinical landscape. By targeting disease areas that traditional drugmakers often bypass for financial reasons, these AI-native firms are potentially opening new markets for drug discovery.
The Official Narrative: Bridging the Gap
Leaders in both fields have articulated a vision of "shared intelligence." For the pharmaceutical giants, the value proposition of partnering with companies like Google, NVIDIA, and OpenAI is clear: the ability to scale research workflows across thousands of employees.
When Bristol Myers Squibb rolled out Claude Enterprise to 30,000 employees, it wasn’t just for coding or document summary; it was to create a shared intelligence platform spanning research, development, manufacturing, and commercial operations.
"We are moving from a world where we test in a dish to a world where we test in a simulation," noted an industry analyst involved in the recent Global R&D Funding Forecast. This sentiment is echoed by the move toward "agentic AI"—systems capable of performing complex multi-step workflows. Genmab’s partnership with Anthropic to build custom, agentic AI agents for clinical development represents the next stage of this evolution, where the AI serves as a proactive researcher rather than a reactive tool.
Strategic Implications: What Happens Next?
The marriage of Big Tech and Big Pharma carries profound implications for the global economy and human health:
1. The Rise of "Computational Biology" as the Standard
Drug discovery is increasingly becoming a computational bottleneck issue. Companies that fail to secure high-performance computing (HPC) resources or proprietary LLMs will find themselves at a structural disadvantage. We are seeing a "tiering" of the industry where the "haves"—those with direct access to GPU clusters—can iterate on drug candidates at speeds previously thought impossible.
2. The Question of Intellectual Property (IP)
As Anthropic and OpenAI move deeper into the wet lab and preclinical space, the traditional pharma model of proprietary IP is being challenged. If an AI model trained on public and private data designs a molecule, who owns the resulting drug? The influx of tech-native talent into these spaces suggests that the legal frameworks governing drug patents will need a complete overhaul to accommodate AI-generated intellectual property.
3. The Shift in Financial Risk
The $2.1 billion funding round for Isomorphic Labs and the $1 billion Merck-Google deal highlight that capital is shifting toward AI-enabled biotech. By reducing the failure rate in the early stages of drug discovery, these companies hope to lower the overall cost of R&D—a cost that has historically been the primary driver of high drug prices.
4. Regulatory and Ethical Hurdles
The move by companies like Anthropic to run their own preclinical programs—while simultaneously acting as a vendor to companies like Novo Nordisk—creates a complex landscape of potential conflicts of interest. Regulators will be forced to scrutinize whether the "black box" nature of these AI models provides enough transparency to ensure patient safety in clinical trials.
Conclusion: A New Frontier
The data from 2025 and 2026 suggests that the "Tech-Pharma" hybrid is not a temporary trend but the new status quo. As companies like Google and Meta leverage their massive computational budgets to unlock the secrets of biology, the traditional pharmaceutical sector is evolving from a laboratory-centric industry to one defined by data, cloud-scale compute, and artificial intelligence.
Whether this transition will result in a faster, cheaper, and more effective pipeline of life-saving medicines remains the trillion-dollar question. However, one thing is certain: the era of the lone, bench-top scientist has been supplemented—and in many cases, eclipsed—by the era of the AI-driven supercomputer. The race to decode human biology is now officially a race to dominate the digital infrastructure of intelligence.
About the Author